

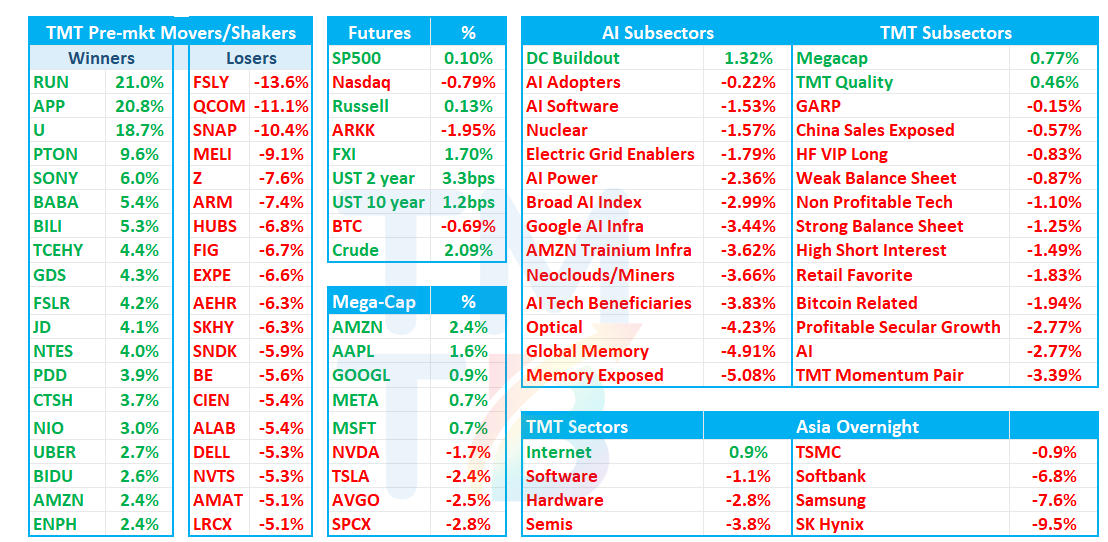
Good morning. QQQs - 80bps with more follow through to yesterday’s price action as Semis -4% early with many names already down 5%+ as charts continue to break down (see our EOD wrap from yesterday for our thoughts). Rotations continuing early this morning as hyperscalers outperforming again (AMZN +2%). Software -1% after misses from HUBS -9% and FIG -6% have app sw weaker, while Internet +1% is the bright spot again. U +20% and APP +23% after both put up huge quarters and currently in a factor sweet spot. COHR -3% was decent but selling off with the rest of semis. ARM -7.5% another royalty miss despite increasing confidence in their over $2B #. EXPE -7% on a weaker Q4 guide.
Asia mixed overnight: TPX +1.16%, NKY -1.79%, Hang Seng +3.67%, HSCEI +3.87%, SHCOMP +0.1%, Shenzhen +1.59%, Taiwan TAIEX -3.2%, Korea KOSPI -5.28%. Softbank/Sammy/Hynix all down 7-10%.
We’ll hit recaps from APP, HUBS, ARM, EXPE, and FIG then onto the usual.
Lots to get to, so lets get to it…
EARNINGS
APP 3Q26: Next-Gen Model, Only Partly Rolled Out, Re-Accelerates Gaming to ~50% and partially helps flip the Share-Loss Narrative
Overall, a very solid print for what was a somewhat a crowded HF short coming into the print and a stock that has derated to a mid teens p/e multiple. Used to be LO darling but has been largely de-grossed — likely needs another good print to get its mojo back, but this was a good start.
Gaming, where bears saw share loss to U, was the bright spot. It grew nearly 50% y/y (their first gaming growth disclosure in a year) on a partial rollout of new ad models, driving most of the 3Q beat ($2.185B vs. ~$2.10-2.12B bogeys), first acceleration after four straight decels (although the 2 yr stack decel’d) and biggest beat vs. street since 1Q’25. The 4Q guide, counting only model gains already live, beat bogeys on revs ($2.38B mid vs. ~$2.33-2.36B) and EBITDA ($2.01B vs. ~$1.93-1.96B). Foroughi said share-loss checks “tend to end up being flawed” and called 2Q’s miss “our own foot fault,” but mgmt gave no take rate, gaming vs. consumer split, full-rollout timing or e-com revenue: “You sort of have to make your own guesses.” Foroughi called the 3Q model rollout “a model transition as significant as Axon 2.0,” and asked if it’s Axon 3.0, put it on that level “from a technology standpoint in terms of technical complexity.” It’s “still in partial rollout,” the 4Q guide counts only gains “already live,” and there’s no timing on the full rollout.
The nits are the 4Q guide’s +8-10% q/q (vs. +14% in 3Q), but their usual ~5.5% beat on the mid would take 4Q to ~+15% q/q. No 2027 number, but 2026 now tracks to ~$8.33B (nine months reported plus the 4Q guide), so Street’s ~$10.1B for 2027 assumes just +21% growth, well short of the “roughly 30%” a year Foroughi says the business can compound at long term. At 30%, 2027 revenue would be ~$10.8B. Overall, much better than feared after U/META share-loss scare, and the higher base de-risks 2027 and likely gets some nascent bulls back on board hoping for e-com to ramp and beats to continue in ‘27. Bulls will say APP can grow revenue ~30%+ in CY27 and deserves high teens CY27 EV/EBITDA which = ~$500+.