

Good afternoon. Another wild day in Tech land as QQQs +1% rallied as much as +2.5% by the early morning before grinding lower all afternoon. SPY was a lot better, +1.6% on the day and VIX fell 2-3 pts. The story of the day was rotation, rotation, rotation! Less risk on or risk off, and more “risk-somewhere-else” as investors reacted to last night’s blue tsunami and a slower DC buildout means for semis (TLDR: not good)
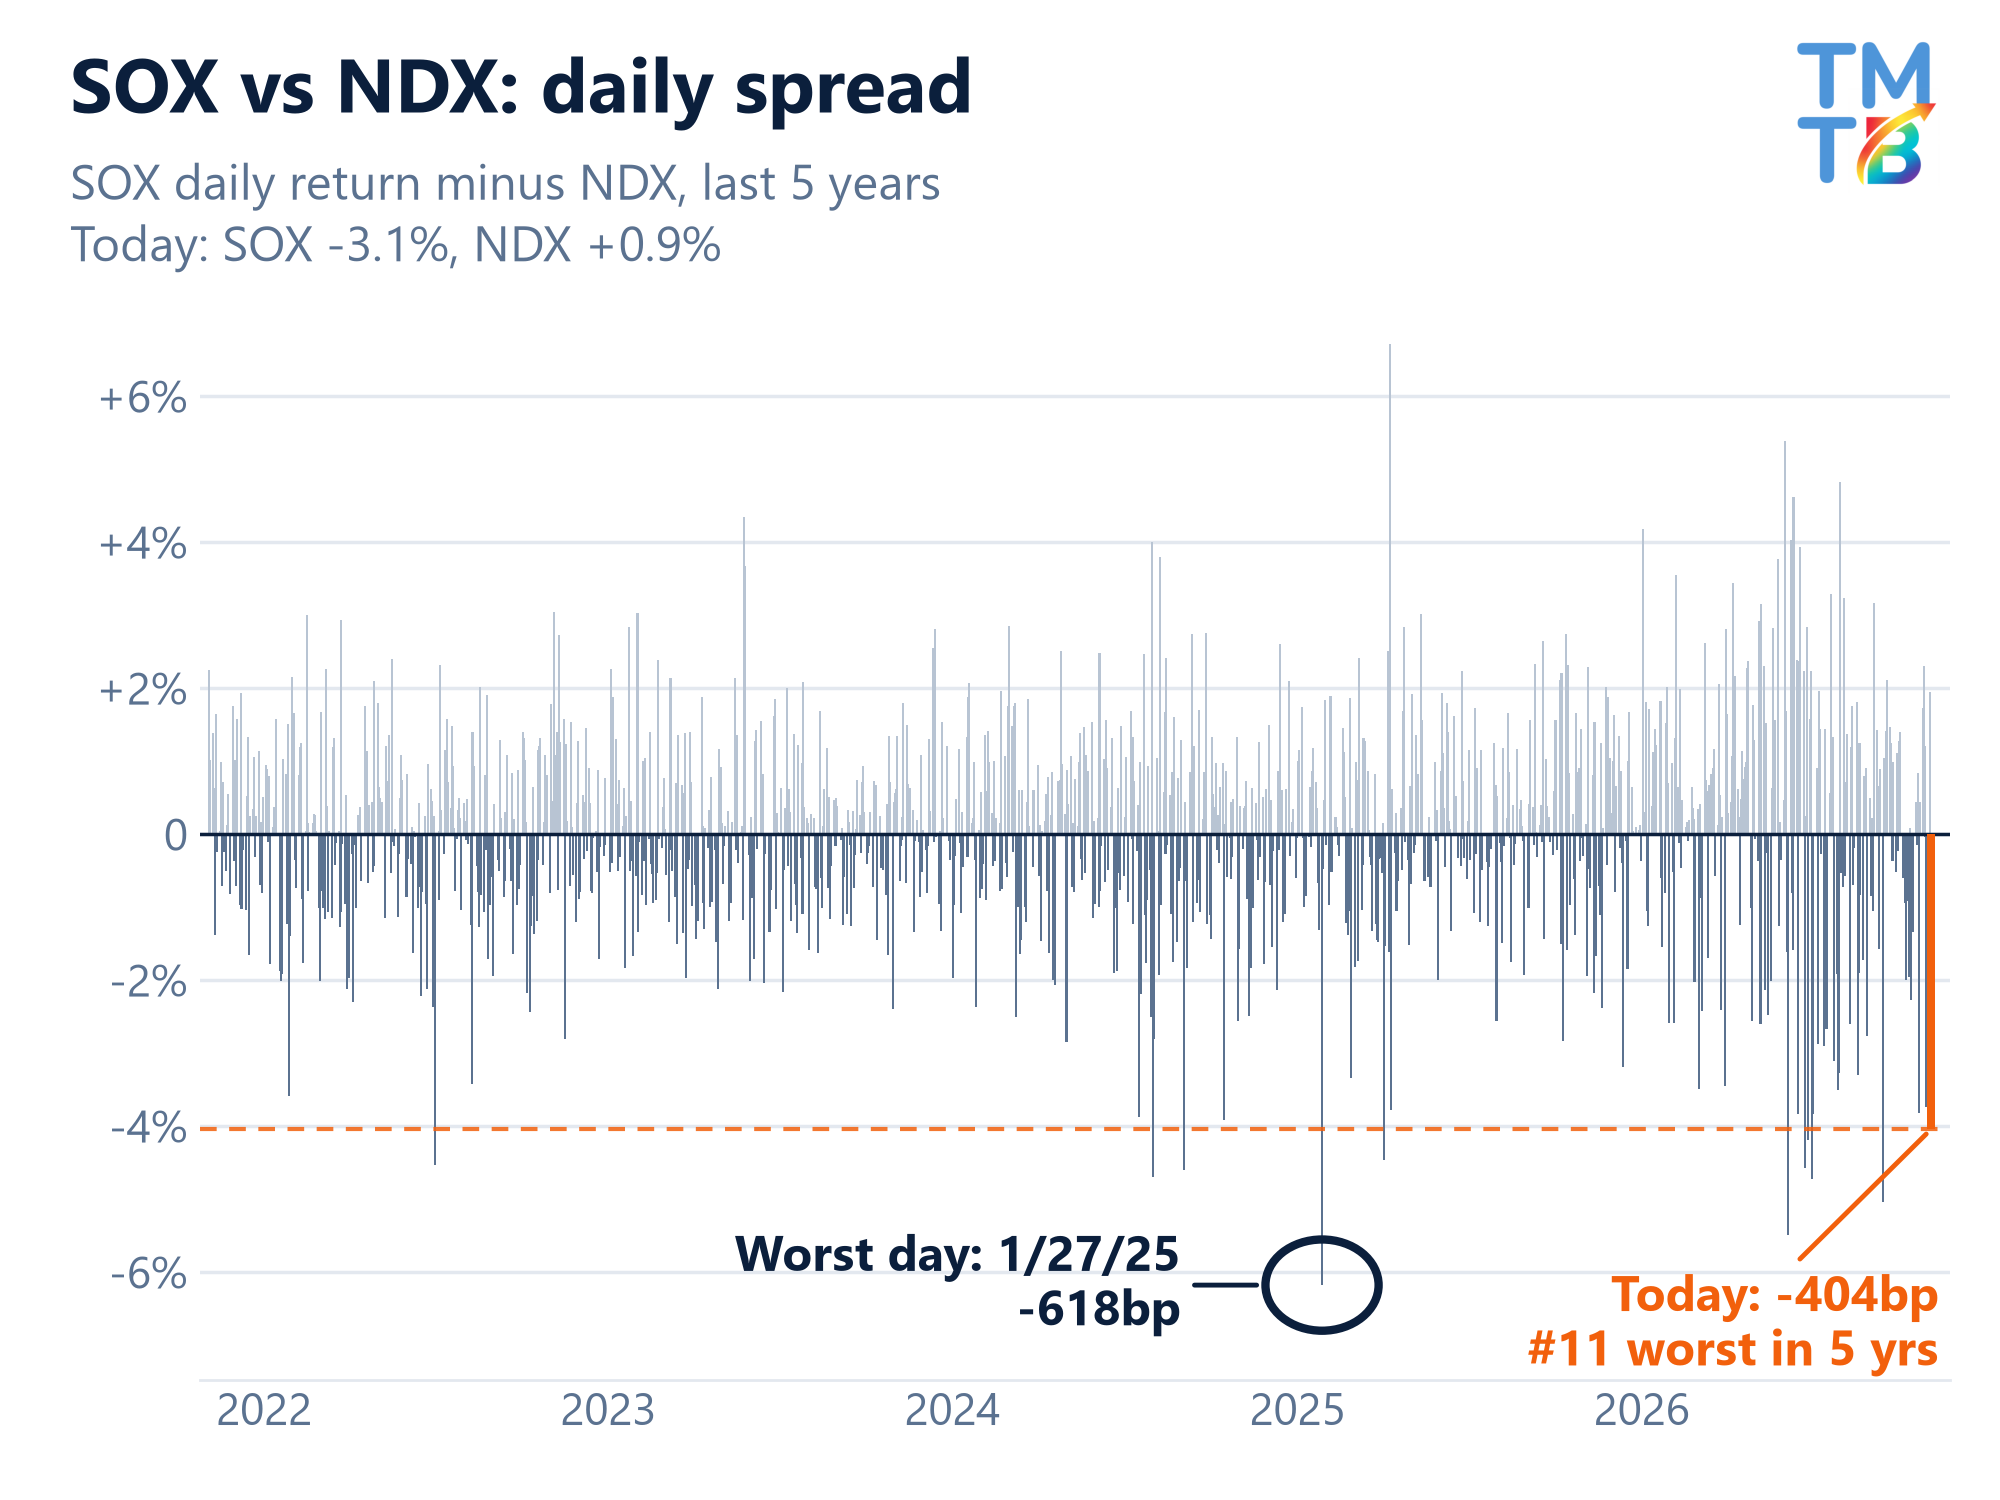
Semis -3% opened green and bled all day (down as much as -5%), underperforming QQQs by 4%, the 11th largest spread in the last 5 years:
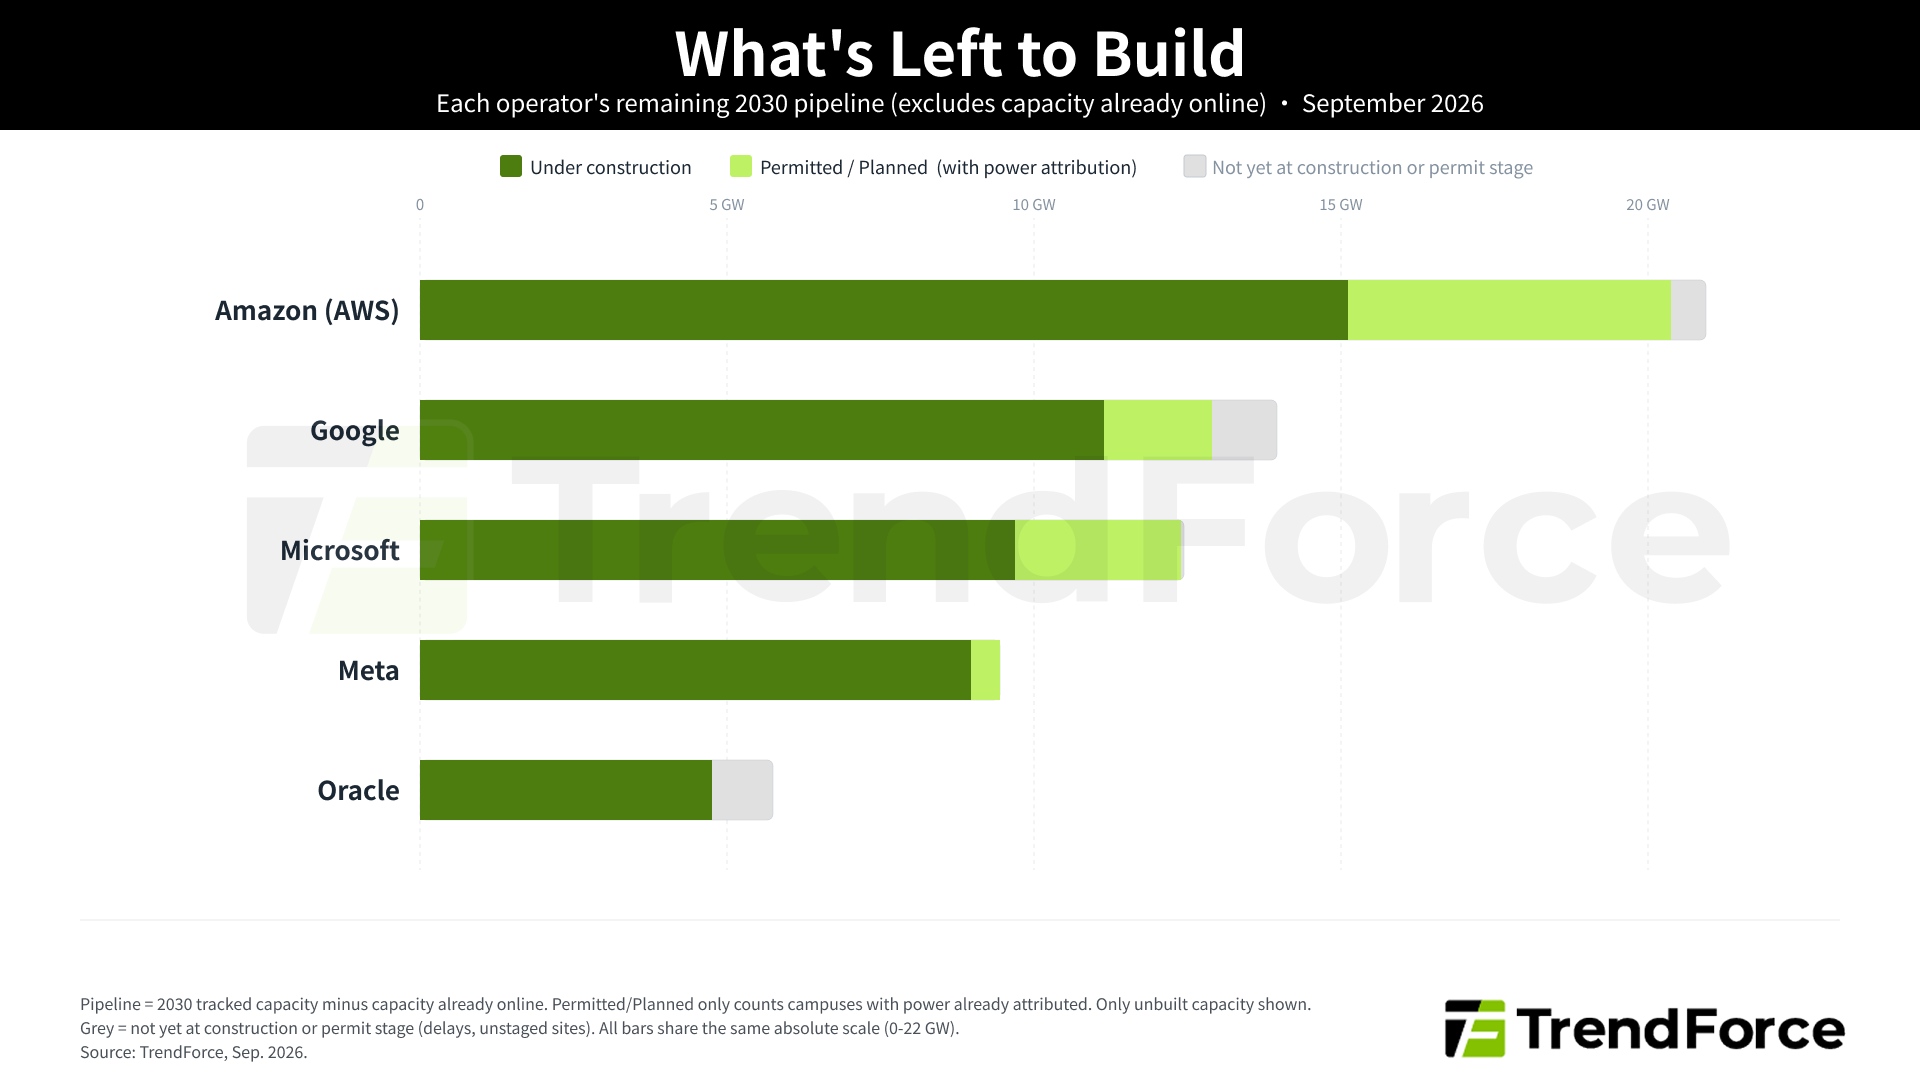
Texas-exposed miners and AI power the epicenter of the unwind giving back all gains from yesterday and more (HUT -23%; VST -14%; VRT -13%), while the hyperscalers ripped on the view that those with the most existing capacity just got a lot more valuable (AMZN/MSFT +6%, GOOGL +3%). Lots of debate among investors on the magnitude of the moves in the CSPs. The bulls made the argument that harder new builds make existing powered capacity scarcer, so prices go up and it widens the moat for whoever already owns energized compute, while firms that only promise future capacity fall behind. We showed this chart this morning, showing hypers have the most capacity already permitted and under construction:
Some framed it as a win-win: value of existing capacity goes up while FCF improves if capex flattens and memory prices drop. Yup, the rare tech bull case where building less, spending less, and growing less somehow adds up to being worth more. Hypers are also a lot more politically savvy than Neos at permitting and getting builds across the finish line so another leg up there in a tougher regulatory environment. Capacity can also move offshore as shown by GOOGL’s recently announced $15B DC in Malaysia over ‘27-28. All good points.
A few, fairly quiet pushbacks: Dems ran against Big Tech which isn’t good for Mega-Cap, 34 of 36 winning governors back ratepayer protections, which likely means hyperscalers pay grid costs, & lastly union-labor, water and tax-abatement conditions raise build costs. Also, some pointed to AAPLs +6% move as a reason this was all positioning/safe-haven driven.
Outside of Megacap, the AI-loser and consumer baskets squeezed (OTAs +5-10% on lower oil; DUOL +26% on a better print, etc). UBS said they said “zero real buying” in UBER and BKNG fwiw. Consumer agentic Winners vs. Losers basket -6% as a lot of the names beaten down on AI agent disruption risk unwound. There wasn’t one single internet stock red on my screen today; first time that’s happened in a while as investors shifted to a long unloved sector. Names like NFLX +5% and DASH +8% finally getting some love. TMT Mo -8%.
We dove into the potential impact of the Dem win in Texas in our morning wrap here. SemiAnalysis was out saying they 16.7GW of planned 2028 Texas capacity at risk. Gerstner said 10–15GW of the 43GW 2027 build may not come online. Jefferies estimated ~13.3GW of announced Texas projects are at risk under a Hinojosa moratorium, with Texas roughly a quarter of the US capacity expected online by 2030. Roughly 20% of '27 hyperscaler capex goes toward pre-build activity and is potentially at risk, with '28 build plans facing even greater uncertainty (UBS said 30% of 2028 capacity additions at risk).
MS said the Texas results aren’t in tech prices yet, and noted that in 2018, 2002, and 1974, all had drawdowns of 10% post midterms despite market being higher six months later: