

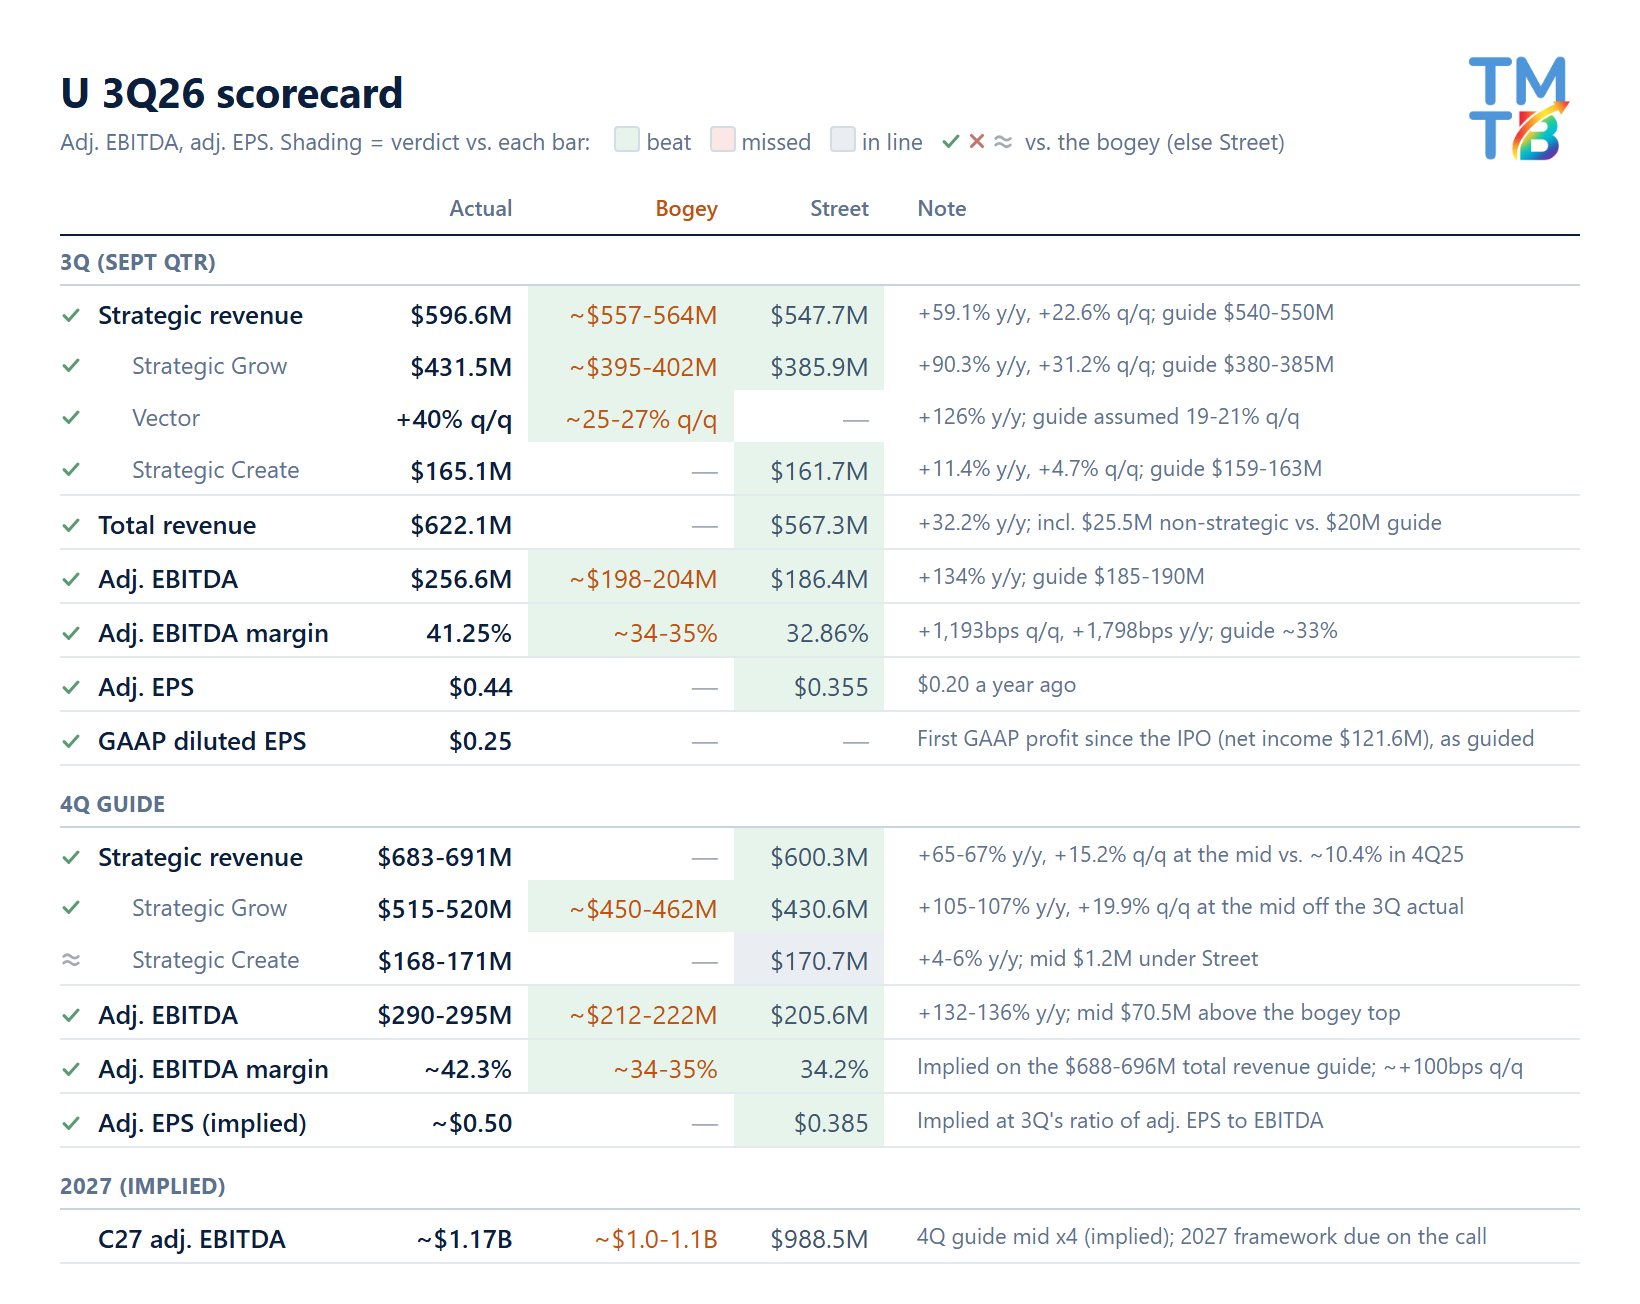
U +15% pre-market: Blowout, cleared every bogey by a wide margin despite this being a crowded HF long. Vector grew +40% q/q vs. the ~25-27% bogey and the 19-21% the guide assumed. 3Q Strategic Grow of $431.5M (+90% y/y) beat Street ($386M) and the ~$395-402M bogeys, and adj. EBITDA of $256.6M (41.25% margin) beat Street ($186M) and the ~$198-204M bogeys. The 4Q guide beat on every line but Create (in line): Strategic Grow of $515-520M (+20% q/q off the 3Q actual) vs. Street $431M and the ~$450-462M bogeys, and adj. EBITDA of $290-295M (~42.3% margin) vs. Street $206M (34%) and the ~$212-222M bogeys (34-35%). Also the first GAAP-profitable quarter since the IPO.
Implied Vector guide is 23-25% for 4Q above bogeys of high teens, and implies accel to ~145% from 125% y/y
4Q EBITDA guide annualized (mid x4, ~$1.17B) already tops Street’s C27 of $988.5M so bulls moving #s at (were at $1.3B+ already).
Overall, just a very solid q bulls will be happy with.
Details:
Vector grew +40% q/q (+126% y/y), vs. the ~25-27% q/q bogey and the 19-21% q/q in the 3Q guide (the CFO on the 2Q call: “Our guidance assumes 19%-21% sequential growth rates for Unity Vector”).
2Q grew +23% vs. a 12-13% guide, after four straight quarters of ~15%. So 3Q beat the guide’s assumption by ~20pt vs. ~10pt in 2Q.
Greater China revenue was $157.4M, +74% y/y and +37% q/q, 25% of revenue vs. 21% in 2Q and 19% a year ago. That’s ~57% of the +$75.6M q/q revenue add; US was -3% q/q.