

Good afternoon. QQQs +1.1% (up as much as +1.5%) on Anthropic S-1 day, with the AI-infra complex ripping back from last week's de-gross before fading into the close a bit. Semis +2.9% (off +3.9% highs) led helped by an optical and memory bid. Software +75bps helped higher by infra & cyber while Internet lagged all day as META -2% fell following their equity raise.
Ok let’s touch on Anthropic first. We won’t dive into details here, plenty of that going around X, TMTB Slack, and in your inbox already. A few links we liked:
A couple things that stood out to us:
48% revenue is generated through CSP marketplaces like AWS Bedrock, GOOGL’s Vertex, and MSFT’s Foundry.
Customer concentration improving: The top five customers fell from ~36% of revenue in Q1'26 to ~21% in Q3'26. Top-five revenue still roughly doubled, from ~$1.7B in Q1 to ~$3.5B in Q3, and each of the five hit a record in Q3.. Revenue from everyone else grew ~4.4x over the same two quarters, from ~$3.0B to ~$13.3B. Customers spending $100K+ a year went from >950 to >11,900 between September 2025 and September 2026.
Cash levels/FCF positive after SBC, and operating leverage better than expected
Total customer spend fell about 20% in the two weeks ended January 2, 2026, compared with the two weeks ended December 19, 2025. This is important bc means Dec ARR likely will be understated ~10%...something to keep in mind
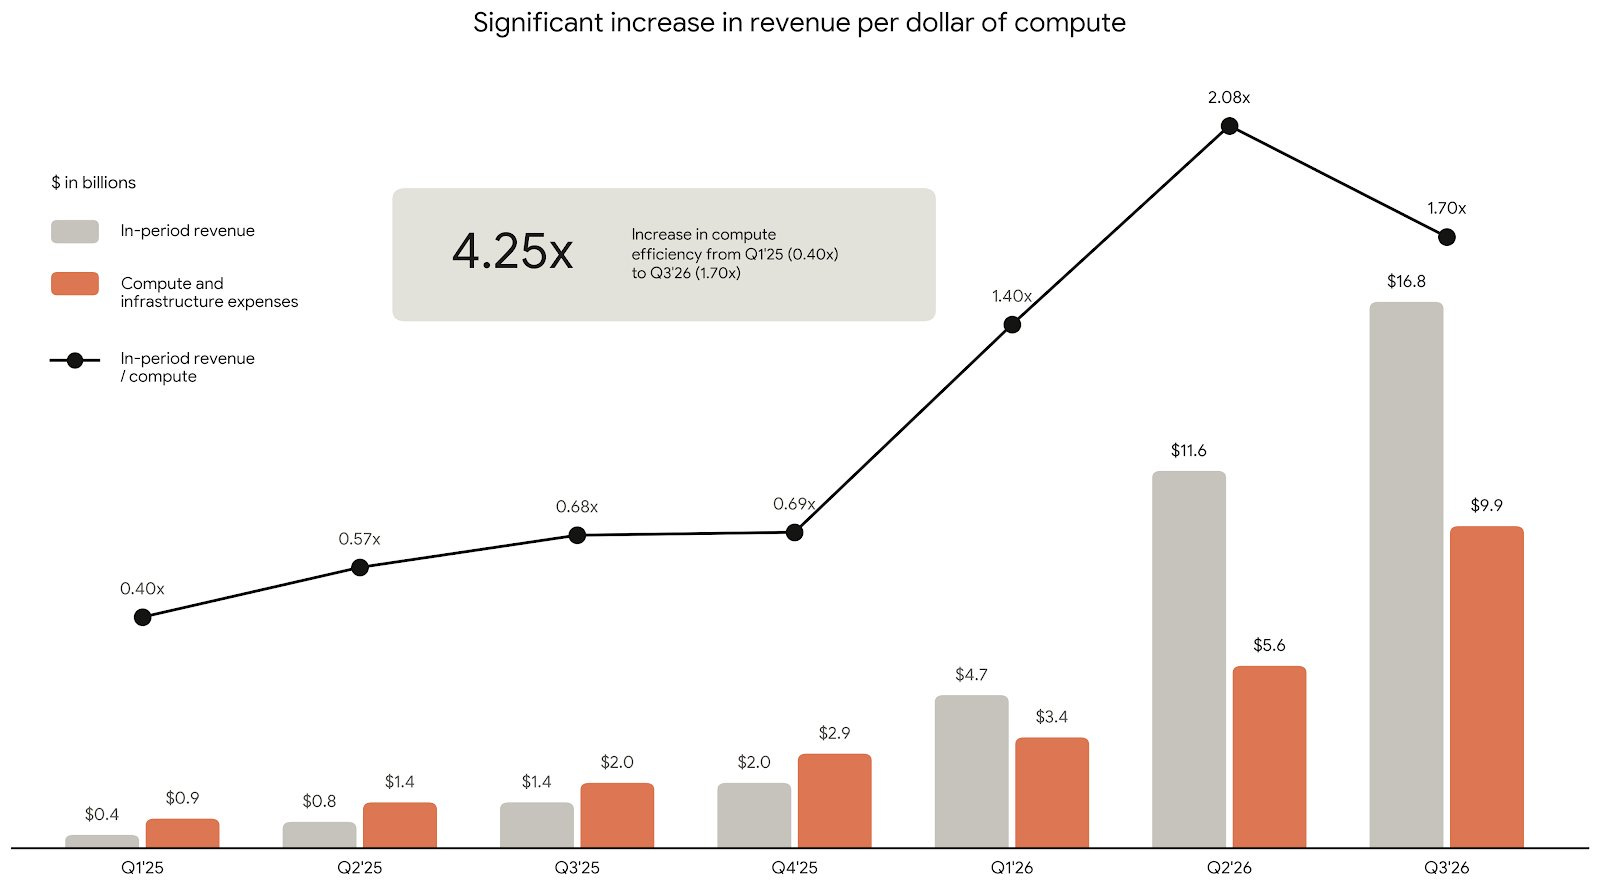
Overall, we think the release was largely positive as it reinforced Anthropic’s cash generation ability and assuaged some bear fears about Anthropic’s business model (despite a lot of it already being telegraphed in leaked reports).
Importantly, they left a spot open to fill in October ARR, which means we likely get it middle of next week when they filed updated S-1. We spent a good portion of our weekly yesterday detailing why Lab ARR matters so much for the AI trade and how it flows through to the financing and build out - it was one lesson we learned over the last month. So a lot of focus will be on that number.
Let’s dive in: