

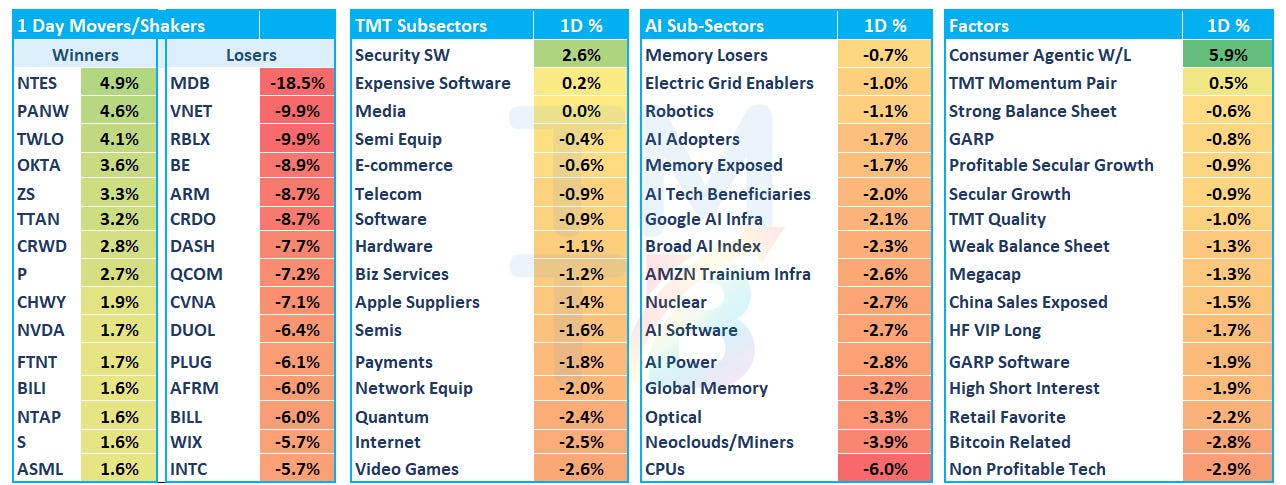
Good afternoon. QQQs -1.1% in a risk-off start to the week, with most of the damage done in the first hour (QQQs -1.7% at the lows around 10:45am) before an Iran headline mid-afternoon helped claw some back. Semis -1.7% led lower (-3.6% at the lows) as the CPU (AMD -3.5%/INTC -5.5%/ARM -8%) & META (-5%) Muse trade unwound hard as the Muse hype cycle reached the point where investors began to dig into the numbers rather than just narratives and rocket emojis. At some point in every hype cycle, even Tech investors decide to open Excel.
On CPUs, this Freda Duan X post was making the rounds, concluding the sandbox layer is much smaller than many expected: serving 100M Muse DAU takes ~1 GW in her base case, but only ~0.1 GW of that is the CPU/VM layer (sub-$1B of CPU content, or ~65K 192-core CPUs, plus ~$2B of DRAM). In other words: 100M DAU is under 1% of a year’s CPU supply. So, slightly less than the ‘buy every CPU on Earth’ the tape implied the last couple weeks (ah, simpler times!). Bull case pushback is bigger picture: a big TAM (and sentiment) expansion rather than units as standalone agentic racks are ~46% of a ~$200-220B+ 2030 server CPU TAM (vs. $30-40B a year today) at ~2x traditional ASPs.
Re: META, concerns over a potential OAI competing product coming out at Dev Day and also questions around how much consumer shopping habits will actually change hit the stock. Stock was also hovering around 15% to 25x FY27 $36 = $900 (the broad consensus on both multiple and EPS), so seems like a logical spot to digest the recent rally, especially given Muse is unlikely to monetize in any meaningful way until ‘28, either on a subscription, ad, or commission cut basis (although Instinct CEO threw out some interesting numbers today in the ILTB pod, saying 50% of Instinct’s transaction volume is travel and they are already doing $1B+ a year in total volume). We wrote about this whole turn in the CPU/Muse hype cycle in more depth in our weekly yesterday (paywall opened in case you’re interested).
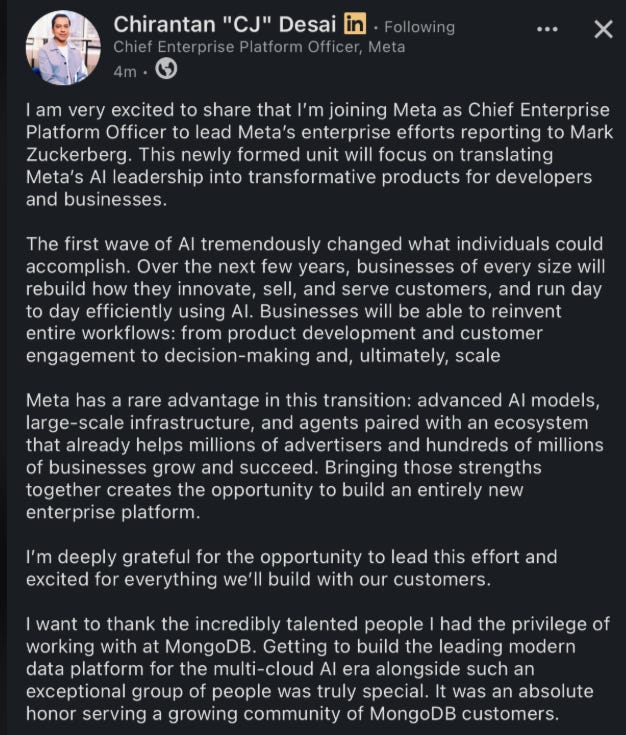
NVDA was the standout +1.7% in semis after announced $150B buyback on top of their existing authorization. Software -55bps held in far better than the headline of the day would suggest (META going after enterprise AI with MDB’s -18% CEO) as cyber ripped and offset the hit to app software (NOW -3%; CRM -3%; MSFT -1.3% TEAM/HUBS/MNDY -5%). CJ left effective immediately after less than 11 months, Dev Ittycheria is returning as interim CEO, and MDB reaffirmed guidance, the day before its investor day. As we said in TMTB Slack this morning, CJ is probably one of the most highly regarded enterprise execs in tech, and it’s hard to see what they can say tomorrow to reassure. Investors were looking for a 3-5pt raise to the long-term Atlas growth target (now >20%) going into the event; that’s a tough ask for an interim CEO. FUNDA called it “a major blow” given CJ was driving the GTM revamp that “was just starting to bear fruit.” Not everyone thinks he’s worth that much: Ummera: “I think CJ’s impact on MDB has been overrated. Hopping to prestige positions like a pod PM” while the news also brought the bears back out, arguing the departure confirms MDB isn’t a real AI beneficiary; Postgres is. Here’s his departure note on LinkedIn:
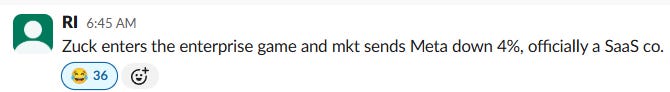
Favorite take of the day in TMTB Slack:
Just another quiet Monday in Tech.
Back to the tape. Macro didn’t help things. The long end sold off again, 10Y +7bps to ~5.25% (still the highest since 2007) with the 2Y +7bps to ~4.93%, and Fed Governor Cook added fuel: she expects “continued pressure on inflation from the AI buildout… and from the pass-through of higher oil prices,” and the “labor market appears to be well positioned to handle an increase in rates.” The market has ~70% odds of a 25bp hike on 10/28, ~40-50bps of hikes for the rest of the year and ~100bps cumulative through Dec ‘27. Oil round-tripped finishing flat: up as much as ~4.5% after Trump rejected Iran’s proposal to reopen Hormuz, then faded as Saudi restored East-West pipeline flows and Axios reported ~2:20pm that Trump is open to sanctions relief for concrete nuclear steps. BTC -2% to ~$83K.
Ok, let’s get to the good stuff…
AI/SEMIS
Big Day tomorrow for OAI: