

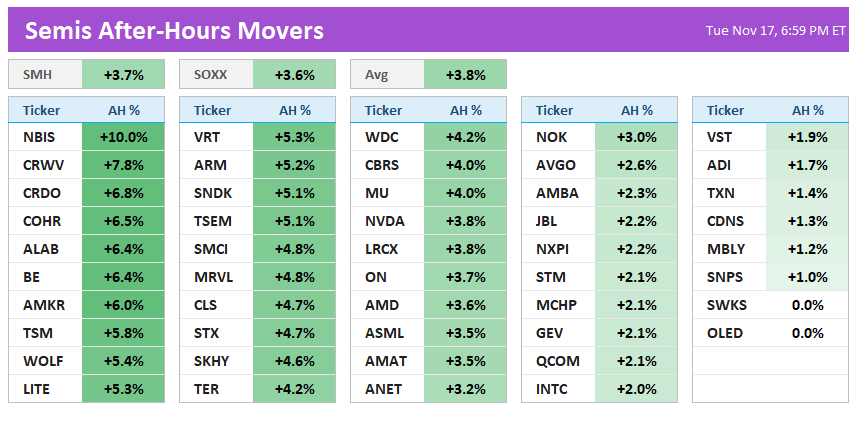
Raise your hands who expected Colette to save the AI semis trade? Who needs Jensen…
Semis +4-5% rallying hard close after Interim CEO Colette Kress raised FY28 growth to “approximately 75%” from 70% instead of cutting or pulling it. On FY27’s ~$423.7B (F1Q-F3Q plus the $130B Jan-qtr mid), that’s ~$741B vs. ~$712-717B implied by the bogeys. The quarter itself was above bogeys & the biggest beat vs guide since 3Q’25, DC Beat was the biggest since 1Q’25, and Jan guide was also above bogeys. Vera Rubin did nearly $20B in its first quarter; licensed Hopper sales to China ($2.4B in F3Q) have stopped and not included in the Jan guide. She’s still studying this week’s export rule and skipped whether demand still points to the ~100% growth customers forecast in August. On customer financing, the worry without Jensen, she’s “rigorously evaluating future investments, commitments, and guarantees” as other capital comes in, but overall she sounded good on those continuing (see quotes below).
The FY28 guide implies close to $17 of EPS at 72-73% FY28 GM, which is better than street at $16 but a tad light of where buyside is at $18. Still, it’s a relief. Overall, much better than feared and largely de-risks FY28. Overall, investors pretty happy with the print and happy the focus is off Jensen at least for tonight…
Investors are preferring to buy other semis (Neos leading the way higher) instead of NVDA and the group is rallying in the post after testing post-election lows today and it looks like SMH is taking the same shape it did before the SPCX IPO bottoming two days before pricing.
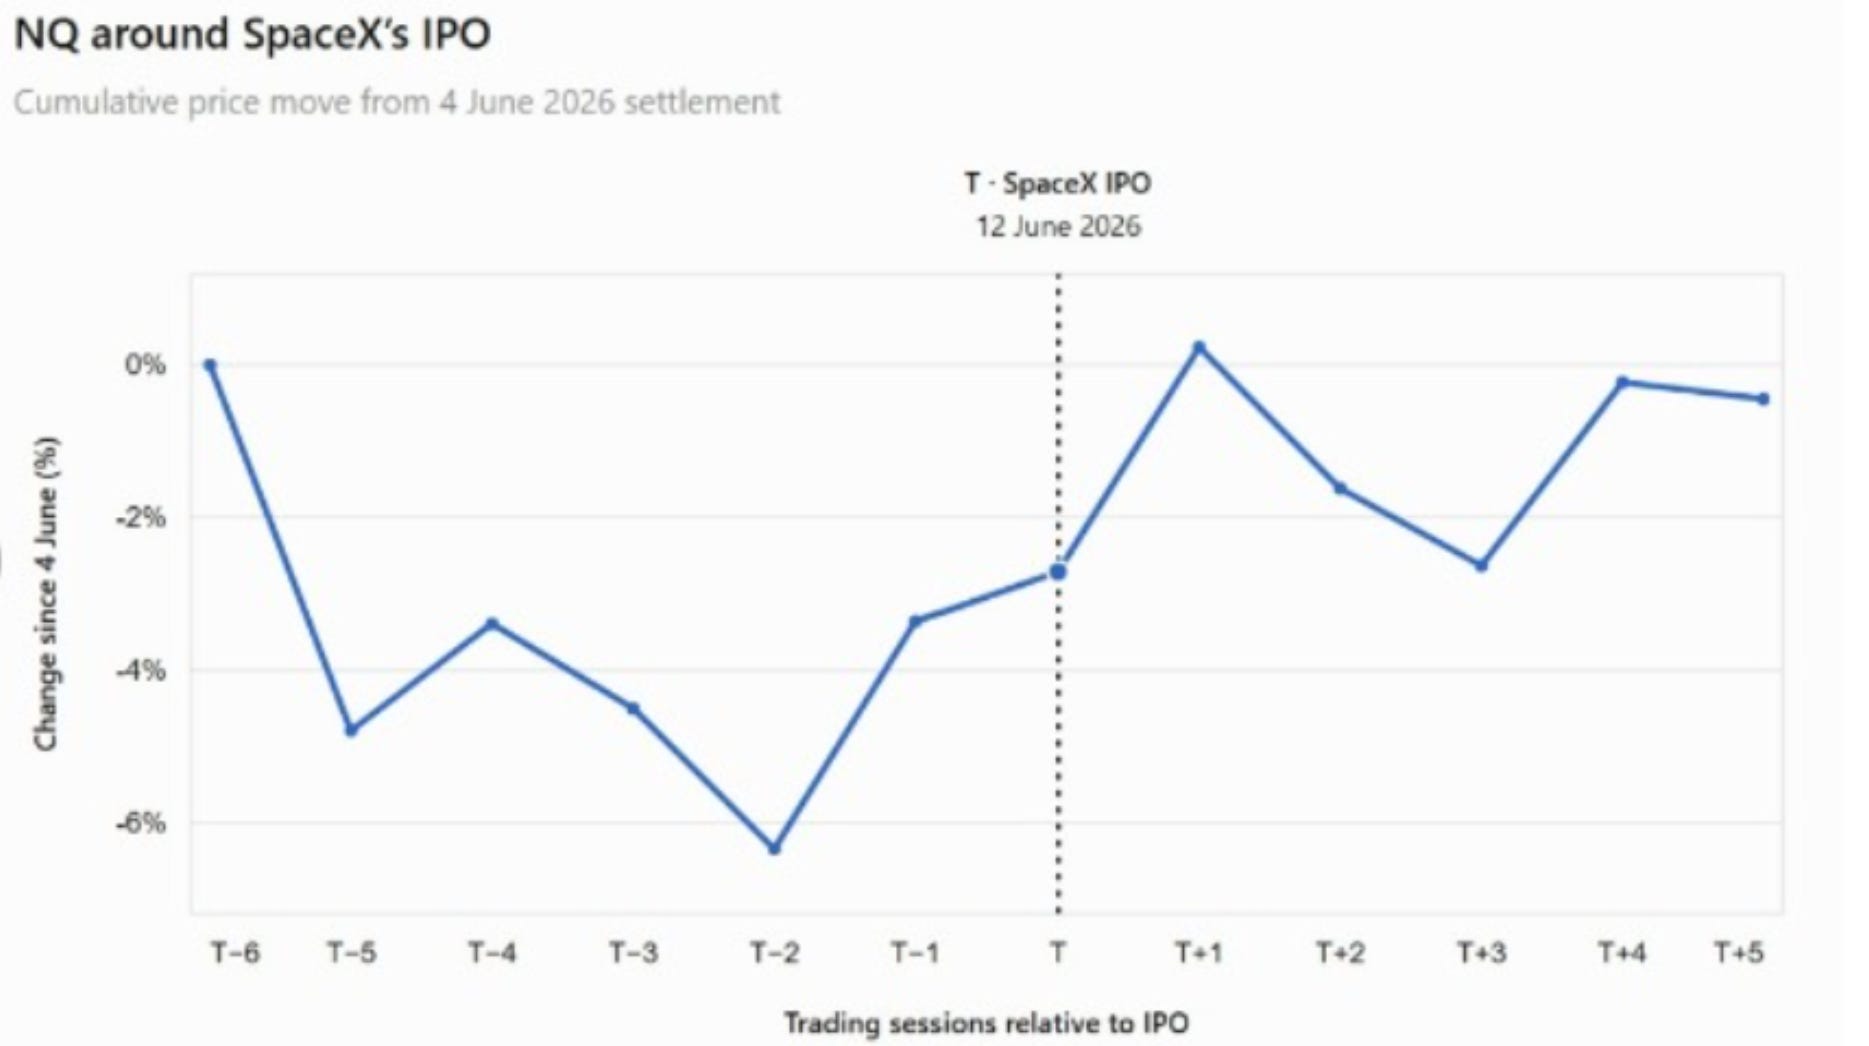
Can semis rally more than 2-3 minutes days?
We are currently staying away from long-term calls on semis here at TMTB. Your guess is as good as mine but the set up at least through the end of the week looks solid enough:
The Anthropic IPO vibes are surprising to the upside — WSJ says it now expects above $80 vs initial $70-78 range as seems like the narrative is threading the needle at the right time: post-Jensen, the sentiment around open-source gap shifting in their favor (along with distillation stopping and a weakish Qwen model release), better ARR in Oct from Opus 5.5, & potential cyber security tailwinds given recent news over the past week. The mixed reviews from OAI’s Astra 6.2 release today are helping and now post-NVDA the semi vibes seem to have bottomed (at least for the week).
Key Quotes from the call
On Neos:
“We have supported the development of this ecosystem, and we will continue to be disciplined and selective in our support”…“Their capital, it needs to be set up, ready to go for us to work in terms of that allocation.” Buyers below investment grade need “solid offtake.”
Tthe market matures and additional sources of capital become available, we are rigorously evaluating future investments, commitments, and guarantees.” Also: “we will remain thoughtful in how we participate and disciplined in how we commit capital.”
customer guarantees go only to “very strong customers,” where “there will be a portion that we will do.”
on the new contingency paragraph: “Is it new? No. Did we change anything? No.” If a partner can’t build, “our guarantee doesn’t exist anymore.”
On GPU Pricing:
Hopper GPUs have recontracted at up to twice their original price under the multi-year agreements, while the B300 rates have risen more than 60% since their introduction.” Compute “remains fully utilized across every hyperscaler and neocloud we serve.”
Earlier:
NVDA +2.6%: Clean beat and a Jan-qtr guide at the top of the buyside bogey, but GM a bit light. All in-all looks really solid with biggest beat over midpoint of the guide since 3Q’25. Bigger issues at play here obviously and key will be the call and reiteration of ‘27 guide of 70%
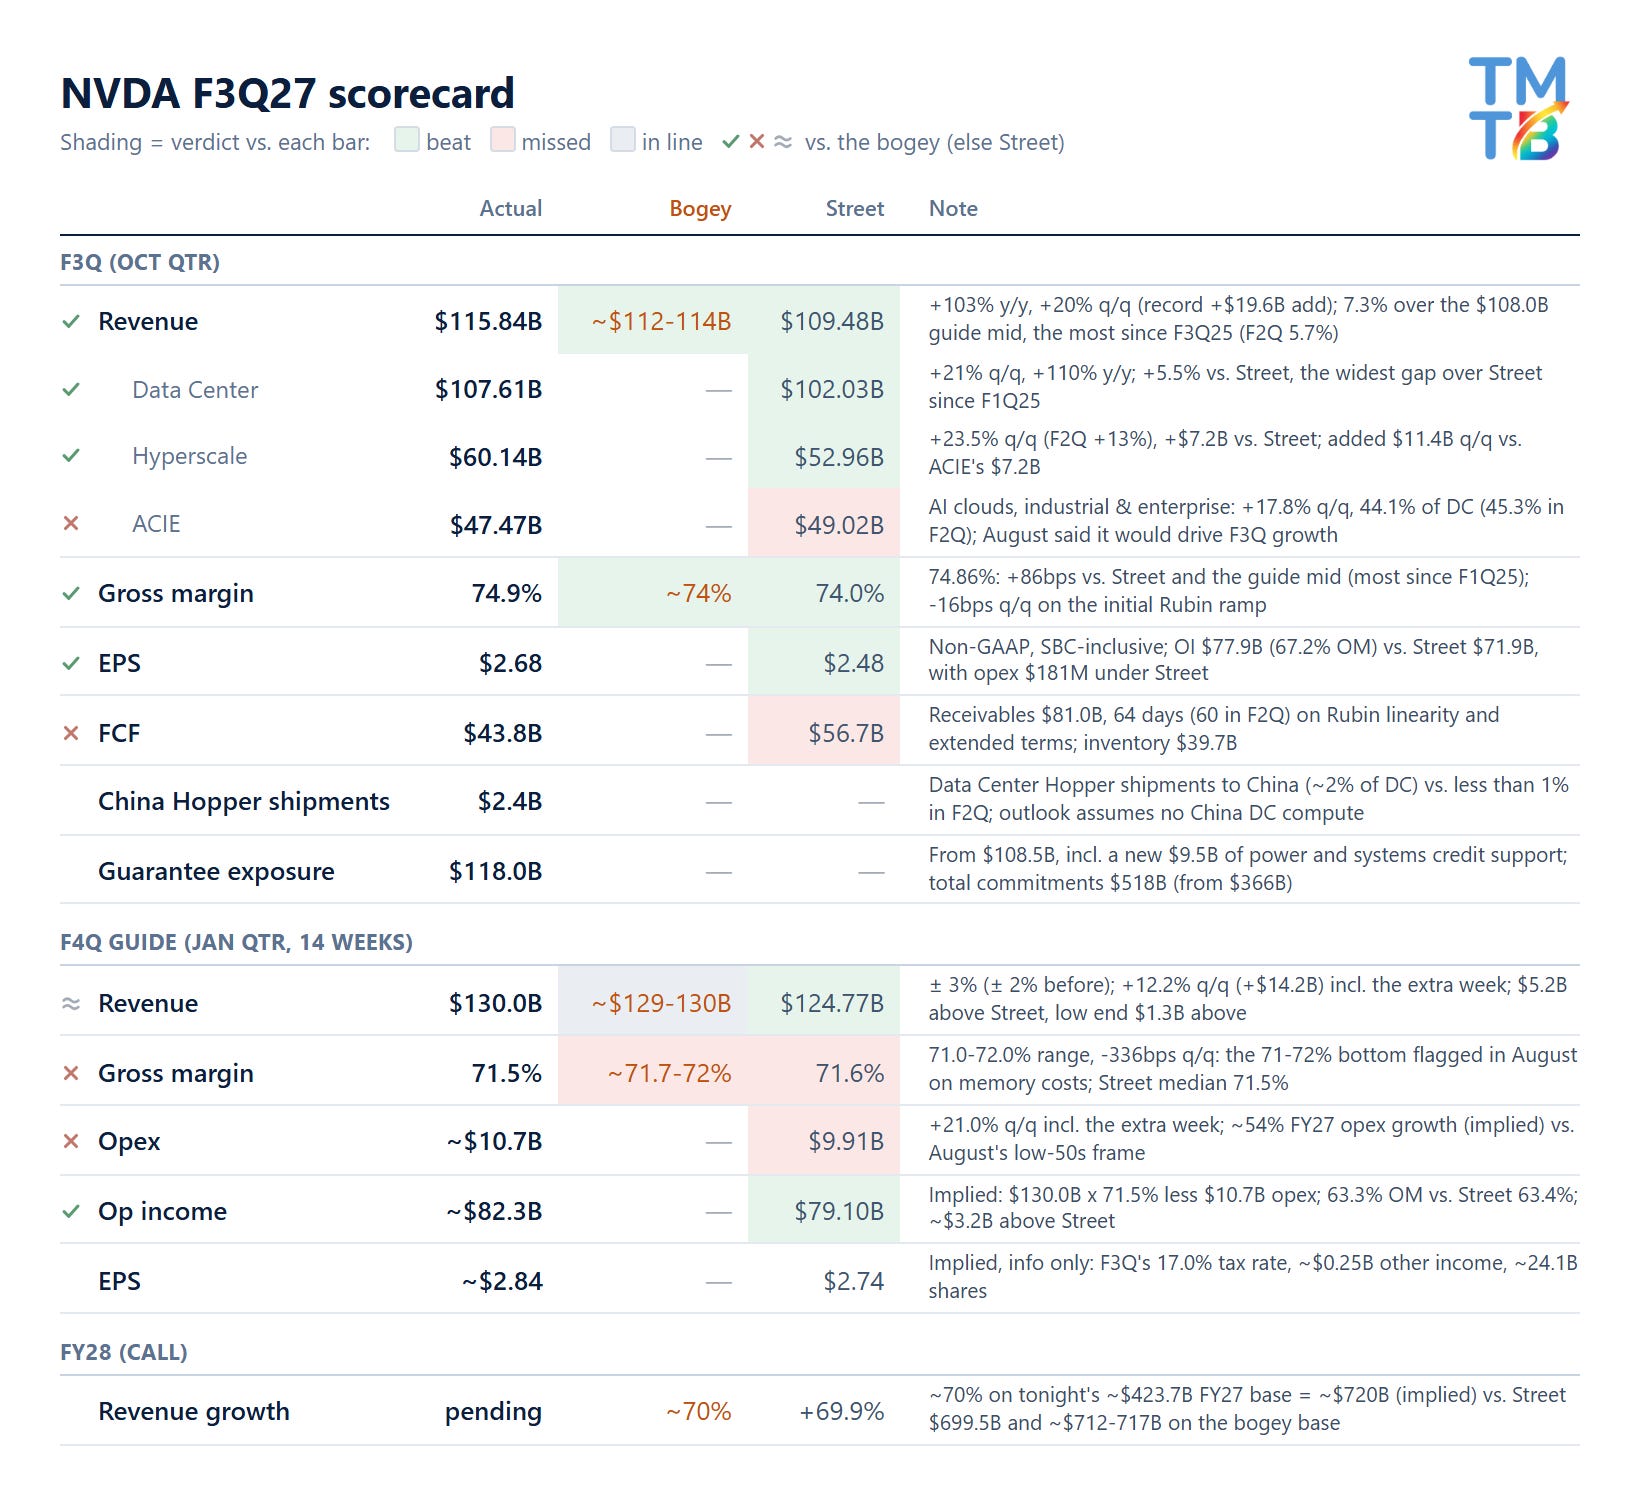
F3Q revenue of $115.8B (+103% y/y) beat Street ($109.48B) and the ~$112-114B bogeys, a 7.3% beat on the $108.0B guide mid vs. 5.7% in F2Q (the biggest since F3Q25) and a record $19.6B q/q add.
Data Center of $107.6B beat Street ($102.03B) on Hyperscale ($60.1B vs. Street $52.96B), while ACIE (AI clouds, industrial and enterprise) missed ($47.5B vs. $49.02B).
GM of 74.9% beat Street (74.0%) and the ~74% bogey, and EPS of $2.68 beat Street ($2.48).
The Jan-qtr revenue guide (a 14-week quarter) of $130.0B ± 3% (widened from ± 2%) beat Street ($124.77B) and was in line with the top of the ~$129-130B bogeys. GM of 71.0-72.0% (71.5% mid) missed Street’s 71.6% mean (in line with the 71.5% median) and the ~71.7-72% bogeys; with $10.7B of opex (Street $9.91B) that’s implied OI of ~$82.3B, above Street’s $79.10B.
The CFO Commentary: “We plan to file our 10-Q in the coming weeks.”
“We have partnered with leading neoclouds to enable broader access to our AI infrastructure to serve AI startups, model builders, enterprises, research organizations and sovereign customers. Our commitments take effect only if the neoclouds secure financing to purchase the data center infrastructure products and the related compute capacity is deployed, made operational, and accepted by us. The maximum commitment presented assumes these contingencies are satisfactorily resolved. If they are not timely resolved, the amount and timing of our commitments may be affected, and certain commitments could be reduced or eliminated. Under these agreements, we will earn revenue on the upfront sale of our infrastructure and if certain criteria are met, we will participate in revenue share generated by the neoclouds from their third-party customers.”