

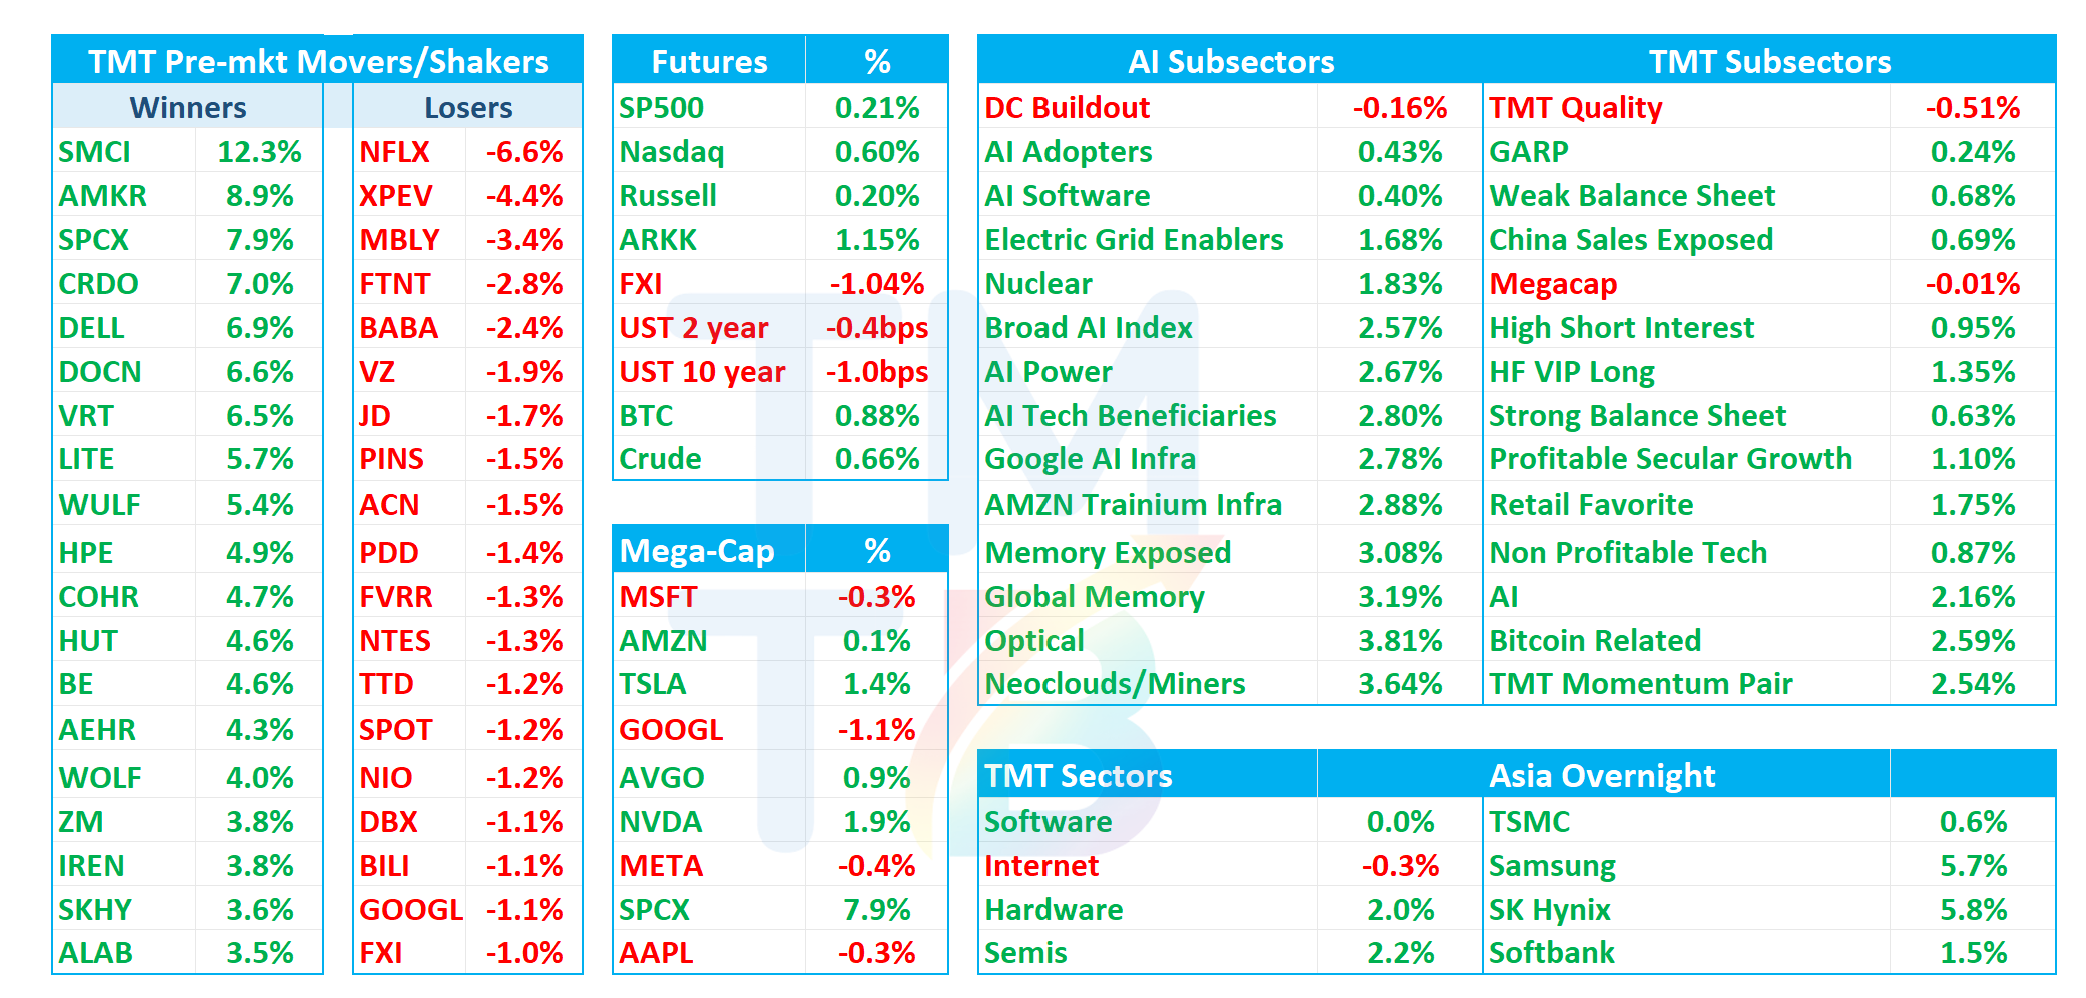
Good morning. QQQs +60bps / SPX+25bps as better SPCX +8% earnings and commentary from musk, as well as better numbers from SMCI, has semis +2% early. Internet flattish after NFLX -6% missed even low expectations. SMCI numbers have DELL/HPE +5%, DOCN +6% on a Piper upgrade, and Optical +6% (CRDO +7% / LITE +6%) leading the way higher in semis. GOOGL -1% on weaker 3p ad checks.
Asia mixed overnight although Korea was in the green: TPX +0.86%, NKY +0.85%, Hang Seng -0.9%, HSCEI -1.08%, SHCOMP -0.6%, Shenzhen -0.49%, Taiwan TAIEX +1.28%, Korea KOSPI +3.29%. Memory strong with Samsung/Hynix +5-6%
Another busy day with META, LRCX, TSLA, TXN and IBM prints on the docket this afternoon.
We’ll start with earnings, the onto the usual. Let’s get to it…
EARNINGS
SPCX +8%: Better than expects as AI compute drives a broad beat; Q1 guide ~50% above Street, with funding needs rising
SPCX beat Q3 revenue by 14% and adjusted EBITDA by 30%, raised its compute deployment targets and guided Q1 well above Street, while the accelerating build pushed Q4 CapEx to $35–40B vs street at 21B
Revenue grew 161% y/y to $14.58B (last q +92%) vs. Street $12.84B, with adjusted EBITDA of $8.81B vs. $6.80B and margins of 60.4% vs. 53.0%. Super Intelligence drove most of the upside as compute pricing moved above the previous $30–50/W range, supporting sub-one-year deployment paybacks. Q1 revenue guidance of $33–37B vs Street ~$23B, while mgmt now expects approximately 13GW of compute exiting 2027.
Some good quotes from Elon on the call…
Compute Build-Out Guide
“We are tracking to be able to bring roughly 200,000 GB300s online per month for every month for the remainder of this year, continuing that pace next year. With next year being primarily Rubin, very Rubin compute, at this point, I would say I am fairly confident of being able to bring an incremental 10 gigawatts of compute online in 2027. That would be in addition to the roughly 3 gigawatts, maybe 2.5 to 3 gigawatts that we will have online by the end of this year. Let me put it this way. I would be surprised if we brought on less than 13 gigawatts of compute by the end of next year. … To make sure that that is not a constraint for our build-out, we are actually going to aim for an incremental 20 gigawatts of power cooling infrastructure next year.”
Compute Pricing And Payback
“At current pricing, new compute deployments are generating a payback of less than a year. Pricing is currently tracking slightly above the high end of the $30 to $50 per watt range we were discussing just last quarter, which further supports the attractiveness of these terrestrial SI compute investments. … If you look at, say, how are our short-term contracts renewing? Are they renewing at higher dollars per watt or lower? We see them renewing at higher dollars per watt, not lower dollars per watt. … It is not impossible that we will have a six-month payback period for compute next year.”
3. Terrafab Timeline
“It is what we are aiming for internally, to make our first sort of test chip functional in approximately May or June of next year. That is just a kind of an SRAM chip or something that basically tests the line. That is at the research fab in Austin. Our aspiration is to reach volume production around Q3 of 2028 at Terrafab, at Gibbons Creek, the main Terrafab location. These are very aggressive dates. We are very appreciative of ASML and all of our other suppliers in accelerating equipment deliveries in order to achieve this outcome.”
Musk said Tesla and SpaceX have formed committees to examine a potential combination.
Feedback was largely positive with bulls happy with pricing power, execution, and near-term numbers although plenty of pushback on the 13GW # by end of next year as no one thinks that is a reasonable estimate (which is par for the course for Elon).
Some good bull and bear takes from the earnings thread last night in Slack:
Bulls:
“If you look at SpaceX’s results, compute pricing appears to be holding up very well. Why isn’t that bullish? Compute capacity in its Superintelligence business grew by less than 30% quarter over quarter, from 1.4 GW to 1.7 GW, yet revenue increased by a full 200%.”
“Given the surging prices SpaceX is paying for Nvidia GPUs, I think it’s a bit of a stretch to expect SpaceX to dump its prices later on.”
“plug in 7GW. numbers still look great!”
“Market is already heavily discounting his claims though.. I don’t think we’re pricing anywhere near 13GW fully up and running at spot rates by end of next year”
“Has scaled colossus faster than anyone else. He’s smart to not tell you who the customers are vs Oracle tied to one customer.”
“Cowen DC call today said that SPCX is focusing their compute build in SE Asia where there is plenty of power, build costs are 50% of USA, and sites can be built in 6-9 months”
“The guy has $3.5T in market cap and a 20 year track record of making money appear on command...”
“SPCX as natural consolidator of neos given his cost of capital relative to peers”
“arguably spcx has 1) the optionality of starship at $200 per kg unlocking many use cases, 2) starlink getting tens and possibly hundreds of billions of dollars of recurring revs and 3) if ai goes south, xai can gain share with probably the cheapest token cost out there”
“i dunno about 500b-1T, that’s for later. you can’t prove that is wrong right now … next few months look FIRE”
Bears
“Even discounting for the school of Elonism, these numbers are wild. The 13GW. The $500b-$1trn. All of it.”
“Does anyone take this $500b arr guide seriously? iphone sales + entire services biz is $300b (approx). we adding that much rev in 1 year lmao?”
“Elon says he will guarantee 10 GW, claims he could do 20 GW, will monetize them all >$50/w, end ‘27 at $1 trn ARR. Prob ends up doing <5 GW and $30/W blended.”
“1. Probably wont be built, 2. If it is, that wont be the revenue. If 1 does happen, could be ugly because of 2.”
“Assembling 300 MW with trucks parked outside pumping NG in is an amazing feat. Doing it at 30x the scale is crazy talk. That call yesterday was Alice in Wonderland. … delivering 5-7 GW would be an amazing feat, forget 13GW (!)”
“now he needs to find $300 to $500bn of capital to execute - putting aside the operational hurdles”
“WHO IS THE CUSTOMER MAN? How can we not care about the answer to this question....”
“there is no way they can use 13GW if there’s not an external buyer … As for Grok, they can’t even use their compute as is now lol, they are renting it out.”
“Elon is attempting to build all this compute to rent it at SPOT rates, presumably without any lock-in at all. If prices fall sharply, he’s left holding the bag. … we have Oracle trying to make 13B/GW/year, whereas we have Mr. Elon claiming he can make 50B/GW/year.”
“Liquidity for locked up shares…1.3bn shares eligible for sale off lockup T+2 for Thursday October 22nd”
Some good discussion on Slack here whether this is good or bad for Neoclouds: