

Anthropic IPO day is finally here and it’s a happy one for tech investors as QQQs +2% with strength across the board.
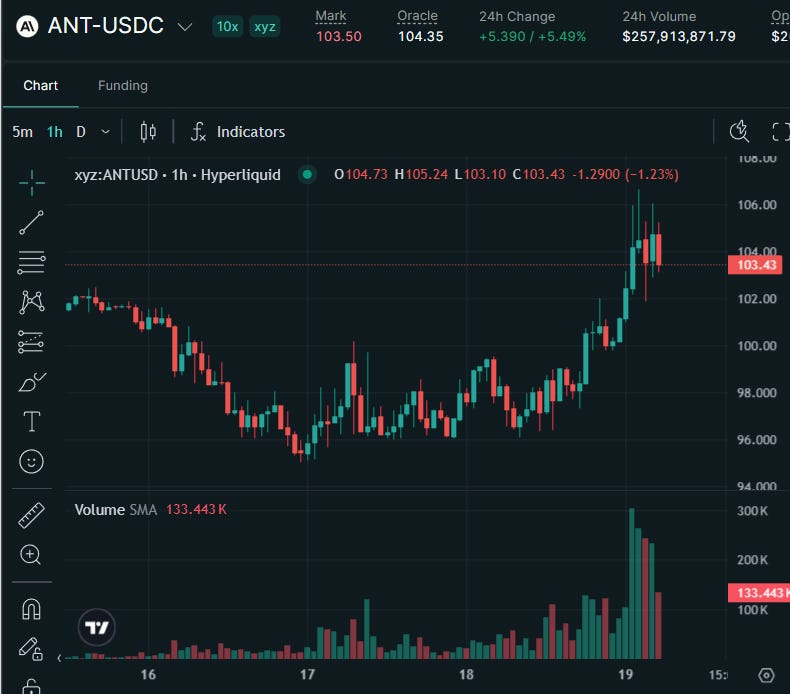
ANT priced at $83 (up from initial range of $70-78), raising $81B+ (with another $26B on top with PP).
Hyperliquid has ANT opening at $103-$104.
SPCX got going just before Noon ET so expect the opening auction around then.
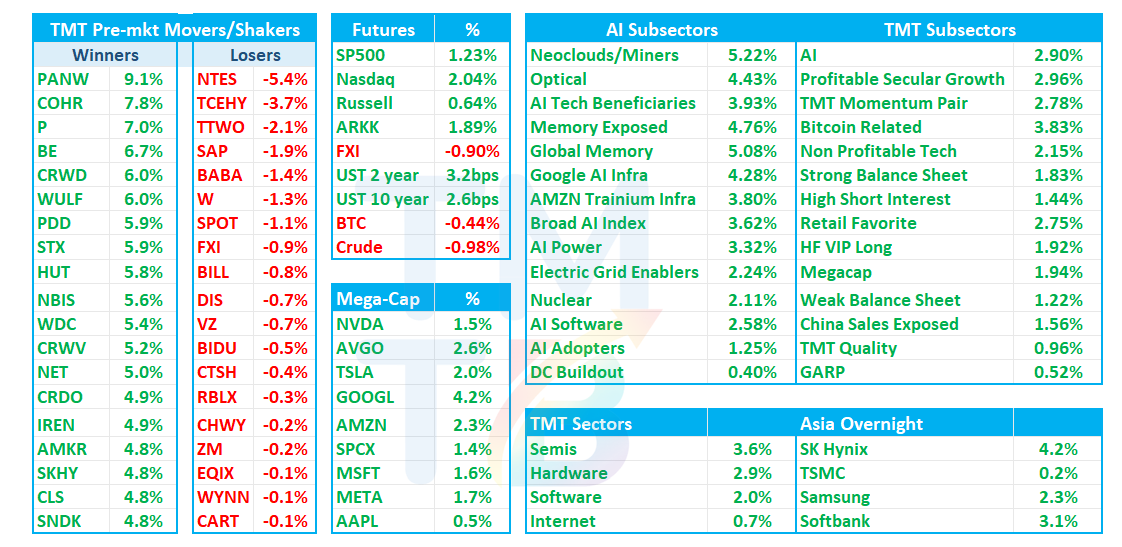
In Tech, Semis +3.5% and Software +2%. PANW +9% after a massive beat and raise emboldening cyber bulls (NET/CRWD +5% in sympathy); MDB +4% on a UBS upgrade; TTWO -2% giving back some of yesterday’s gains post-GTA launch despite positive reviews and solid 3p #s; Memory and Neos leading the way higher in semi land +6%. Hypers also strong with GOOGL +4% (new model Neon getting good reviews on X) and AMZN +2%
Asia mixed overnight: Korea KOSPI +1.39%; TPX -0.04%, NKY +0.71%, Hang Seng -1.95%, HSCEI -1.86%, SHCOMP -0.28%, Shenzhen -1.47%, Taiwan TAIEX -4.4%.
Lots to get to, so let’s get to it. We’ll hit PANW and P EPS Recaps first then the usual…
PANW +10%: NNARR Blowout and a Raise ~2x the Beat Outweigh Applied Compute’s FCF Reset
Despite elevated positioning/sentiment going in, just a great quarter overall which should embolden cyber bulls after all the hacking headlines we’ve seen in the press. Main debate centers around the AC acquisition and what that means for margin/fcf profile and what it means vis-a-vis competition vs. the labs.
First the numbers: NNARR of $630M crushed the Street (~$450M) and buyside bogeys (~$520-600M), revenue posted its biggest beat since F4Q21, and all three segments accelerated. I have Organic NGS ARR growth ticking up to ~30%+. FY27 NGS ARR was raised $375M to $11.475-11.525B, which beat Street ($11.11B) and the ~$11.24B bogey: a raise 2.1x the $180M F1Q beat on the guide mid (the bogey assumed ~0.8x). We covered the full #s here last night.
Mgmt tied demand to an AI-driven vulnerability wave (critical/high CVEs at ~7x last year’s monthly pace) that is speeding up consolidation, firewall buying and virtual patching.
The main debate coming out is the Applied Compute acquisition impact to margins/FCF: $4.5B in stock for ~$100M of annualized revenue, targeting $1B of NGS ARR by FY29. Asked what led to it, the CEO said PANW must “get in the training business” to supervise AI: “That’s our bet.” Mgmt confirmed in callbacks it was excluded from the guide, and the deal takes up to 100bps off FY27 op margin and 200bps off FY28’s, back to 29-30% in FY29. That’s as low as ~27.5% in FY28 vs. Street’s 30.5%, up to ~$0.5B less OI. The FY28 FCF target drops to 38%+ from 40%+, now before data-center capex (<$3B through FY30): ~$0.4B under Street. Entering the training/inference biz comes with higher capex/lower margins, we know that and we’ve seen investors react differently and different points in time to shifts like this so it will be interesting to see how investor feedback evolves as time goes on. But so far, #s and Cyber tailwinds outweighing any debate.
Despite the margin/fcf hit, most investors I spoke to liked the strategic rationale for it although heard some debate around this potentially being a defensive move. Here’s a good take from TMTB Slack: