
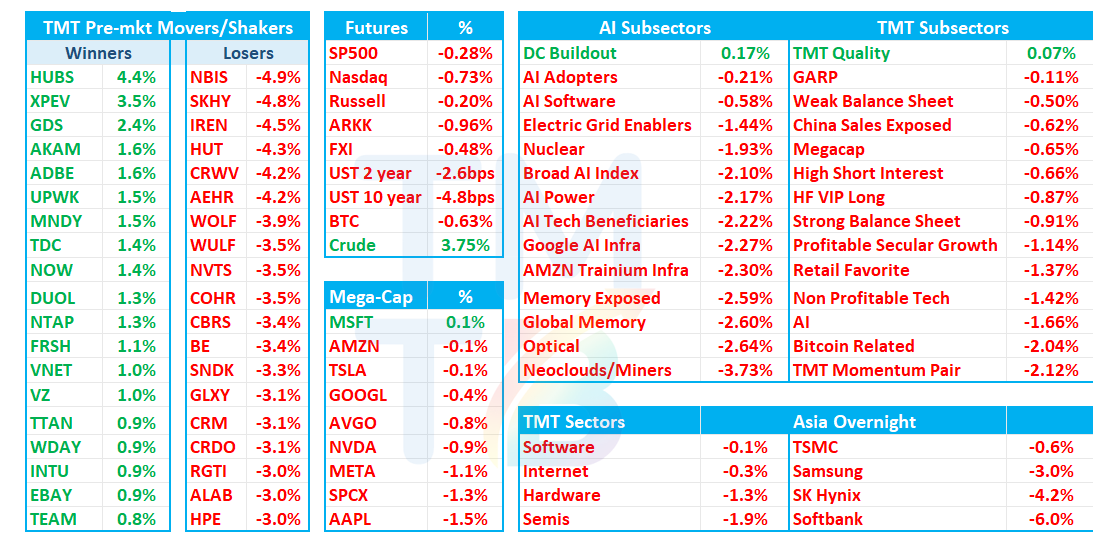
Good morning. QQQs -70bps / SPX -30bps lower to start the day. Oil +3% and yields down 3-5bps across the curve.
In Tech, Semis -2% following the weakness in Korea (-4%) overnight as DC IPO Elice fell 30% on its first trading day in Korea, which isn’t helping things. Neoclouds (NBIS -5%; CRWV -4%; Miners -4%) leading the way lower with memory -3-4% right behind. Software/Internet flattish with CRM -3% after announcing a $5.6B cash deal for BRZE (closest comps KVYO +10% and ZETA +2%). App sw stronger: HUBS +4%; NOW +1%; WDAY +1%
As mentioned above, Asia stocks mostly red led lower by Korea: TPX -1.43%, NKY -1.3%, Hang Seng -1.32%, HSCEI -1.21%, SHCOMP +0.12%, Shenzhen +0.34%, Taiwan TAIEX -1.13%, Korea KOSPI -3.73%. Memory names weaker with Samsung -3% and Hynix -4%. Softbank -6%.
We get SPCX and NFLX earnings today & NET Cloudflare Connect.
Lots to get to, so lets get to it…
AAPL: Loop downgrades to Hold as iPhone cuts increasingly look demand-driven, not just supply
Loop cuts AAPL to Hold from Buy and PT to $330 from $370, lowering estimates after concluding the ~10% Sep/Dec iPhone shipment reductions are unlikely to be fully recovered in 2027 as previously expected. The firm now sees the issue as increasingly demand-related rather than purely supply-driven, while rising memory costs add gross-margin risk. After the stock’s recent appreciation, Loop says AAPL needs a new fundamental catalyst to re-rate.
AKAM: Raymond James upgrades to Strong Buy/$170, says Anthropic financing fears are overdone
RJ upgrades AKAM from OP to Strong Buy after the pullback, arguing the market is over-penalizing its ~$5.5B capital commitment supporting >$11B of expected Anthropic revenue. AKAM represents <3% of Anthropic’s estimated ~$520B of infrastructure obligations over the next 7–10 years, making it a relatively small but differentiated piece of the buildout given Akamai’s networking footprint. While higher rates and Anthropic funding remain risks, RJ sees favorable risk/reward as AI sentiment recovers and contracted inference revenue ramps; PT $170.
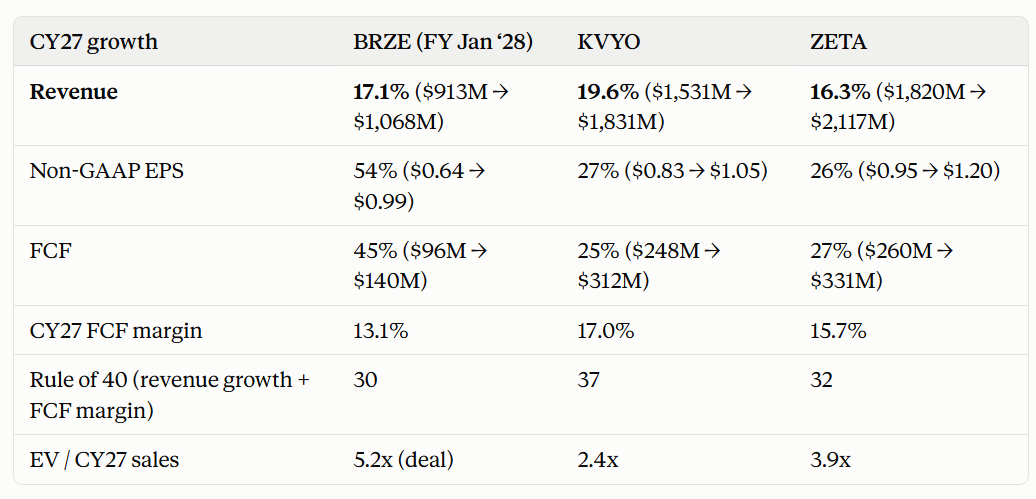
CRM: To buy BRZE for $47.50 in cash / $5.6 EV (58% premium; ~5x CY27 sales)
Some comps: