

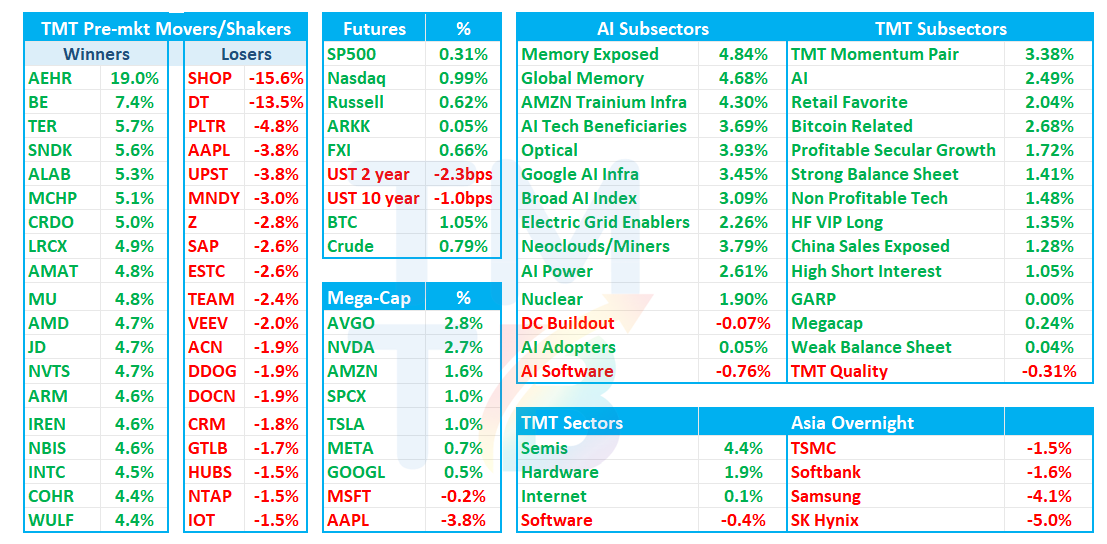
Good morning. QQQ +80bps / SPY +30bps as stocks bouncing in the last few minutes as news crosses wires that Washington has approved the draft memorandum of understanding that the Qatari delegation presented to Iran yesterday.. Taco Tuesday strikes again. All eyes on midterms tonight with Dems predicted to take House and Senate:
In Tech, AAPL -4% on weaker GM guide/commentary and lower services guide. PLTR -7% as the call talked up short-duration sovereign AI delas which lowered bookings growth despite 13th straight q of acceleration. ON +4% on better top line #s. DT -13% on a 2Q ARR Deel and SHOP -15% on a messy print with lower GMV, better rev guide, but worse opex guide. We sent out first takes on both here.
Tonight, we get ALAB, BKNG, ANET, and AMD among others.
Semis +3% outperforming early as Internet -30bps and Software -1% lag. BE +6% on a Barclays upgrade. ORCL +1% has turned green after their $10B/$10B Equity deal and Memory +3-4%. NVDA/AVGO +2-3%
We’ll hit the usual first then PLTR and AAPL.
TECH RESEARCH/EARNINGS
NET: JPM upgrades to OW/$350 after ~20% pullback as growth reacceleration + FCF leverage improve setup
JPM upgrades NET from Neutral after the ~20% pullback, seeing an attractive entry as revenue growth can reaccelerate toward 35%+ with improving FCF margins. Drivers include GTM improvements under Mark Anderson, DNR recovering from ~110% to ~120%, stronger $1M+ enterprise penetration, and developers rising from 4.5M to 7.4M as Workers/agentic AI adoption broadens. JPM says Acts I-III alone support the acceleration, with Act IV/agent traffic providing additional upside. PT $350 unchanged.