
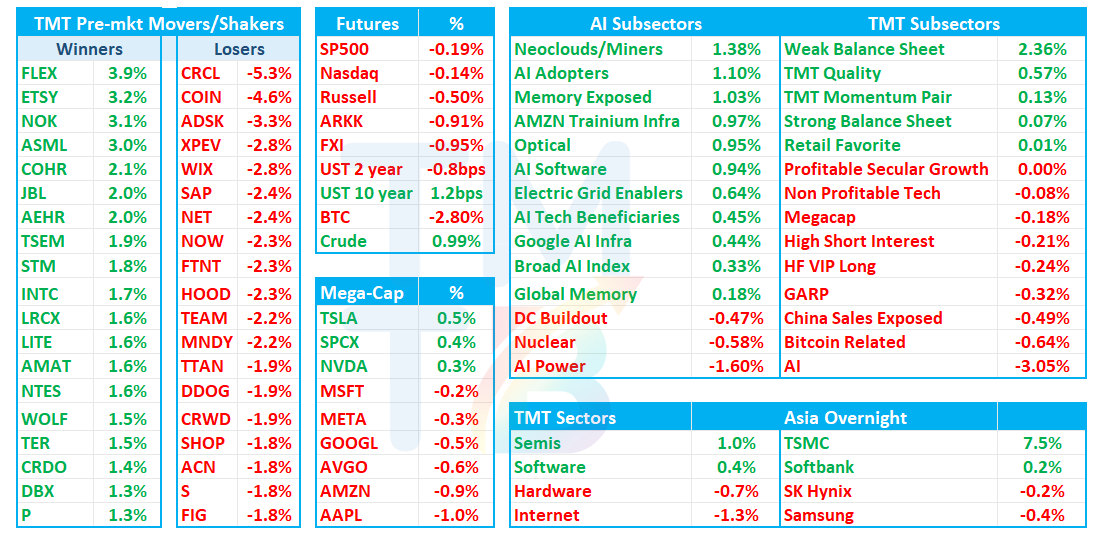
Good morning. QQQs -15bps / SPX -20bps to start with Oil +1% and yields mixed - 10 year pushing past 5% while 2 year yields slightly down as global yields were up in Europe and Japan. Semis +1% bouncing early at the expense of software -1% after yesterdays 10%+ spread between the two, the biggest gap in history.
Overnight, Asia weaker: TPX -0.52%, NKY -0.01%, Hang Seng -1%, HSCEI -0.96%, SHCOMP -0.54%, Shenzhen -0.82%, Taiwan TAIEX -0.77%, Korea KOSPI -0.85%
CRM Dreamforce starts today with Sam Altman expected and Dario tomorrow. CLARITY vote today (20% chance of approval according to Polymarket). Fed meeting tomorrow where >90% odds of a rate hike by Warsh.
Let’s get to it…
NVDA: SemiAnalysis says real-world Rubin economics are already far ahead of GTC claims, with up to 7x throughput/MW
SemiAnalysis says pre-release Vera Rubin is already delivering up to ~7x Blackwell’s token throughput per MW versus NVIDIA’s ~3x GTC claim, with further upside as software/kernels mature. SemiAnalysis estimates that despite Rubin renting at >$8.50/chip-hour versus ~$5 for Blackwell Ultra, Rubin still produces ~62% more tokens for the same 3-year rental TCO at 80 TPS P90 interactivity and up to ~16x more at the high-interactivity frontier. The read-through is that Rubin’s higher upfront/rental cost is more than offset by inference economics, supporting rapid upgrade adoption and continued NVDA pricing power.
NOK: Rosenblatt initiates Buy/$15, says AI optical franchise is mispriced at a telco multiple
Rosenblatt says Nokia Optical grew 20% y/y in 2Q26 while AI & Cloud revenue more than doubled, with €2.8B of AI/Cloud orders and roughly half expected to convert within 12 months. Rosenblatt sees the optical TAM expanding ~35% CAGR to $40–50B by 2030, with scale-out and eventually scale-up providing incremental upside beyond DCI/scale-across, and assumes no scale-up contribution in 2028 estimates. Rosenblatt also highlights U.S. InP laser capacity and Infinera integration as share/margin levers, arguing NOK should increasingly rerate from a telco multiple toward AI infrastructure.