

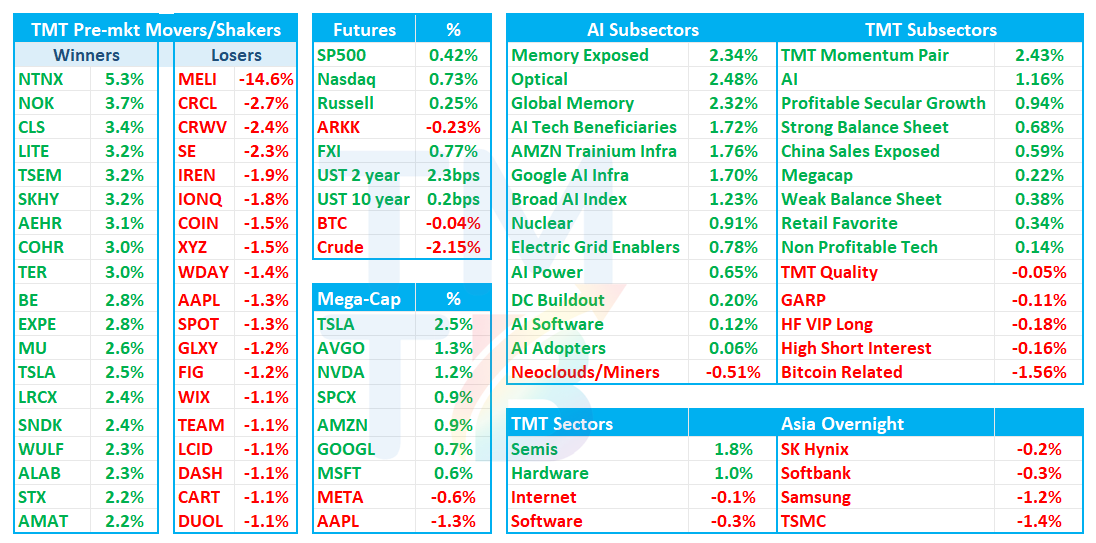
Good morning. QQQs +75bps early with stocks catching a bid after META announced its equity raise ($35B being raised now out of a total of $95B). Semis +1.7% leading the way higher trying to put together a bounce.
Anthropic S-1 set to drop at 9am ET so get your Claude’s ready…

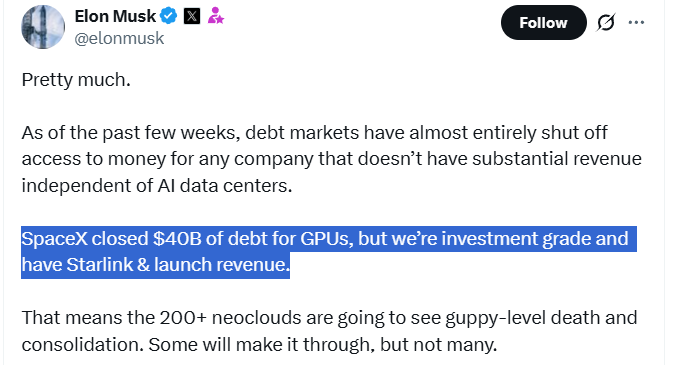
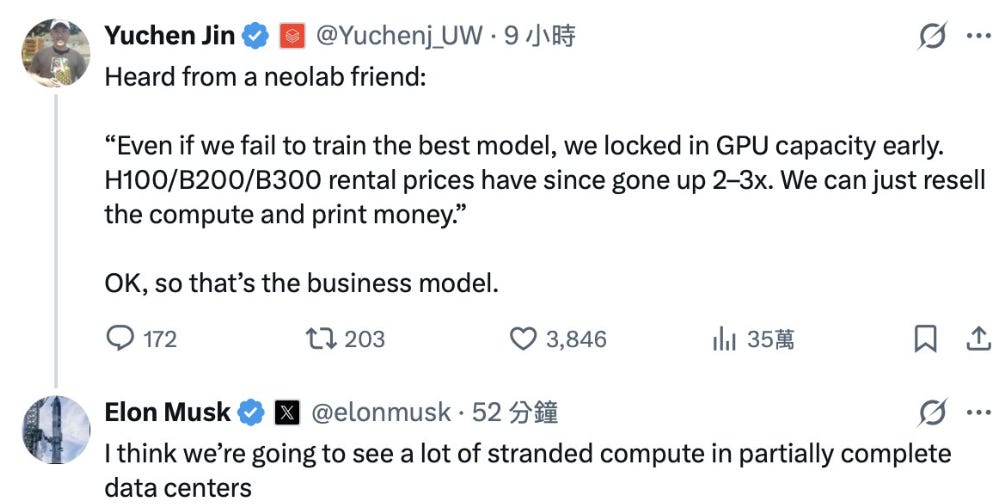
In Tech, Memory +2-3% leading semis higher, TSLA +2.5% on a Barclays upgrade, MELI -15% as Bolsonaro beat Lula in a surprise results in Brazil, SPCX +1% after raising $40B in debt from Apollo & CRWV -2% on Elon’s tweet storm over the weekend, suggestion debt markets had all but closed for Neoclouds.
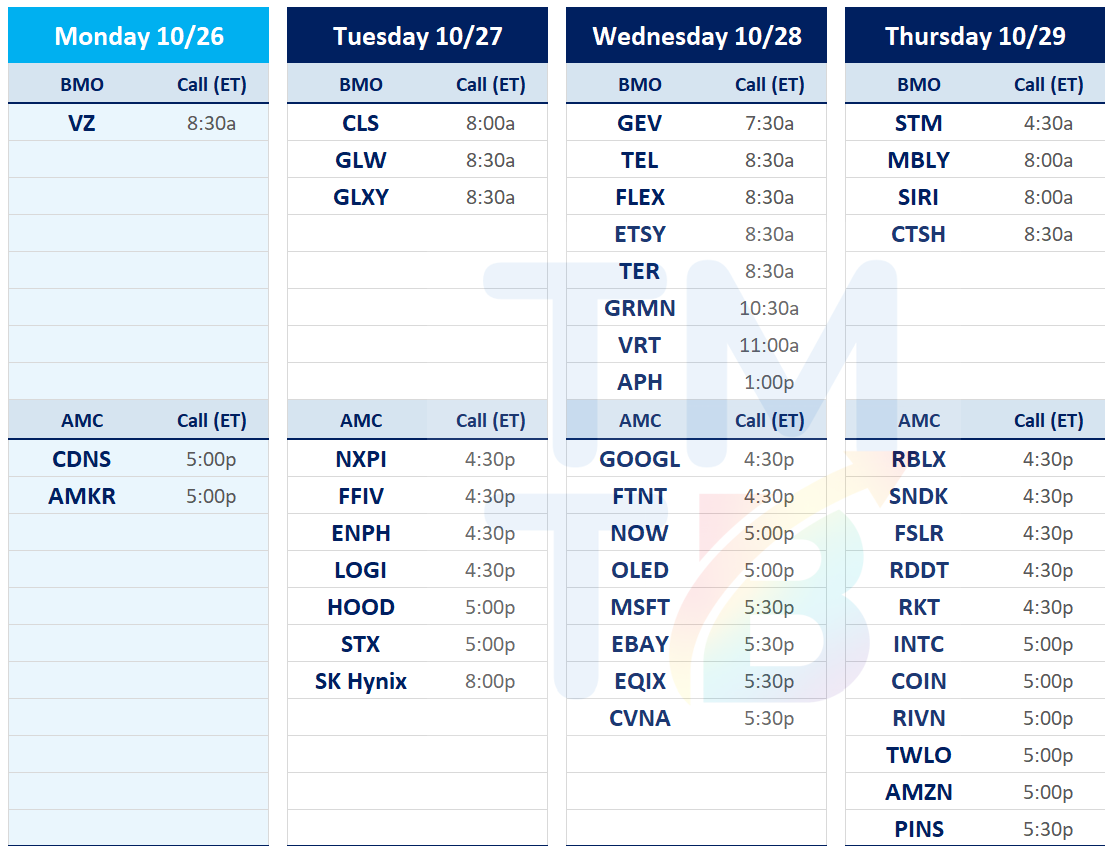
Already looking like it’s going to be a very fun week and we got a full earnings lineup in Tech as well with GOOGL/MSFT on Wed and AMZN on Thursday. We’ll have some bogeys out later today or tomorrow.
Asia saw mixed price action overnight: TPX +0.18%, NKY -0.8%, Hang Seng +0.51%, HSCEI +0.59%, SHCOMP +0.19%, Shenzhen -1.13%, Taiwan TAIEX -1.8%, Korea KOSPI -1.46%. Memory was flattish.
Lots to get to this morning, so let’s get to it. We’ll start with META and SPCX…
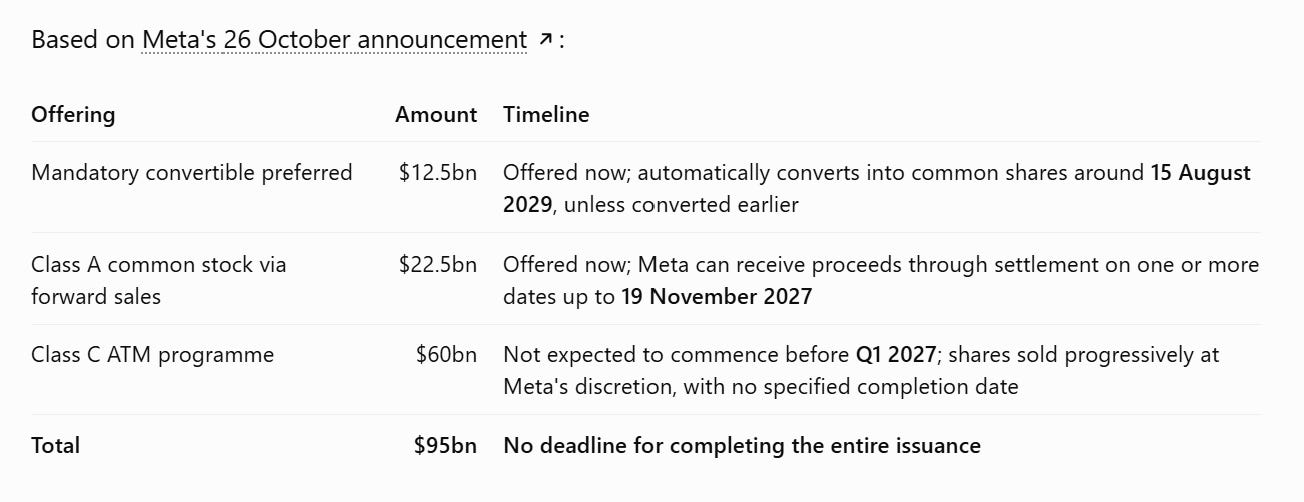
META: To offer $22.5B of Common stock, $60B of Class C stock, and $12.5B of Preferred - Bloomberg
NVDA AMD AVGO interested in buying $5B in aggregate
Timeline: (h/t Zackin Slack)
SPCX: Elon says they raised $40B in Debt and talks down neoclouds in weekend tweet storms
Debt deal led by Apollo with Apollo-backed Atlas SP slated to manage the entity, Under the contemplated master finance lease, the Equipment will be delivered in tranches, each of which will be subject to a separate lease schedule with a term of approximately five to five and one-quarter years from the applicable commencement date.


TSLA: Barclays upgrades to OW/$450 as SPCX takeout optionality joins improving core + Robotaxi inflection
Barclays upgrades TSLA to OW and raises PT to $450, arguing upside is no longer just about a potential SPCX combination: core auto trends are improving after two years of declines, Energy is nearly sold out for 2027 with >50% shipment growth potential on data-center demand, and Robotaxi miles have inflected sharply alongside FSD uptake >75% on newly purchased North American Teslas in 3Q. Barclays still sees a potential SPCX/TSLA merger and associated premium as an important catalyst, but now views improving fundamentals and Robotaxi momentum as standalone support for the stock.
TSLA: DB says SpaceX merger could become the main stock driver; Robotaxi progress tangible, Optimus still early
DB keeps Buy/$420 and says a potential SpaceX combination may increasingly anchor TSLA’s valuation, potentially creating a floor as investors handicap the premium needed to secure shareholder approval. Robotaxi is the clearest operating positive: unsupervised miles reached 3.1M, ~9x in three months, Cybercab is already in paid Austin service, and broader 24/7/geographic expansion is planned into 2027. Optimus remains much earlier, with production-quality units starting but management still describing a difficult S-curve; DB does raise energy-storage expectations as AI data-center demand improves pricing
SPCX: DB raises PT to $250 as compute pricing + capacity economics look better than expected
DB says near-term estimates remain too low after 3Q, with Customer B already generating ~$1.68B/month vs. its prior ~$1.25B assumption, suggesting an earlier renewal and/or pricing above the original ~$31/GW. DB also sees SpaceX’s vertically integrated build model sustaining ~$35–36B/GW capex, with a 440K Vera Rubin GPU training cluster (~1.3–1.4GW) due by 2Q27 and spot-market economics implying ~8–9 month paybacks. Funding looks manageable despite a ~$175B gap under a 10GW 2027 build scenario, with DB expecting investment-grade/GPU-backed debt; Buy, PT $250 from $235.