

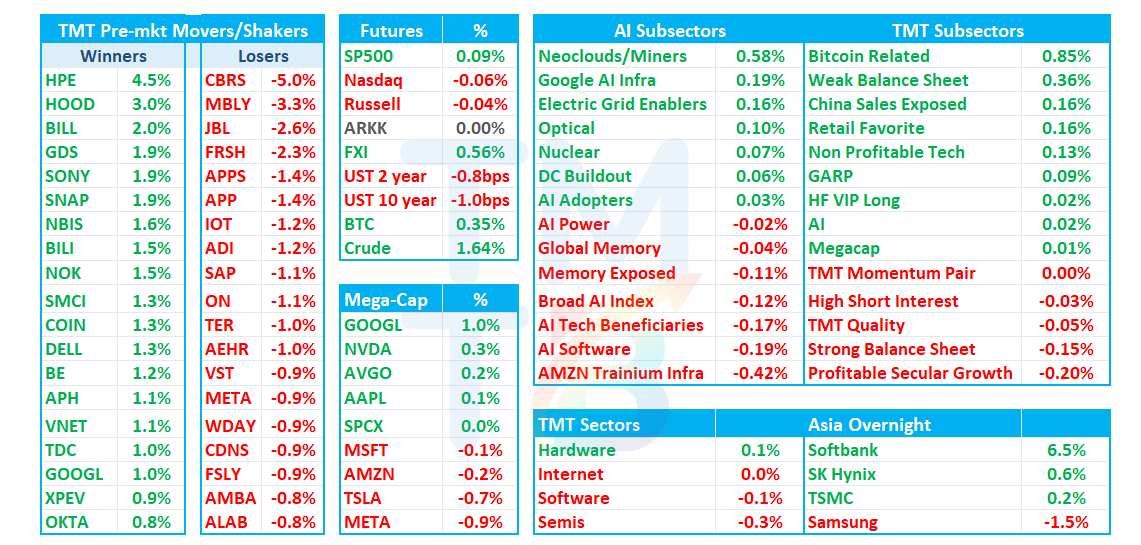
Good morning. QQQs hovering around flat as macro was relatively quiet overnight. Oil +1.6% while yields are flat.
In Tech, we get SNPS analyst day, HPE Networking event (stock +4% after raising FY27 networking growth to highs teens/low 20s and increasing synergies target to $800M vs. $600M), and MU earnings (bogeys below). CBRS -5% the main loser after reports Ultrafast is using NVDA chips instead of theirs. HOOD +3% after more agentic announcements yesterday. GOOGL +1% the Megacap standout as rumored benchmarks of Gemini 4 Pro continues to make the rounds on X.
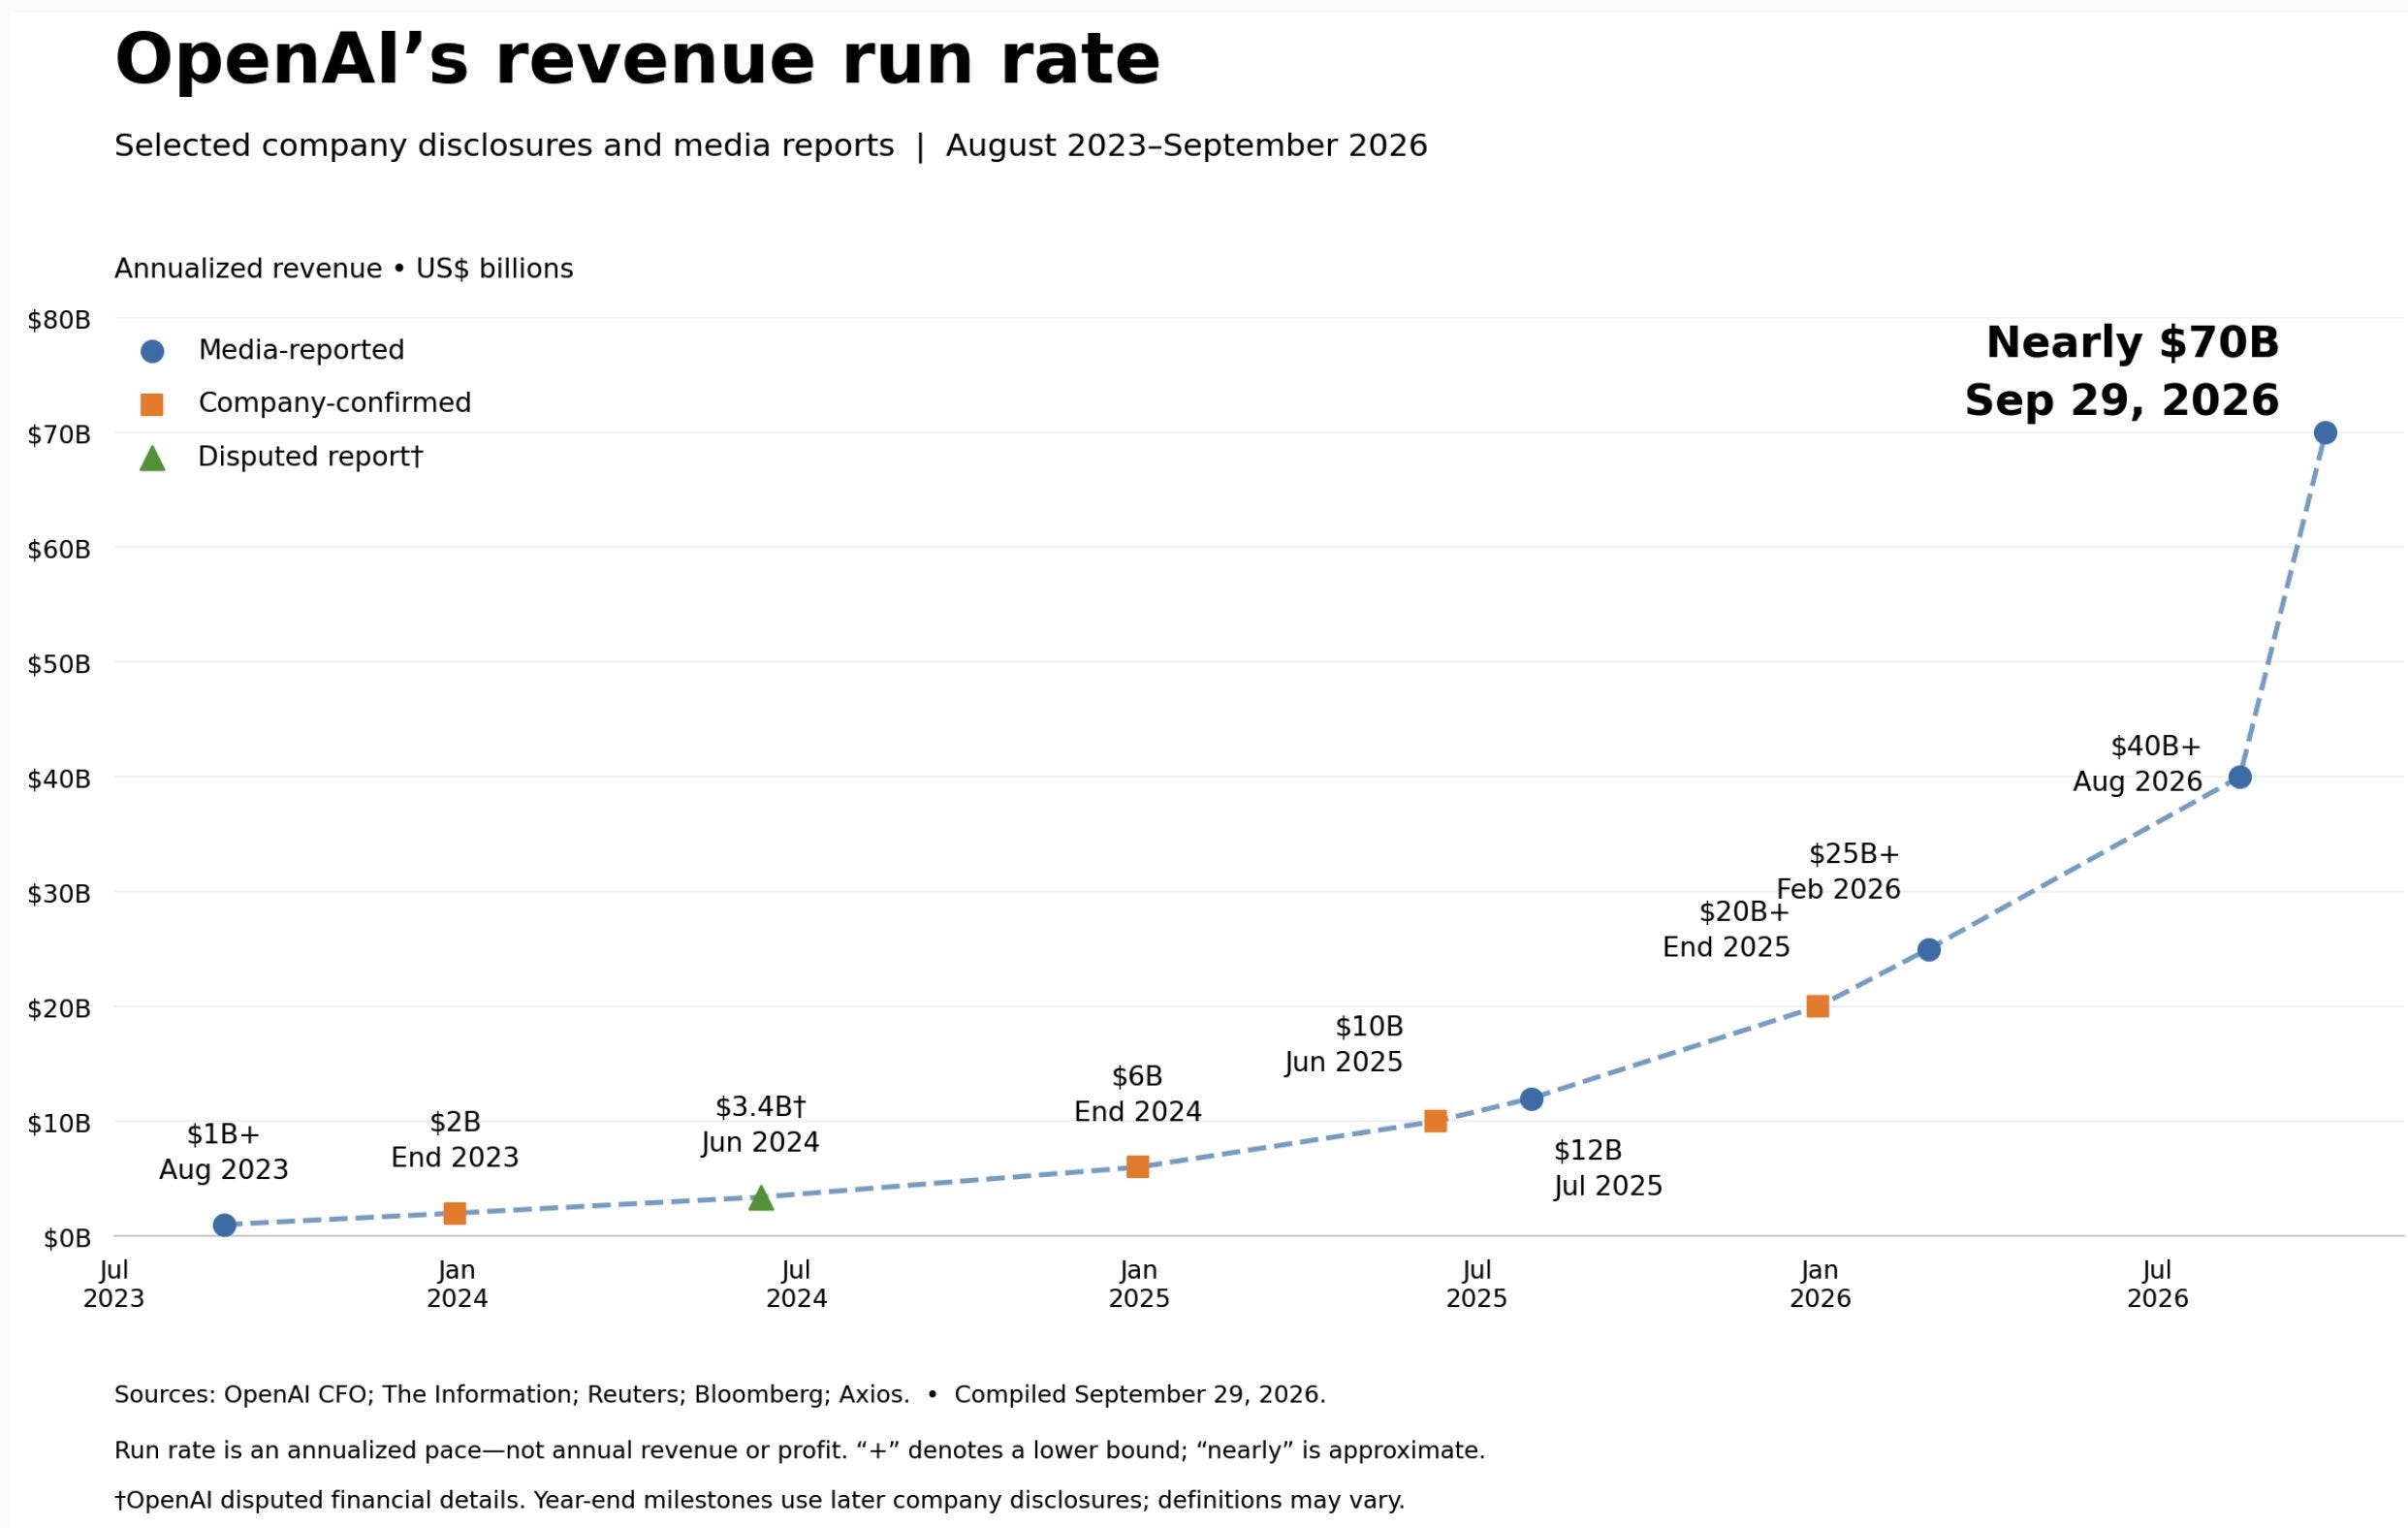
Overnight, Asia mixed to green: TPX +1.67%, NKY +1.94%, Hang Seng +0.37%, HSCEI +0.5%, SHCOMP +0.31%, Shenzhen -0.23%, Taiwan TAIEX +0.65%, Korea KOSPI -0.48%. Softbank +6.5% following OAI proxies up after ARR numbers.
Lots to get to this morning, so let’s get to it…
CRWV/NBIS: William Blair initiates OP, sees neocloud market growing ~10x to $250B by 2031
William Blair estimates global neocloud revenue grows from ~$25B in 2026 to ~$250B by 2031, supported by inference, agentic workloads, enterprise AI, hyperscaler offload and sovereign compute; CRWV, NBIS, IREN and Nscale already have roughly $275B of customer commitments. Blair initiates CRWV and NBIS at Outperform, calling them the best-positioned scaled players given power/capacity access, financing capability and execution, with both increasingly moving up-stack into broader cloud/software services. The key debate is whether today’s attractive economics survive normalization: GPU pricing has been stickier than expected and paybacks are shrinking, but returns remain highly sensitive to utilization, pricing and leverage as hyperscaler-owned capacity ramps.
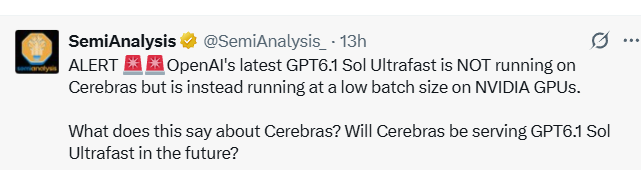
CBRS: Semianalysis says OpenAI Ultrafast not running on Cerebras
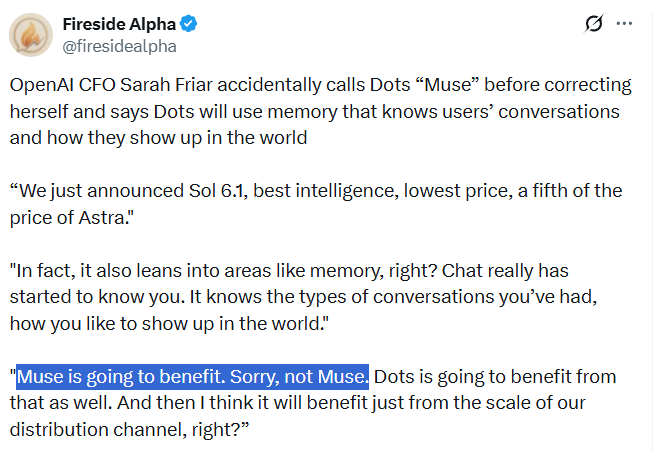
OpenAI:
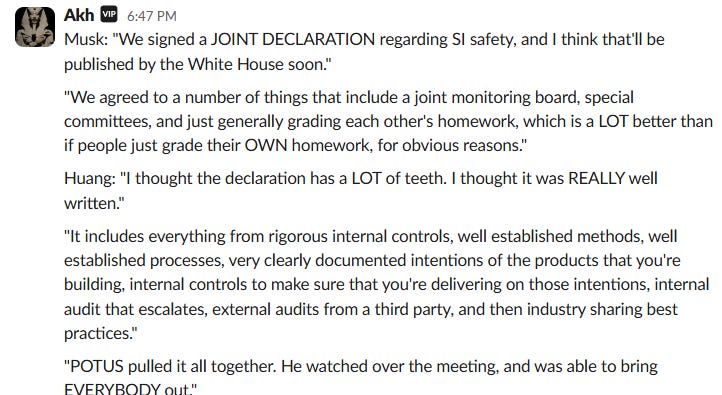
AI Safety: WH Meeting seemingly goes well
Reuters reports President Trump and AI executives signed a voluntary safety pact that includes independent audits and internal controls to prevent unauthorized access to computer networks. The administration also backed further data-center expansion. Trump is considering a roughly 10-person oversight committee and plans to name a new AI official, while the agreement relies on voluntary commitments rather than new binding federal regulation.

APP: Wells says eComm pixel acceleration looks like a false start, mostly APAC/no-traffic sites
Wells says recent APP pixel additions have accelerated, but the inflection is largely APAC Shopify sites with little or no web traffic; when weighted by traffic, adoption remains roughly flat, suggesting no meaningful customer-growth inflection exiting 3Q, sees customer acceleration unlikely before 2027; stays EW/$325.
MBLY: Barclays downgrades to EW as advanced ADAS wins lag and VW/China risks rise
Barclays downgrades MBLY to Equal Weight from Overweight and cuts PT to $9 from $14, arguing the company still has not landed enough large advanced-content wins to validate the longer-term ASP/growth thesis despite resilient near-term results. Barclays sees added risk around the VW ramp, where SuperVision carries ~$1,300 ASP vs. ~$50 today and Surround ADAS ~$125 vs. ~$46 base ADAS, but launch delays and potential competition from Horizon/Rivian could pressure the expected ramp. CEO transition adds execution risk while China is also becoming a bigger overhang as Horizon has reached roughly half of the China L2 ADAS market versus MBLY at ~25%
WDAY: 2.5% RIF focused on product/tech, FY27 guide intact
WDAY announced a 2.5% RIF focused mainly on product/technology, alongside select office reductions, while still planning to hire in strategic areas, suggesting a shift toward AI talent. FY27/F3Q27 guidance was reiterated except for lower GAAP operating margin from $65–80M of restructuring charges; non-GAAP estimates are unchanged.