

No TMTB EOD Wrap today - we are on the road
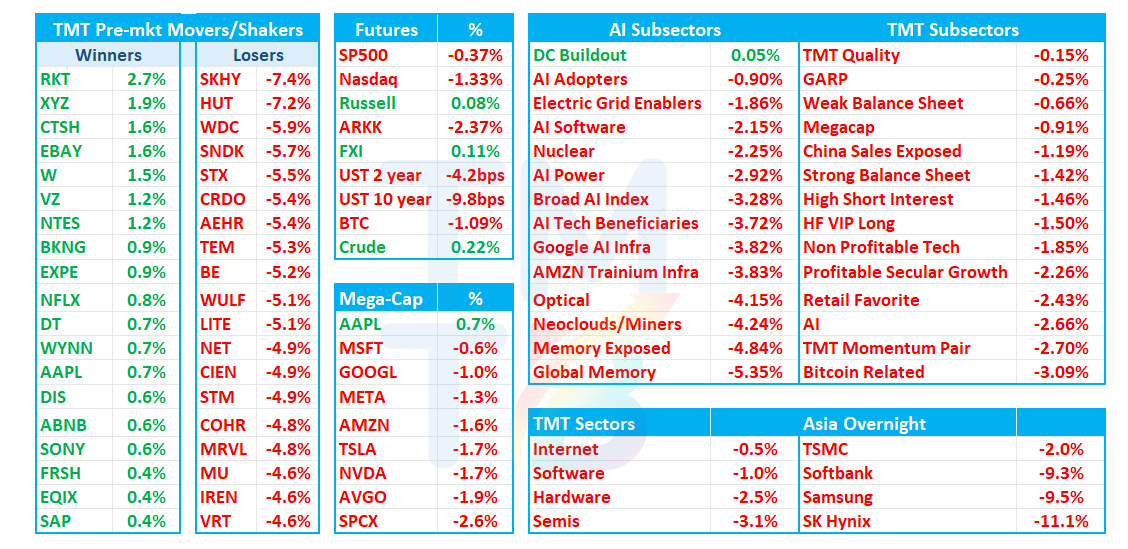
Good morning. QQQs -1.2% / SPX -30bps / Russell flat with yields down 5-10bps across the curve and Crude flat as semis leading the way lower again.
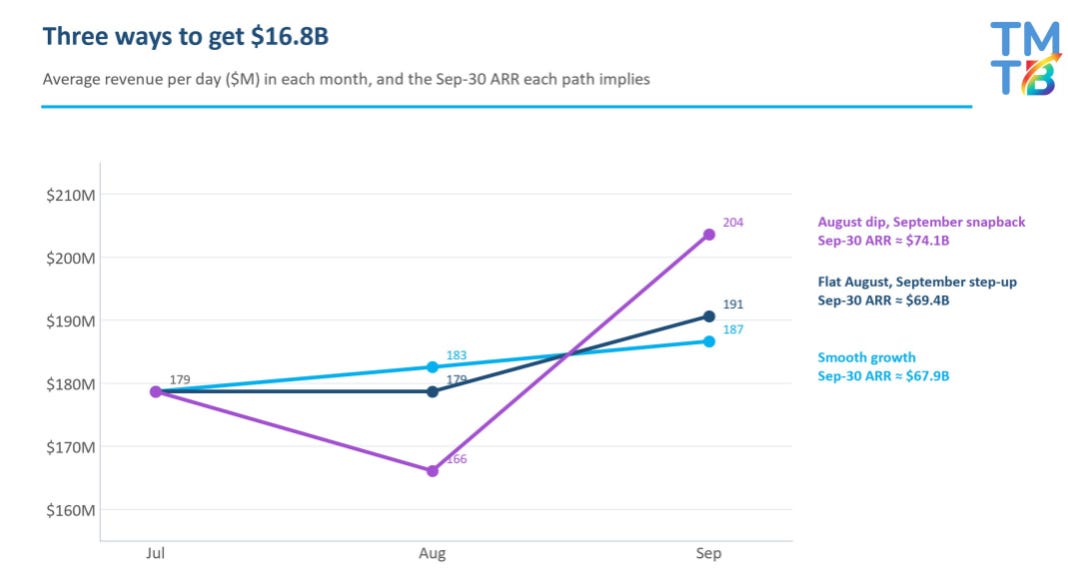
Big news last night was the snippets we got from Anthropic meetings with investors: FT/Reuters reporting that Anthropic told investors Q3 revenue rose 45% sequentially to $16.8B, slowing from roughly 140% growth in Q2. Anthropic told investors that it was cash flow positive and banking $1.70 in revenue for every $1 spent on computing power in the third quarter, and operating margins were 11% (FT). The FT also reports distillation accounted for 5–7% of revenue and was materially curtailed during Q3.
Reuters was also out saying “Anthropic could see its annual revenue run rate reach $110 billion by the end of the year, according to estimates from analysts who met with company executives earlier this week.” Reporter clarified:

So it doesn’t seem like official company guidance and just a re-hashing of old expectations
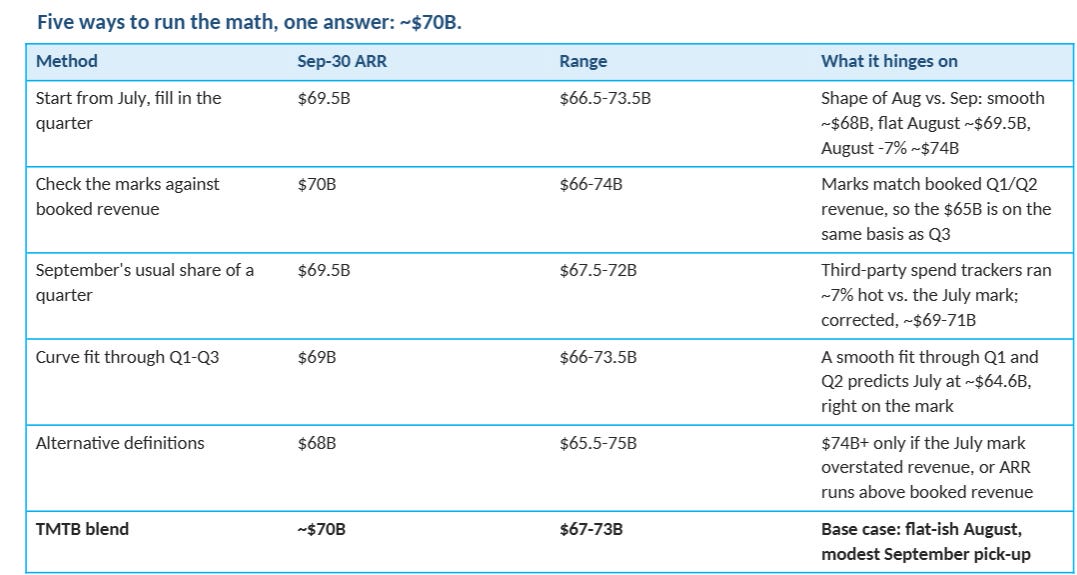
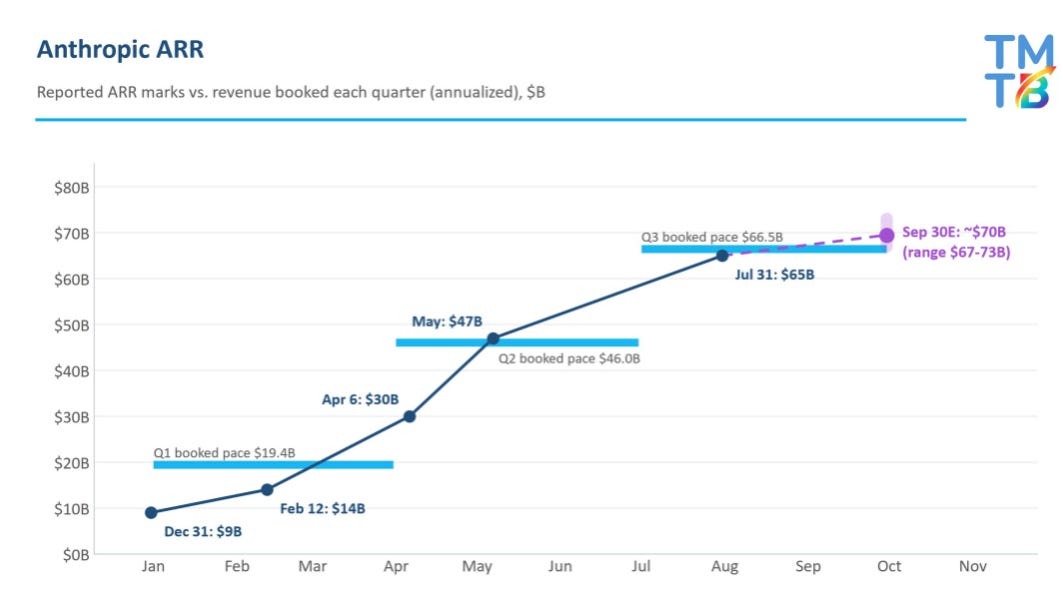
Our best guess for Sept ARR comes to ~$70B, but without more disclosure, the figure could be anywhere from $67 - $75 depending on the shape of revenues (for example, if August was flat with July, implies $70B, but if August was -7% m/m, then that would imply $74B). Anthropic counts usage revenue from the last 28 days x 13, plus one month of subscriptions x 12 (as described by Reuters). In practice, ARR = average daily revenue over the last 28 days x 364.
All a bit confusing, I know. Some charts to help clarify:
Lots of debate about how much distillation/META/MSFT headwinds affected the Q3 number (along with slower summer seasonal months + Astra’s release in September) with a rough estimate probably around $4-7B, which would have put ARR in mid to high 70s range. No hints around how October was trending, but most expecting a re-accel given Opus 5.5/Sonnet traction.
Still conclusion is that it was below investors expectations who expected ARR in the high 70s and still were hoping for $100B YE ARR, which now seems more in doubt. The #’s won’t help sentiment for investors in the AI trade who were hoping for higher growth that would confirm the ability to fund the buildout and if better OpenAI ARR #s couldn’t get the mkt up, hard to see worse Anthropic numbers doing that although to be fair we are more washed here than a couple weeks ago. It will be great once we have financials from these labs in hand so investors don’t have to through this whole exercise again, but for now it looks like all eyes will be on any tea leaves we get from the October number.
Early on, Semis -3% with Internet/Software -1%. Memory weakest (SKHY -7%, SNDK -5%, HDDs -5%) as Musk continues to do this to pour cold water on sentiment:

TSM-2% after a solid quarter where they raised FY26 but Q3 GMs a touch light.
Overnight, Asia generally weaker with Korea limit down at one point: TPX -2.38%, NKY -4.9%, Hang Seng -1.03%, HSCEI -0.98%, SHCOMP -1.59%, Shenzhen -2.64%, Taiwan TAIEX -3.41%, Korea KOSPI -7.57%. Hynix -11%; Samsung -10%; Softbank -9%
We’ll hit TSM Earnings first then onto the usual…
TSM: Stronger revenue guide and AI demand, but N2 dilution misses buyside margin bogeys
TSM delivered a modest 3Q revenue/EPS beat and guided 4Q revenue to $52.3–54.3B, implying +14% q/q/+58% y/y at the midpoint, roughly 5–6% above Street, lifting FY26 revenue growth to ~44% from slightly above 40%. The disappointment was margins: 3Q GM of 66.4% missed the 67.5% buyside bogey, while the 4Q midpoint of 66% missed ~67%, reflecting the steep N2 ramp and overseas dilution. Mgmt’s AI commentary remained strong, with no slowdown, potential upside to accelerator growth and demand broadening into CPUs/networking. FY26 capex stayed at $60–64B despite expectations for a higher midpoint, although the multi-year expansion message became more aggressive.
Key quotes: