

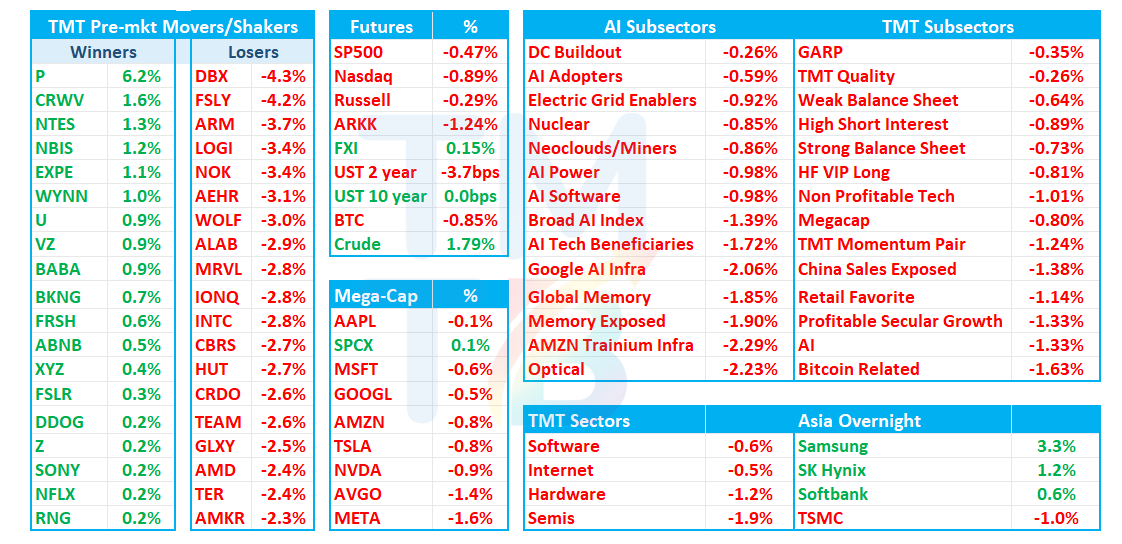
Good morning. QQQs -90bps as the market continues to digest the yield and Crude spike from yesterday. Yields hovering around flat today while Crude is up another 2% (overnight, Iran official warned they may expand war to Indian Ocean of US attacks again). Fed expects have shifted more hawkishly over the past week with the market now pricing in closer to 80% chance of hike at the next meeting and 36bps worth of hikes this year (and 55bps in 27).
In Techlandia, META -2% digesting a bit after Connect day 1, where they talked up Muse partnerships and announced a new set of VR glasses among other things (more detail below). Semis -2% leading the way lower as Software/Internet -50bps hangs in better. CRWV/NBIS +1-2% the standouts in semis after a couple of sell-side upgrades. P +6% after giving out much better targets at their analyst day.
Overnight, Asia generally weaker while Korea was closed: TPX -0.39%, NKY +0.76%, Hang Seng -0.29%, HSCEI -0.09%, SHCOMP -1.22%, Shenzhen -1.97%, Taiwan TAIEX -0.28.
Ok, lots to get to, so let’s get to it…
CRWV: JPM upgrades to OW/$125, says premium short-duration contracts drive revenue/margin upside that outweighs higher capital needs
JPM says CRWV’s pricing backdrop has strengthened materially, with July pricing +25% across SKUs, recent short-duration contracts signed around ~$40M/MW, and short-term capacity commanding roughly 3x long-term pricing. JPM expects the better mix to drive 5–10pts higher contribution margins, sees 4Q26 operating margin at 15.3% vs. 14.1% consensus, and raises long-term margin expectations to ~20% from high-teens despite continued heavy capacity build. JPM upgrades to OW from Neutral, raises Dec-27 PT to $125 from $120, and improves FY27 EPS by ~28%.
NBIS: BNP upgrades to OP/$399, sees 2027 as key catalyst as scarcity pricing drives materially higher AI Cloud returns
BNP Paribas says Nebius’ outlook has improved meaningfully, with a path to ~$22B+ ARR exiting 2027, ~30% above consensus, as META/MSFT capacity ramps and incremental capacity reprices higher. BNP models ~$20M/MW for new AI Cloud capacity, implying >25% ROIC, while recent GB300 deals near ~$40M/MW suggest 60%+ ROICs and ~1-year paybacks; Vera Rubin could provide further upside. BNP raises 2026/27 EPS by 17%/37%, upgrades to Outperform from Neutral and lifts PT to $399.