

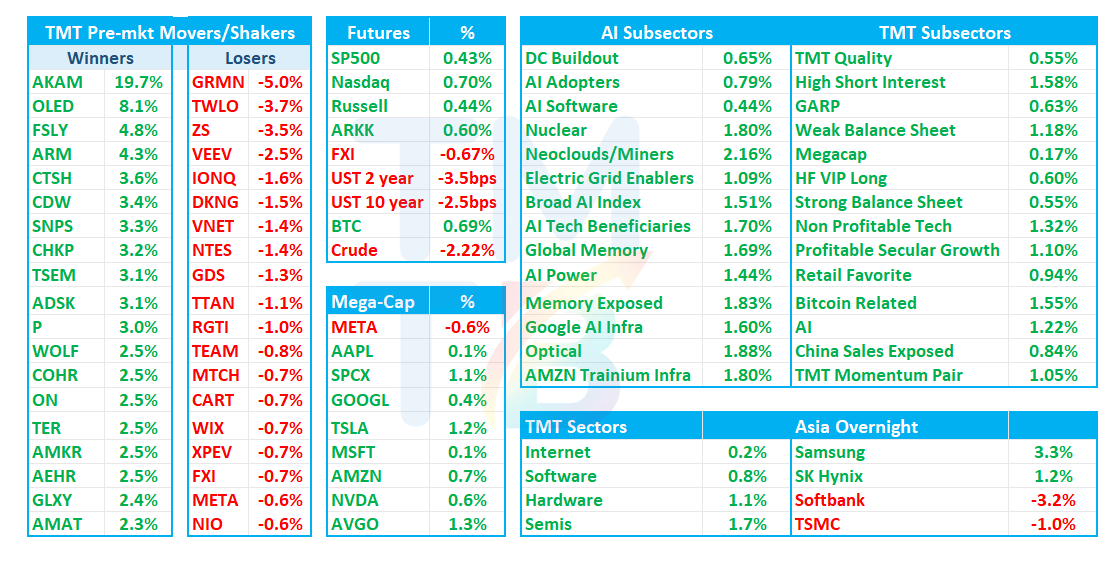
Good morning. QQQs +70bps as investors digest a wave of headlines pointing to a possible diplomatic off-ramp between the US and Iran around Hormuz. The reports first began circulating during Thursday’s session, with Iran later confirming it had sent Washington a proposal that would restore the framework of the June MOU within seven days, after which the two sides would begin talks on Tehran’s nuclear program. Yields ticking down 3-4 bps across the curve although Crude +2.5% is staying bid.
In Tech land, Semis +1.8% helped by the big AKAM/Anthropic deal annoucned after the close for “accelerating CPU workloads”. AKAM +19%. CPU names bid: ARM +4% / AMD +2% / INTC +2%. META -50bps looking to digest some recent strength. SNPS +3% on an HSBC upgrade while TWLO -4% on an HSBC downgrade. DDOG +1.5% as Wolfe says checks show increasing likelihood of being involved with META’s Muse.
Overnight, mainland China and Korea were closed but otherwise Asia mixed: TPX +1.31%, NKY +1.3%, Hang Seng -1.01%, HSCEI -1.21%.
Happy Friday. Let’s get to it…
AKAM: $11.6B Anthropic deal to support Anthropic’s “accelerating CPU workload demands” transforms CIS growth outlook, with potential expansion to ~$20B
Sell side generally positive on the deal, saying Anthropic’s 7-year ~$11.6B commitment is a major validation of AKAM’s cloud infrastructure strategy, with an option for another ~$9B that could take total contract value toward ~$20B. Revenue contribution is minimal in 2026, builds to roughly $150–300M in 2027 and ramps through 2028 toward a ~$1.7B annualized run-rate, materially accelerating CIS growth. The deal requires substantial upfront capex and likely pressures FCF near term, but sell side sees the stronger revenue visibility, premium CPU economics and potential follow-on frontier-lab wins as enough to shift AKAM from a “value” story toward a higher-growth compute asset.
Read-throughs from Claude:
AKAM’s cloud already runs on AMD EPYC. The current top tier is 5th-gen EPYC and the one before it is 3rd-gen. I found no Intel or Arm servers anywhere in their lineup. The dollars are modest for AMD. My rough math is about $1–1.4B of CPUs over 2027–28. NVDA previously flagged Akamai’s Vera deployment plans. Vera targets agentic workloads (code, orchestration, data processing) with high-bandwidth LPDDR5X.
JBL. The 8-K has Jabil holding Akamai’s $1.7B of memory on consignment and buying it back at cost as it uses it. That means Jabil is building the servers. It’s big revenue at thin margins.
Lenovo (992 HK / LNVGY). It signed a new 7-year hardware deal with Akamai on 9/23, likely the second server supplier.
SNPS: HSBC upgrades to Buy/$700, sees business model shift + agentic AI turning Synopsys into an AI beneficiary
HSBC says SNPS is moving toward a licensing-plus-royalty model in Design IP while agentic AI could shift EDA from human-seat subscriptions toward higher-value usage/consumption as agents orchestrate more design work. HSBC sees these changes driving revenue growth to ~15% in FY27 vs. ~11% consensus and lifting the earnings CAGR from ~7% in FY24–26 to ~28% in FY26–28. Upgrades to Buy from Hold and raises PT to a Street-high $700 from $490.