

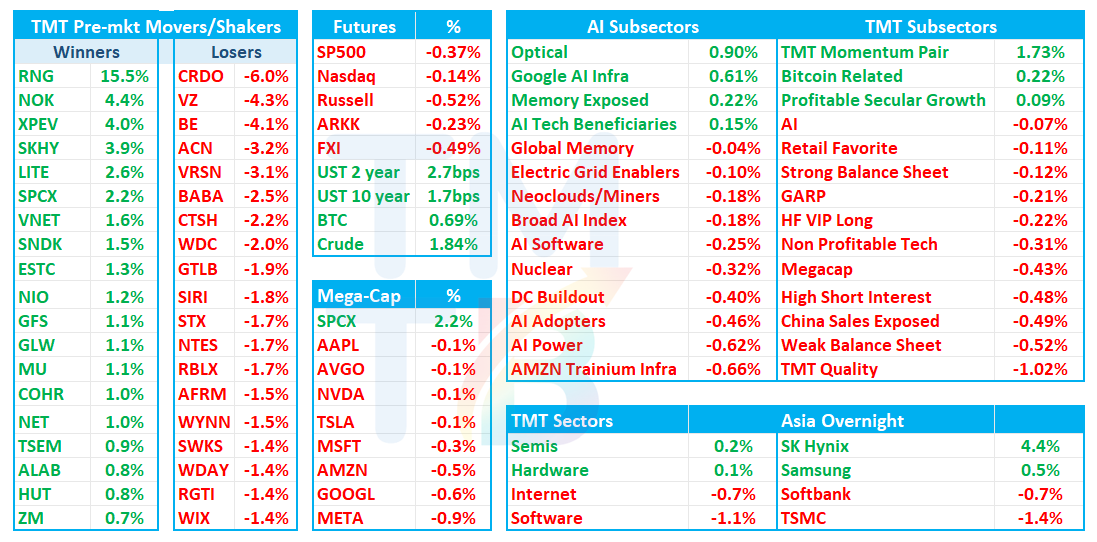
Good Morning. QQQs -15bps after a sea of red yesterday with Oil +1.3%. Yields +2-3bps across the curve. Lots of pain across the board yesterday: GS said Global Fundamental L/S managers, Multi-strats and Systematics all fell more than 1% on the same day for first time since Covid
In Tech, Semis flat while software -1%. WDC -2% despite handedly beating bogeys, BE -4% on a beat and raise, SPCX +2% on a sell-side upgrade and on reports they’re in talks to access 80k cell sites (Towers +7-8%; Telcos -4-5%). INFY -7% on lowered rev guide. RNG +15% on a set of good numbers.
Asia held in well despite the big declines yesterday in U.S.: TPX -0.79%, NKY -0.34%, Hang Seng +0.69%, HSCEI +0.87%, SHCOMP +0.89%, Shenzhen +2.44%, Korea KOSPI +0.3%. Hynix +4%; Samsung +0.5%
We’ll hit WDC BE VRSN RNG Earnings first, then onto the usual. Happy Friday! Let’s get to it…
WDC -2%: Beat and Raise above buyside bogeys, pricing Is Still Accelerating, but pushback is lower cost/TB decline and concerns around supply with higher capex
Recap: FQ1 revenue/EPS of $4.38B/$4.64 beat Street $4.14B/$4.10 on $/TB up 28% y/y. The FQ2 guide of $5.1B/$5.80 is ~12%/~20% above Street ($4.57B/$4.82), with GM guided to 60-61% vs. Street ~57.4%. FQ2 guide implies ~52.6% OM (Street ~49%) and ~75% q/q incremental GM. Opex steps up to $400-410M on product qualification costs.
$/TB accelerated to +28% y/y (from ~18% last q), mgmt expects Dec-Q growth to be higher still with pricing mostly locked, and it sees room to keep expanding y/y gains for another 3-4 quarters, which is driving ~80% incremental GMs. Exabytes (+22% y/y, below the >25% target for a second straight quarter) and cost/TB (only ~4-5% lower y/y on DRAM/NAND inflation) were the soft spots.
Overall solid set of numbers, especially given positioning as stock is down 50%+ since June highs and 20%+ since Oct 1st Toshiba news coming in (one of the worst performing stocks in AI semis). Stock was flat initially AH but fell another ~5-6% after hours after mgmt said capex “modestly above” the 4-6% range next to talk of accelerating exabyte supply growth. Neither message was new, but both touched on the post-Toshiba supply nerves.
Buyside numbers going up slightly morning and still sit around $60+ for CY‘28 vs street at $45 so trading at around 5x at sub $350. Bulls will like the accelerating rev % y/y and price increases to roll through the next 3 q’s with incrementals at 80%, which means still room for margins to keep rising. Bears will pushback on industry dynamics changing for the worse, mgmt’s comments on “pricing moderation” after 3-4 qs (although they walked that back on callbacks), and slower cost/TB declines.
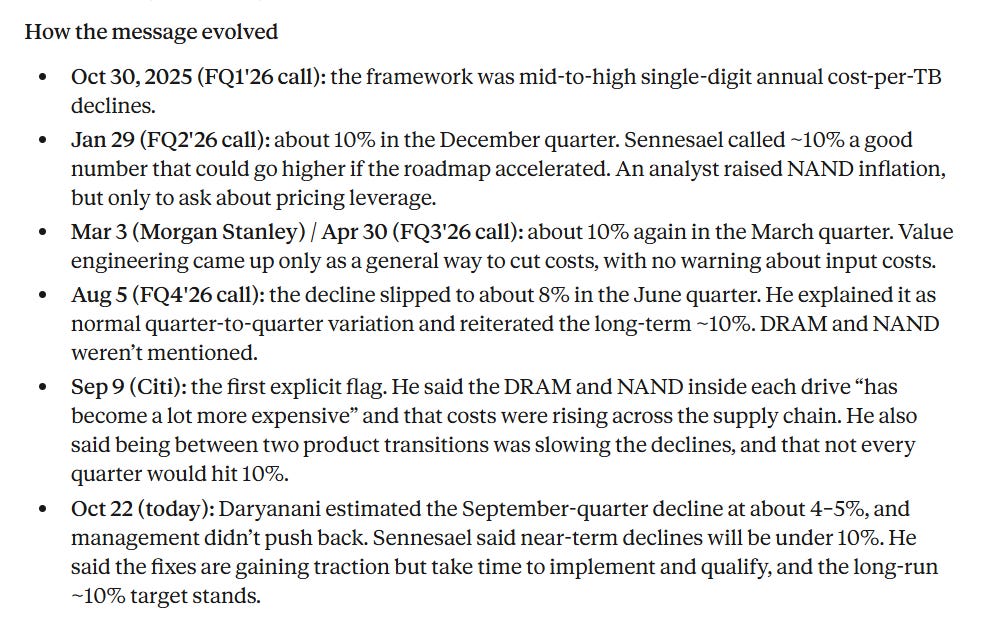
Despite stock selling off on capex comments, message was the same as Citi conference:
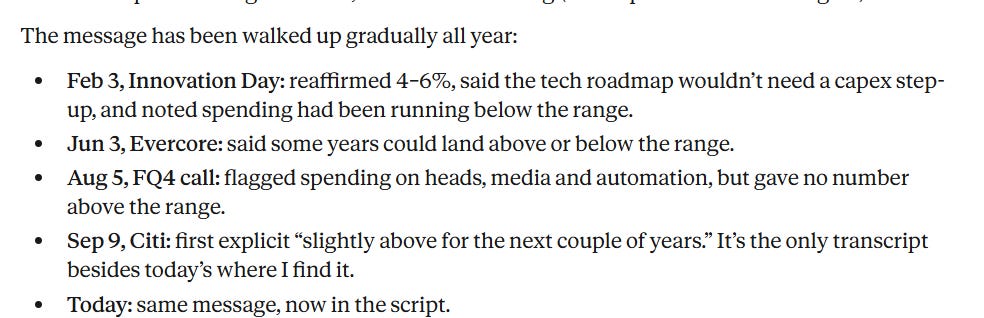
On input costs, language was slightly more explicit than at Citi with only a 4-5% decline but kept 10% LT target alive
Key Takeaways
Pricing. Blended $/TB rose 28% y/y and ~9% q/q (nearline +26% y/y, +8% q/q), up from ~18% in the June quarter and ~9% in March. Strength showed up in both nearline and client/consumer (client revenue more than doubled y/y). The drivers:
contractual escalators as LTAs hit their anniversaries
expiring LTAs renewed at higher prices
strong spot pricing on non-contracted exabytes
mix toward higher-capacity drives
Dec-Q $/TB growth is guided above 28% (implied mid-to-high 30s%). HAMR will be priced at parity with ePMR per TB (“the price is the price”), so WDC won’t be buying HAMR share with introductory discounts. Incremental: pricing is now running well above the high-teens framing the Street had treated as sustainable.
Margins. GM of 58.1% (+1,420bps y/y, +370bps q/q) beat Street ~55.6% and the 55-56% guide, with >80% incremental GM both y/y and q/q. OM was 49.1% vs. Street 46.4% as opex fell to 8.9% of revenue. Mgmt laid out three durable GM drivers:
pricing (escalators, renewals, spot)
up-mix to higher-capacity drives, which carry a higher ASP per drive
more exabytes through areal density without adding fixed unit cost
In callbacks, mgmt said HAMR margins should be at least comparable to ePMR once at volume.
Exabytes. Shipments were 248 EB (+22% y/y, +7% q/q), with nearline at 223 EB (+22%, ~90% of EB). Both came in a touch below Street (~249-250 total, ~227 nearline). Growth was stuck at 22% for a second quarter, below the >25% LT target and well behind STX’s mid-30s. Mgmt called Sept-Q “the floor.” It expects growth to accelerate through FY27-28 as 40TB ePMR reaches ~30% of nearline bits in Dec-Q and ~50% in Mar-Q, followed by HAMR. Mgmt called 40TB ePMR the “fastest transition of any ePMR platform.” The 50% target is unchanged from August; the 30% is new. Asked whether ~35% EB growth in six quarters is the message, the CFO said “you’re thinking about it in the right direction.” Bears will say if WDC grows supply ~35%, STX ~30% and Toshiba doubles capacity, industry supply could outrun demand and the 28%+ price increases could reverse. In callbacks, mgmt said 35% isn’t guidance. The long-term target is still >25%; above 30% is possible but not guided, and the growth is meant to fill orders customers have already signaled.
Capex. Capex roughly doubled q/q to $227M (5.2% of revenue vs. ~3% in FY26).
New wording: the script now has capex “modestly above” the 4-6% range for the next two years, with the five-year average still 4-6%. In callbacks, mgmt said up to ~2pts above, i.e., ~7-8%, which is 3x+ FY26’s $418M in dollars.
Where it goes: head wafers (HAMR heads need more process steps and longer cycle times, which cuts throughput), media and glass substrates, and factory automation. It also covers more heads and media per drive as platter counts go from 11 to 12 and eventually 14. It is not for unit capacity: total platter counts are growing low-teens % y/y on minimal unit growth.
Costs. Cost/TB fell only ~4.5% y/y and was roughly flat q/q, vs. ~8% in June and ~10% in the Dec and Mar quarters. That is well short of the ~10% LT target. Mgmt blamed DRAM/NAND inflation inside the drives in a tight supply chain, plus being between product transitions. Value-engineering fixes are gaining traction but take several quarters to implement and qualify. Near-term declines will stay under 10%, with no timeline back to ~10%. Incremental: input costs were first flagged at the September conference, but this is the first time the slippage is this visible. This is where WDC’s ~2-year HAMR lag vs. STX shows up in the P&L. Pricing is more than covering it for now.
Competition. On Toshiba’s capacity plans and chatter about industry consolidation, mgmt said long-term industry fundamentals haven’t changed (25%+ demand CAGR, tight supply). It reiterated it will not add unit capacity. Mgmt argued the bottleneck is head and media capacity, not drive assembly. Players that rely on third-party heads and media may have to add units “just to maintain their share” and “will have a harder time” growing exabytes. WDC buys some external heads and media to benchmark its own, but only for lower-capacity drives; all leading-edge platforms use internal heads. That matters given reports of Toshiba’s interest in TDK’s HDD head business. If a competitor meaningfully adds units, WDC’s response “is going to be the same”: areal density, not units.
HAMR. The roadmap:
qualifications with two hyperscalers finish in CQ1’27
volume shipments start in 1H CY27
two more customers begin qualification in 1H CY27
2nd-gen HAMR (5TB/platter, ~55TB on 11 platters) begins qualification in 2H CY27
Mgmt says customers like its failure rates vs. what they’ve seen from other players. The “two hyperscalers” wording read as a step back from September, when mgmt said it was “in qualification with four large hyperscale customers” (see callback below). High-bandwidth drives are sampling with multiple customers for KV cache in AI inference and for video streaming. Mgmt is now working out how to price them, with impact from late CY27 into CY28.
Demand. Mgmt says revenue is limited by supply, not demand. All of its top seven customers provide visibility through 2030-31, the demand signal is “increasing” quarter after quarter, and the supply-demand gap isn’t going away near term. Mgmt framed four demand legs:
cloud, accelerating on video and AI-enabled services
training and RL
inference and agentic AI, with “tremendous” growth in logs, checkpoints and outputs
physical AI, led by AV customers in Asia and robotics
It argued softness in any one leg, including neoclouds, would be absorbed by the others. Incremental: in September mgmt said customers were asking to sign LTAs through 2030-31. Now it cites visibility through 2030-31 across all of its top seven customers.
Customers. Cloud was $3.9B (88% of revenue, +54% y/y, +16% q/q). Demand is broadening to enterprise and hybrid-cloud OEMs, neoclouds and frontier AI labs, which mgmt is now building into its forecasts and investment plans. Mgmt is selective on neoclouds, favoring strong balance sheets and quality end customers. Per callbacks, it also structures agreements to limit credit risk.
Cash. FCF of $1.38B (31% margin) came in ~8% below Street (~$1.50B). Capex doubled and inventory rose ~18% q/q (+$270M), built in components rather than finished goods ahead of EB acceleration; mgmt says any extra exabytes would ship immediately. WDC returned $1.06B ($1.0B of buybacks, $56M of dividends) and raised the dividend 17% to $0.175.
Callback. The most important takeaway: Dec-Q is largely de-risked. The vast majority of the quarter’s revenue is already under contract with pricing locked, and $/TB growth will exceed 28% y/y. Mgmt also walked back the scarier readings of the call:
~35% EB growth is not guidance; >25% remains the LT target, and >30% is possible but not guided. Supply growth is aimed at existing customer demand, not excess capacity.
Four hyperscalers remain in HAMR qualification (two finishing first, with two new customers to follow), so there is no pushout.
The 3-4 quarter pricing comment refers to y/y growth continuing to accelerate, with no set timeline for moderation.
The less comforting detail: LTAs mix fixed pricing, premium pricing on incremental volume and annual escalators. But commercial terms for the 2030-31 visibility years are not finalized, and purchase orders run only ~4-5 quarters out.
Bull vs. Bear Debate
Bulls this is an AI supercycle and Supply is limited by heads and media, not assembly lines. The two vertically integrated leaders (WDC and STX, ~90% share) are growing exabytes through areal density rather than units. The new pricing is being written into LTAs with escalators and renewals, and customers now plan storage five-plus years out alongside land, power and compute. Bulls argue this looks like a planned, multi-year infrastructure buildout, not the PC-driven cycles that earned HDDs single-digit multiples. They see Toshiba’s capacity ambitions as a prove-it story, given its reliance on third-party heads and media and its history of missed roadmap milestones.
This quarter fed every leg of that argument. Pricing accelerated to +28% with Dec-Q higher and largely locked, and mgmt sees 3-4 more quarters of expanding y/y gains. Pre-print Street CY27 models embedded only ~13-16% average $/TB growth. Every 5pts of CY27 pricing is worth roughly $1B of revenue that falls almost entirely to profit, or ~$2 of EPS.
GM is guided to 60.5%, and bulls see the mid-to-high 60s by CY28. 40TB ePMR and HAMR (priced at parity, with margins at least equal to ePMR) should lift EB growth from the 22% “floor” toward 30% while the industry adds no units. Opex is essentially fixed at ~$400M a quarter, so OM can head toward 60%. With 35-45% FCF margins and 85%+ returned, WDC would retire ~4-6% of its share count a year at today’s price. Bulls read the capex step-up as old news aimed at the real bottleneck (heads and media). Catalysts include STX’s upcoming print, HAMR qualification completions in CQ1’27, the Dec-Q pricing print and LTA renewals.
Bears see a classic commodity up-cycle dressed up as secular growth. $/TB is up 28% and heading toward the mid-30s in an industry where it historically fell 15-20% a year, and pricing like that invites a supply response:
Toshiba reportedly plans to double capacity, and has reportedly shown interest in TDK’s HDD head business, which would ease its component bottleneck.
STX is already growing EBs in the mid-30s on HAMR.
WDC itself is more than tripling capex and talking up accelerating EB supply growth toward 30%.
An exabyte from areal density is still an exabyte. If industry supply grows in the high 30s while demand compounds at the ~25%+ mgmt keeps citing, the shortage closes sometime in 2028. The LTAs bulls lean on won’t stop it. Mgmt conceded that the further out you go, the less volume and pricing is covered; out-year terms aren’t set, and purchase orders run only 4-5 quarters. The incremental demand supporting spot pricing comes from neoclouds and frontier labs, the part of the AI stack most exposed to the financing stress now hitting the complex. Hyperscale customers (cloud is 88% of revenue) have every incentive to second-source and push back at renewals once supply loosens.
The bull case assumes pricing stays strong after supply responds and that WDC closes its technology gap. This quarter cut against both:
EB growth was stuck at 22% for a second quarter.
Cost/TB declines slowed to ~4-5% as the ~2-year HAMR lag vs. STX shows up in the P&L.
HAMR volume still depends on qualifications that don’t finish until CQ1’27.
The promised acceleration means running two transitions at once while absorbing HAMR head throughput losses.
Mgmt’s own comment that pricing growth will “eventually slow down” after 3-4 quarters puts the second-derivative peak on the calendar for 2H CY27 although mgmt seemed to walk back the moderation comment in the call back.