

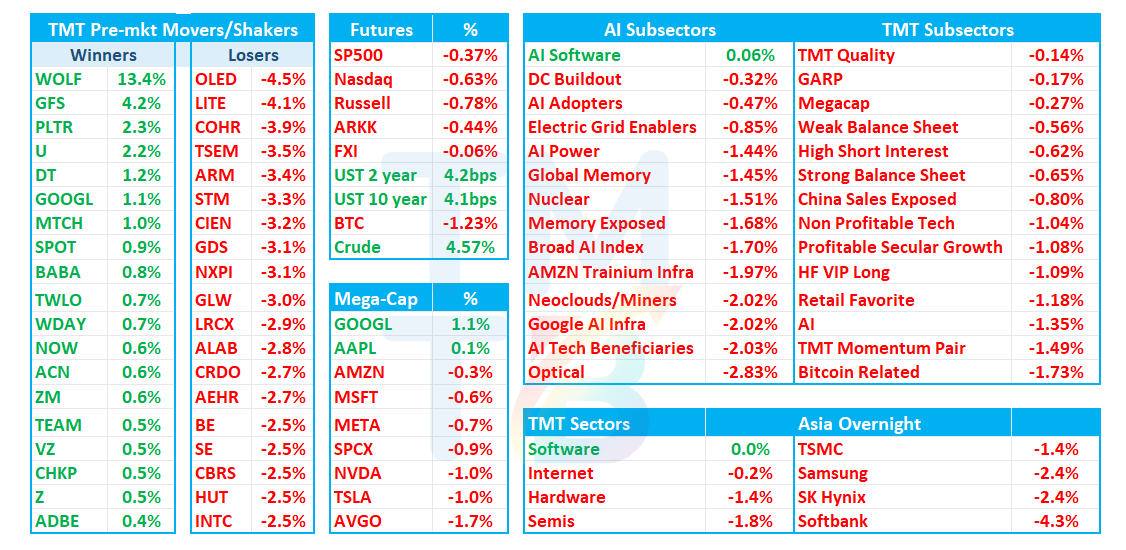
Good morning. QQQs -60bps lower as yields +4bps across the curve and Oil +5% following several Trump is considering air strikes headlines and an uptick in Hormuz commercial ship attacks.:
“Military ordered to be ready for possible Iran strikes as Trump weighs timing” (Axios), “U.S. military prepares new Iran war options ahead of midterm elections” (NBC News), and “Trump Is Considering a Plan to Strike Iran Before the Midterms” (The Atlantic) (h/t VK)
In Tech, focus on Samsung which finished -2% overnight after results that looked light of street, but a bit better than bogeys that had moved lower over the past couple of weeks. GOOGL +1% after announcing Gemini enterprise agents. TSM -1% after solid Sept numbers. U +2% after an RJ upgrade a few other positive sell-side notes.
Overnight, Asia generally weaker: TPX -1.51%, NKY -1.42%, Hang Seng -1.43%, HSCEI -0.89%, SHCOMP -0.79%, Shenzhen -1.63%, Taiwan TAIEX -0.99%, Korea KOSPI -2.62%. Softbank -4%. Samsung/Hynix -2.5%
Let’s get to it…
PLTR: GS upgrades to Buy/$230, sees another estimate-revision cycle as AI TAM expands
GS says PLTR is set for another phase of outperformance into 2027, with sovereign AI, bespoke apps and verticalization potentially driving another step-function increase in TAM. It also sees the FDE model as a durable moat, built on tight field/product feedback loops and increasingly automated via AI FDEs. With shares +16% YTD vs. NDX +24% and at a discount to growth comps on EV/FCF, GS upgrades Neutral to Buy with a $230 PT.
U: Raymond James upgrades to Outperform/$54 as Google partnership strengthens Create/Vector flywheel
Raymond James says Google’s AI + distribution closes a key gap in Unity’s creator ecosystem, bringing the engine to non-coders and potentially driving more content, runtime data and engagement into Vector. Vector has already materially outperformed, growing 23% q/q in 2Q vs. initial 12–13% expectations, with Strategic Grow +63% y/y and 3Q growth guided to 68–70%; RJ sees this supporting durable share gains and margin expansion. It upgrades U to Outperform/$54, valuing shares at 9x 2027E revenue of $2.55B vs. ~7.5x currently and APP at ~8.9x.
NBIS: Rosenblatt initiates Buy/$304, sees ~98% revenue CAGR through 2030 as #2 neocloud scales
Rosenblatt sees NBIS just behind CRWV among neoclouds, with ~250MW active power today and 3.5GW contracted, ~75% expected from fully owned sites. Revenue grew 5.5x y/y in 2Q26 and is expected to grow 6.5x in 2026, supporting a ~98% FY26–30 CAGR. Rosenblatt expects additional debt/equity funding despite customer prepayments, following August’s $5.75B convert, and initiates Buy/$304.
GOOGL: Google Cloud introduces Gemini Agent, a universal enterprise AI agent that autonomously plans and executes tasks across research, content creation, coding and business workflows using organizational context and integrated tools.
Automatically selects models, connects to enterprise systems and includes cost controls, security and centralized governance. Strengthens Google's push into enterprise AI automation, potentially driving Cloud adoption, customer retention and revenue growth.
Reminder GOOGL CLoud CEO Thomas Kurian Keynote at 1:30pm ET.
TSM: Sept Revenue -0.6% MoM, +54.6% YoY
Avg Sept seasonality roughly flat m/m (so roughly in inline ex currency). Q3 came in at about US$46.7B, roughly 2% above the top of the guide and 3.3% above the midpoint.

Samsung / Memory: Samsung’s preliminary Q3 operating profit reached KRW107.4T ($80.2B), versus LSEG’s KRW106.1T estimate. This was above buyside bogeys which had moved down to KRW105-106T. Implies 55% OM vs street at 53.8%
AVGO / ORCL / SPCX: AI chip financing expands with $50B-plus OpenAI deal – WSJ
WSJ reports Broadcom is discussing more than $50B of financing for OpenAI’s custom-chip program, starting with Jalapeño, with Apollo, Blackstone and other lenders. The deal could cover several gigawatts and close by year-end. Oracle is separately talking to Apollo and Goldman Sachs about financing chip purchases through a vehicle that would own the hardware and lease it back. WSJ also reports SpaceX’s $40B Nvidia-chip financing talks, first reported by FT on Tuesday.
META


The chart has four distinct phases of DAU growth (reminder no international launch yet):
Launch week: Slow, averaging about +28K a day, and stalled around 220–240K from 9/12 to 9/15.
Inflection (9/17–9/24): Adds jumped to about +145K a day, roughly 1.2M new DAUs in eight days.
Dip and rebound: After one down day on 9/25, growth returned to about +145K a day from 9/27 to 9/30.
Since 10/1: Growth has slowed to about +45K a day, or 0–4% daily, though 10/4–10/5 picked back up to +80–90K.
