

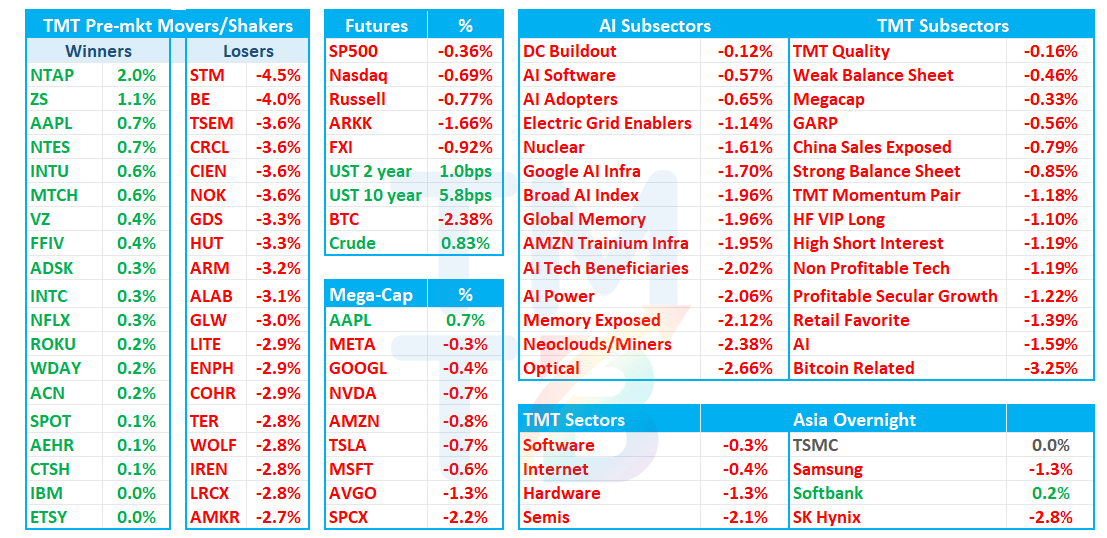
Good morning. QQQs -75bps / SPY -40bps as higher yields weighing this morning: 10year +6.5bps to 5.35% and 30year +6bps to 5.7% as European yields also up after sliding yesterday. Oil +1% on reports Iran has been increasing attacks in Hormuz
In Tech, Semis -2% leading the way lower with many names down 2-4% across the board. Software/Internet -30bps hanging in better. Not many names up this morning on what’s a fairly slow research/news day.
Stocks in Asia mostly red overnight: TPX -0.7%, NKY -0.92%, Hang Seng -0.62%, HSCEI -0.57%, Taiwan TAIEX -0.03%, Korea KOSPI -1.98%
Let’s get to it….
SPCX / NVDA: SpaceX seeks $40B to buy chips led by Apollo – FT
FT reports SpaceX is seeking approximately $10B in bank loans and $30B in investment-grade debt to purchase Nvidia chips, with Apollo expected to lead the financing and Pimco among the lenders in talks. The transaction is expected to close in 2027. SpaceX’s BBB rating opens the deal to insurance and pension investors, although its existing 2056 bonds trade around 85 cents on the dollar amid concerns over debt and capital spending.
MRVL: TD Cowen upgrades to Buy/$350 as connectivity replaces custom XPU as core growth driver
TD Cowen says MRVL’s risk profile has materially improved as growth shifts toward its connectivity franchise and away from concentrated custom XPU exposure; only ~$15B of the ~$80B CY30 revenue midpoint is now expected from custom accelerators, with XPU just ~19% of revenue vs. >40% previously feared. Management targets ~$38B interconnect, ~$10B switching/storage and ~$30B custom by CY30, with FY28 revenue already expected near ~$20B, ~$18B from datacenter. Cowen sees >$30 EPS within three years, upgrades to Buy from Hold and raises PT to $350 from $245.
NTAP: Evercore upgrades to OP/$300, sees conservative FY27 guide + AI/storage driving durable growth
Evercore says NTAP’s ~17% FY27 growth guide embeds an overly sharp H2 slowdown, with normal seasonality supporting low-20s growth and ~$11 EPS vs. Street ~$10. Longer term, AI/storage expansion, Novus/AIDE and operating leverage support a path toward ~$15+ EPS, while high-60s GMs and >32% FY27 EBIT margins look sustainable despite NAND pressure. Upgrades from In Line and raises PT to $300 from $210.
MSFT: Evercore ISI raises PT to $635 from $528, sees 30.5GW FY30 capacity with bull case to $880
Evercore ISI models MSFT datacenter capacity rising from ~12GW exiting FY26 to ~30.5GW by FY30, with ~10.3GW of revenue-generating GPU capacity and Azure AI revenue/GW rising from ~$20B today to ~$27.5B. That supports ~$389B of FY30 Azure revenue (~40% CAGR, ~66% AI mix); the bull case reaches ~34GW, ~$447B Azure revenue (+14% vs. Street), ~$40.42 EPS (+16%) and ~$880/share. ISI sees upside from faster dock-to-live, OpenAI/always-on agent demand and better monetization, while its base case supports the new $635 PT
MSFT: JPM CSP partner sees Copilot penetration ~7x by FY-end, Fabric driving ~5x pull-through
JPM says a large distributor/MSFT CSP expects Copilot penetration ~7x by FY-end as relaunch/free trials reduce friction, with Cowork/Code adding consumption rather than displacing frontier models. Renewal recapture is ~130–140% vs. ~125% baseline, E7 is accelerating upgrades, and Azure has no capacity constraints; Fabric is growing >200% y/y and drives ~$5 of incremental account spend per $1, supporting faster 2027 IT budgets.
SPCX/Terafab: Musk says TSM won’t run Terafab
