

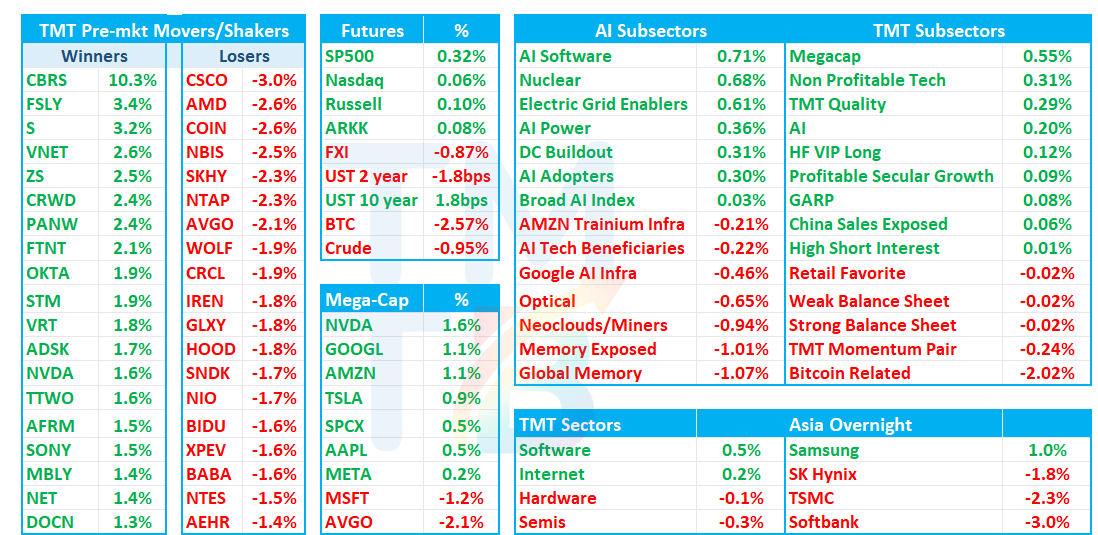
Good morning. Futures a touch in the green with QQQs +10bps / SPX +30bps. Yields flattish while Oil -1%
In Tech, a nice fairly quiet morning (so far…). Semis slightly weaker while software is up. Cyber stocks rallying on the MSFT -1% outrage; NVDA +1.6% continuing its post-Jensen resignation bounce as the headline gave an easy out for shorts to cover; GOOGL/AMZN +1% continuing from yesterday; TTWO +1.5% on a positive barrons mention; CBRS +10% on mixed results but some better commentary around OAI; AMAT flat on fairly in line numbers; CSCO -3% after missing product orders despite a headline beat and raise.
Asia mixed overnight: TPX +0.11%, NKY +0.53%, Hang Seng -1.55%, HSCEI -1.48%, SHCOMP -0.59%, Shenzhen -2.11%, Taiwan TAIEX +1.35%, Korea KOSPI -0.98%,
We’ll hit CSCO AMAT and CBRS EPS then the usual…
Let’s get to it…
CSCO -3%: FY27 raise and $9B AI guide clear the bogeys, but orders slow to +21% (vs. low-30s bogey) and mgmt stopped quantifying hyperscale orders
Stock initially popped 10% last night on the beat and raise but faded as investors realized mgmt didn’t release the orders number in the release like they usually do and there was a reason why: only 21% vs bogeys of low 30s.
Despite the big headline numbers, product orders slowed to +21% from +35% (ex-hyperscale +14% from +25%), and mgmt stopped quantifying hyperscale orders. Robbins only said hyperscale orders grew nicely y/y vs. “$1 billion and some change” a year ago. Rough math (total +21% vs. ex-hyperscale +14%, on a ~$1.3B year-ago base) implies ~$2.2–2.4B, vs. $4B in FQ4 (down ~40%+ q/q). The guide also implies 2H GM steps down to ~64–64.5%. Mgmt’s message is a multi-year supercycle with five drivers, a campus refresh <10% through, and early post-Mythos security orders.
Bulls will point to a 4th straight acceleration (+24.4% y/y on a flat comp; Networking +43%), a record 37.8% OM, an F2Q GM guide ~110bps above Street’s 64.4% (August’s was ~87bps under) and an implied 2H of ~$38.7B vs. Street’s $37.03B.
Bears will lean on slower product orders and weaker implied hyperscaler orders, , F1Q GM missing the bogeys with product GM down 355bps y/y to 63.7%, and an F2Q guide of -2.3% q/q at the mid vs. +3.1% and +1.1% in the last two Jan quarters.
Details:
F1Q revenue of $18.52B (+24.4% y/y, CSCO’s strongest revenue growth “in over 15 years”) beat Street ($18.07B) and the ~$18.3-18.45B bogeys, a 2.3% beat on the guide mid (2.7% in F4Q) and a 5th straight quarter above the top. GM of 65.6% was in line with Street (65.6%) and missed the ~65.8-66% bogeys, but OM hit a record 37.8% (Street 36.2%) and EPS of $1.40 beat Street ($1.32) and the ~$1.35-1.37 bogeys.
The F2Q revenue guide of $18.0-18.2B (mid $18.1B, +17.9% y/y) beat Street ($17.80B) and was in line with the ~$18.0-18.3B mid bogeys; GM of 65-66% beat Street (64.4%) and the ~64.5-65% mid bogeys; EPS of $1.34-1.36 ($1.35 mid; implied OI ~$6.61B vs. Street $6.18B) beat Street ($1.23)
FY27 revenue guide went to $74.8-75.8B (mid $75.3B, +$2.5B), beating Street ($72.92B) and the ~$73.2-73.7B mid bogeys, and EPS to $5.47-5.53 ($5.50 mid), beating Street ($5.10) and the ~$5.14-5.20 mid bogeys, and the FY27 hyperscale AI revenue view went to $9B and beat the ~$8.0-8.5B bogeys. Key for call will be product orders, which weren’t in the release (~31-35% bogeys; +35% in F4Q).