

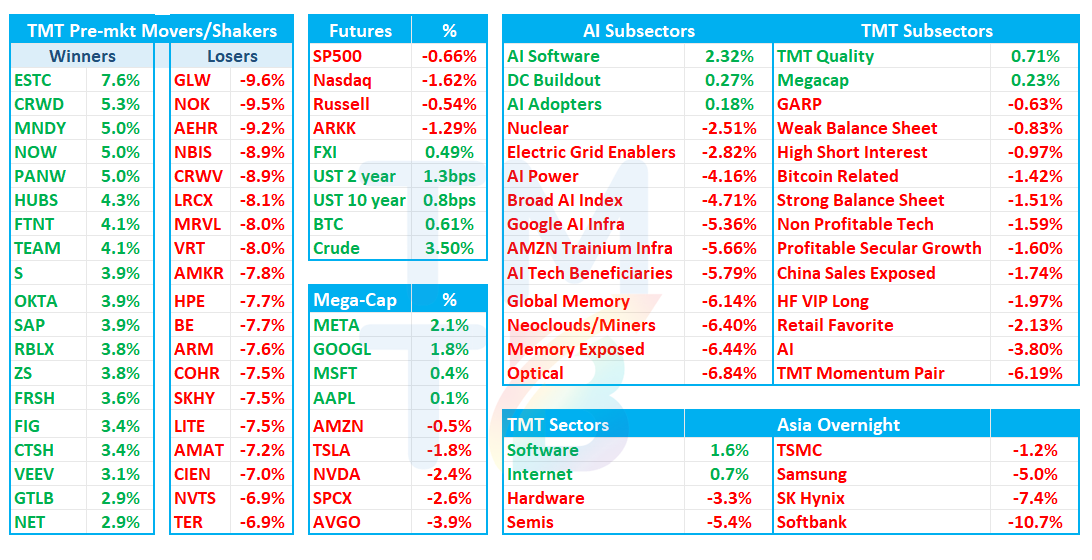
Good morning. QQQs - 1.5% (SPY -60bps) led lower by Semis -5.5% after a weekend where AI Safety dominated the headlines with Dario’s call to “pace the frontier” which was then supported by Atlman & Musk. No AI sector spared so far with Neoclouds -7%; Optical -7%; Memory -6%, etc. Overnight, Asia weaker with KOSPI -3%, Softbank -11% the big loser and Hynix -7% / Samsung -5%. TMT Momentum -6%.
Software +1.5% the main beneficiary of the talk so far on rotation and as a “potentially” slower frontier takes some urgency out of the SaaS-disruption bear case. Cyber +4% strongest sector. Internet +50bps also up led by META/GOOGL +2%
If you need to catch on what happened over the weekend, we thought Gavin Baker had a good rundown of the facts

Sam out with a post last night: When we talk about “pacing”, we do not mean “stopping”. Progress has been rapid and will continue to be. But it should be slower than it otherwise could be; interventions like safety cases and monitoring have significant costs.

MSFT CEO Nadella also weighed in:

Trump:
We're leading China in AI. And frankly, I want to keep it that way.
And we can put guardrails, we can do this and that, but I think you have a lot of negative forces… bringing up things that won't happen.
But whoever wins with AI wins. It's an expression that I came up with. It's true.
In Macro land, Oil +3.5% on more Middle East turbulence: ongoing Hormuz turmoil; Houthi territorial conquests in Yeme; and shuttering of the Saudi East-West Pipeline. Yields up 1-2bps across the curve ahead of the Fed meeting on Wed, where market is pricing in 92% chance of a 25bps increase.
Lots to get to, so lets get to it…
HPE: Evercore ISI downgrades to In Line after +192% post-Juniper rerating, says next leg needs margin proof
Evercore ISI says HPE has executed well but valuation now fairly reflects the Juniper upside, with shares at ~13x FY27 FCF and fewer near-term catalysts to drive further multiple expansion; PT stays $65. ISI sees FY27 revenue growth of +13–17% and EPS growth of +16–20%, but says the debate now shifts to Juniper integration, Networking margins and mix quality, with Networking margins still below historical Juniper levels. ISI views AMD Helios as an additional Cloud & AI tailwind, but likely not material until late FY27/FY28.