

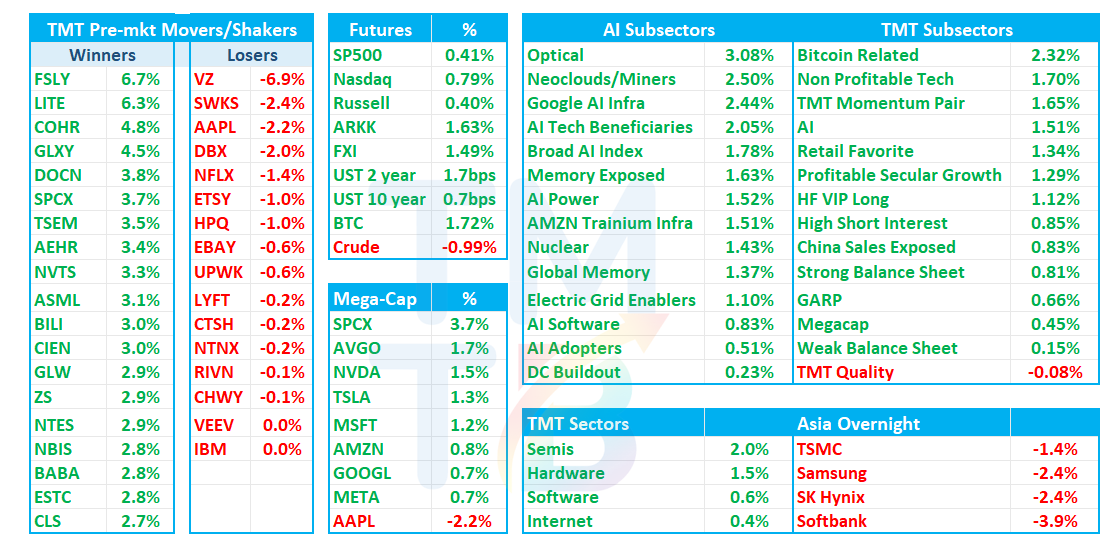
Good morning. QQQs +75bps bouncing back with semis +2% leading the way higher as investors woke up with cooler this morning after OpenAI saying they expect revs to reach $70B by end of year 2026. Yields +1-2bps across the curve, Crude -1%, and BTC +2%
In Tech, SPCX +4% after co announced it acquired low band spectrum, opening up the doorway for it to become a major mobile carrier in the US. The news is hitting telcos and has Towers trading higher. FSLY +6% after an Oppenheimer upgrade. LITE +6% after CEO made comments to Bloomberg that they were sold out through 2029. Bunch of semis up 2-3%+. RDDT +2.5% as various sell-side out saying with DAUs and Ads trending better against low buyside user expects. AAPL -2% as Nikkei Asia saying AAPL cutting iPhone 18 Pro orders on weak demand.
Overnight, Korea and Taiwan were closed for holiday with Japan closed Monday.
OpenAI: Targets $70B-plus year-end revenue run rate, versus $50B in September – Bloomberg
Bloomberg reports OpenAI expects net annualized revenue of at least $70B by year-end, versus roughly $50B at end-September, driven mainly by enterprise growth. It shared the figures in talks to raise $30B or more at a $1.4T pre-money valuation. Earlier $70B estimates reflected investor adjustments for cloud-partner revenue accounting differences versus Anthropic, according to FT.
SPCX / T / VZ / TMUS: SpaceX buys nationwide spectrum for Starlink Mobile expansion – Reuters
Reuters reports SpaceX agreed to acquire Grain Management’s nationwide 800 MHz spectrum portfolio, with WSJ putting the price at about $8B in cash. The spectrum would improve indoor coverage for Starlink Mobile; the purchase still needs FCC approval. Separately, the FCC authorized 15,000 mobile-connectivity satellites. AT&T, Verizon and T-Mobile shares fell roughly 6% in extended trading.

SPCX: JPM says 800 MHz spectrum buy makes Starlink Mobile more credible, but near-term telco risk limited
JPM says acquiring Grain’s nationwide 800 MHz spectrum gives SpaceX a valuable low-band coverage layer with better in-building propagation, strengthening the case that Starlink Mobile ambitions extend beyond handsets. Without an MVNO deal, SpaceX would still need to build a terrestrial macro network to match incumbent wireless quality, requiring significant time/capital; JPM therefore sees limited near-term risk to TMUS/VZ/T despite the stocks selling off. Reiterates OW on SPCX.
SPCX: RBC says low-band spectrum fills key technical gap in path to becoming major U.S. carrier
RBC says acquiring up to 14MHz of nationwide 800MHz spectrum adds critical indoor/obstacle coverage to Starlink Mobile’s existing 2GHz mid-band, enabling a more complete satellite + terrestrial wireless architecture. Combined with FCC approval for 15K Gen2 satellites and Musk’s stated ambition to compete directly with major carriers, RBC sees the deal as strategically important and positive for SPCX. Reiterates OP/$225, with Starship still the major technical hurdle.
SPCX/Towers: Sell-side says Grain spectrum deal is clean positive for AMT/CCI/SBAC; fourth-carrier build getting more credible
RJ/BMO see SpaceX’s 13.5MHz 800MHz purchase as the clearest tower catalyst in years, with no terrestrial build currently in Street models; every 1,000 SPCX towers could add ~$24M of annual sector revenue, while DISH’s ~24K-site footprint could become relevant if SPCX buys assets out of bankruptcy. SpaceX now has ~79MHz of spectrum and could spend another ~$30B, with meaningful commercialization starting ~2029–30; carriers T/VZ/TMUS are the negative derivative, though Citi sees limited operating impact before 2029.
RDDT/Digital Ads: Piper sees solid RDDT 3Q users, accelerating META CPMs + stronger GOOGL AI citations
Piper says after adjusting for Reddit Ads Manager’s methodology reset, RDDT 3Q users grew +5.6% q/q, including U.S. +3.1% vs. Street +0.8% and buyside expectations for flat/down DAUs. META CPM growth accelerated to +47% in September from +33% in August, while GOOGL’s share of AI Mode/Overview citations rose to 21.4%, +290bps m/m/+540bps since April. Ad checks remain strong into 4Q, with NFLX/ROKU/YouTube/RDDT standouts and TTD/SNAP weakest
RDDT: Jefferies expert calls show continued share gains, stronger pricing + promising Max performance
Jefferies says digital ad spend remains healthy at ~10% growth, while RDDT continues to gain wallet share ~20–25% annually and is increasingly viewed as a full-funnel platform, with AI-search visibility an added tailwind. RDDT now captures ~60–70% of spend among smaller platforms at one agency, pricing is no longer at a material discount, and early Max tests show ~15–20% lower CPA; LLM ads remain underwhelming on lower-funnel performance/measurement.
RDDT: Needham traffic tracker points to 3Q user/revenue upside, raises estimates
Needham says RDDT app downloads accelerated +19% q/q in 3Q while web visitors grew +2–3%, with U.S. strength continuing and international users trending higher since April. The data suggests both user and revenue growth could beat 3Q Street expectations; Needham raises estimates and reiterates Buy/$300