

Good afternoon. QQQs -1.3% and Semis -3.4% were already soft on oil and yields when the FT’s 12:45pm headline that OpenAI’s annualized revenue is ~$20B below what had been signaled took SOX from about -1.7% to -3.4% in fifteen minutes; and it never really recovered (-4.6% at the lows). Turns out the biggest risk to the AI trade isn’t power, open source, financing or the Dems winning in November. It’s actually GAAP.
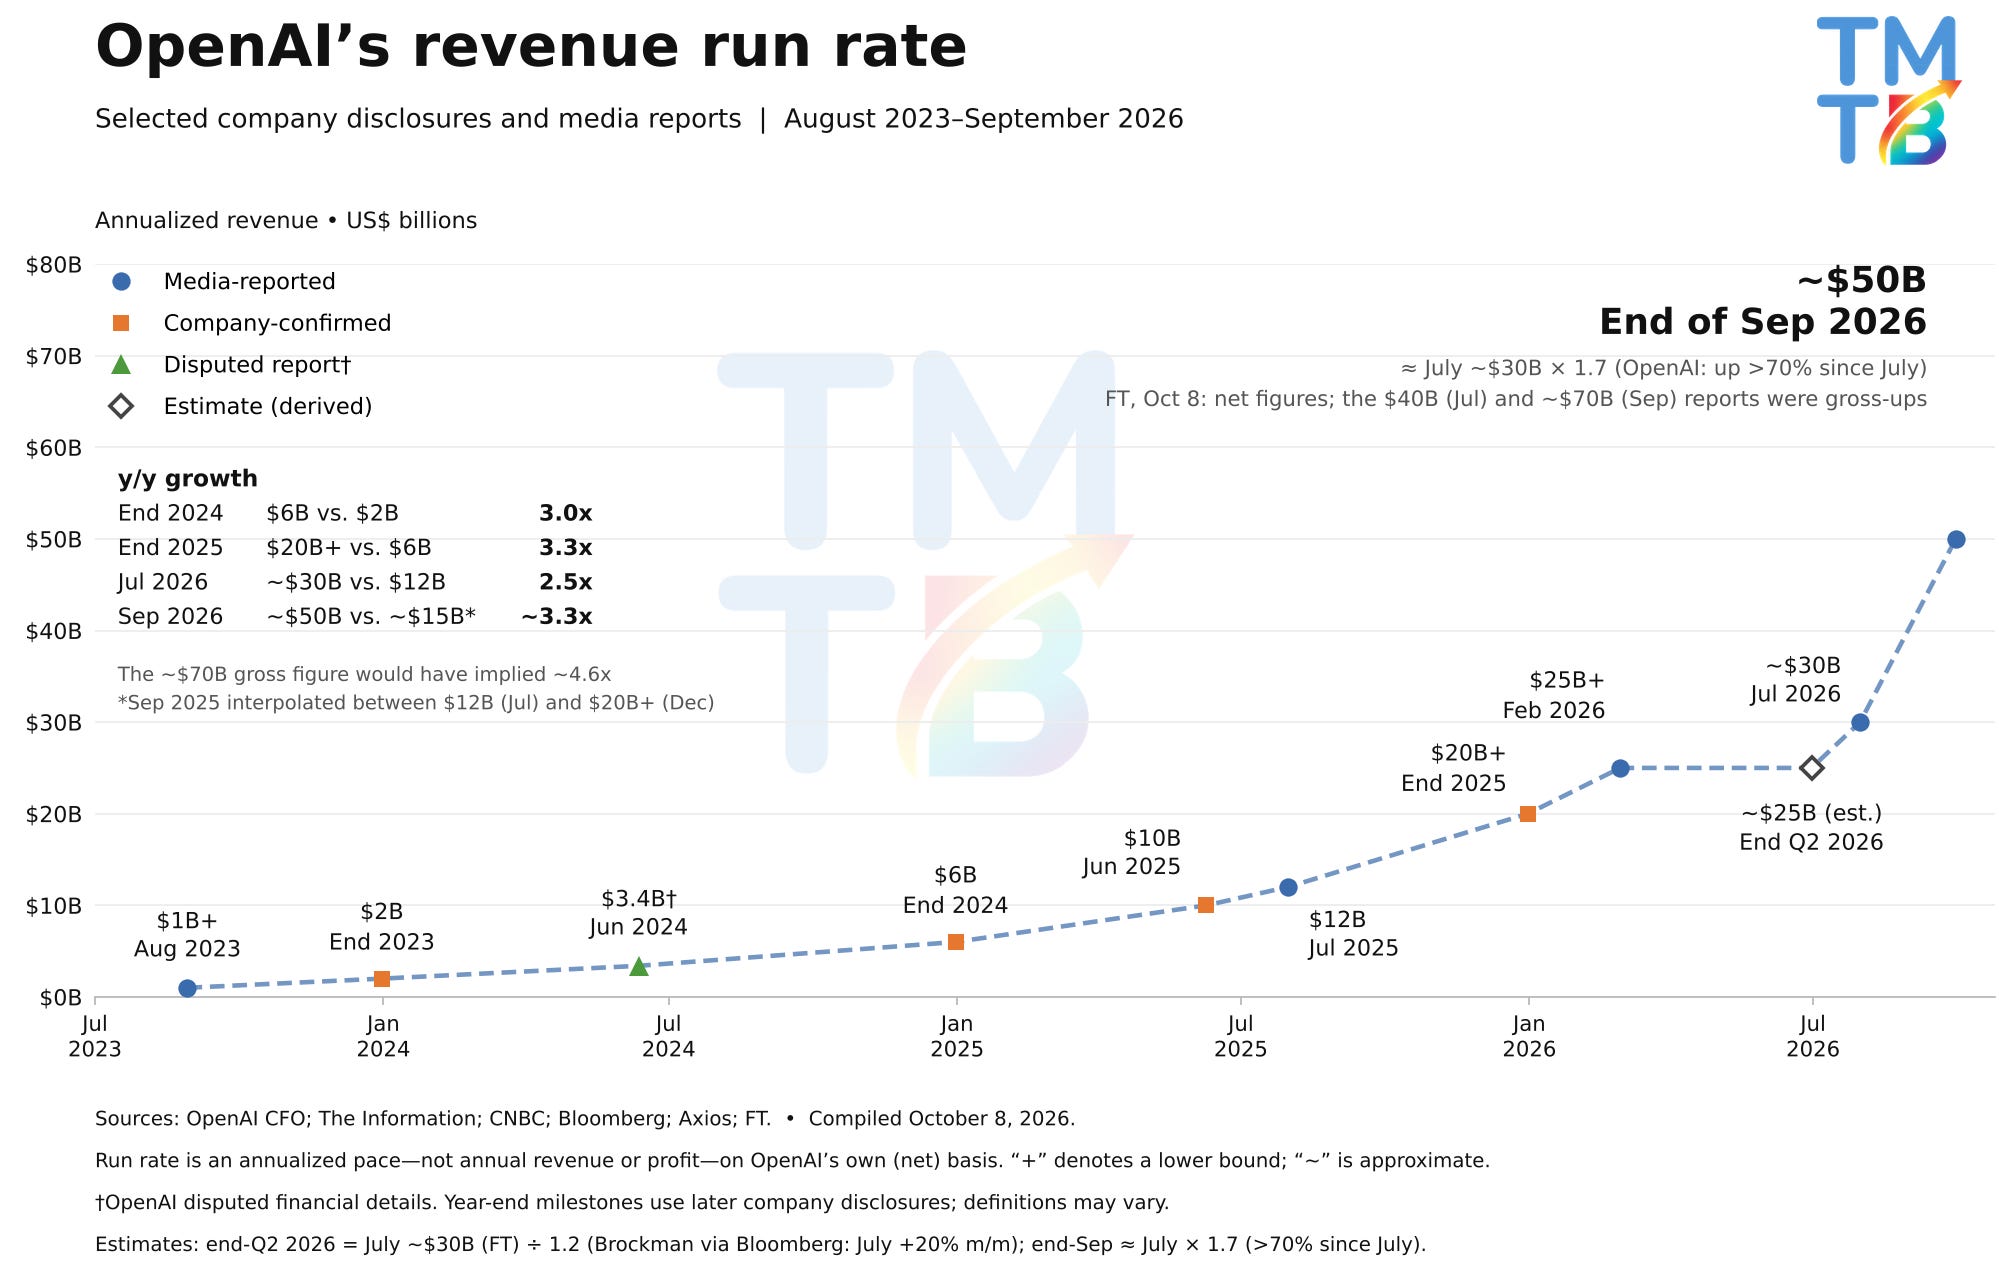
OpenAI’s ~$50B September ARR vs the previously reported ~$70B is the difference between gross and net so the headline was misleading (recall: OAI has to share 20% with MSFT and has the Bedrock deal as well).
Key quote from FT article: "According to a person with knowledge of the matter, the discrepancy arose from attempts by OpenAI’s own investors to produce a direct comparison with Anthropic’s annualised revenues. The pair calculate the figure in different ways, with Anthropic including the revenue from sales via cloud partners such as AWS and Google Cloud, while OpenAI does not.”
Last week we got a $70B figure from Axios which catalyzed enthusiasm among the AI bulls. But the actual progression from Q2 to Q3 seems to be ~$30B → ~$50B, not ~$40B → ~$70B, roughly the same 70% growth rate but off of different numbers.

Here’s my best attempt at how things look and what the numbers we have heard imply:
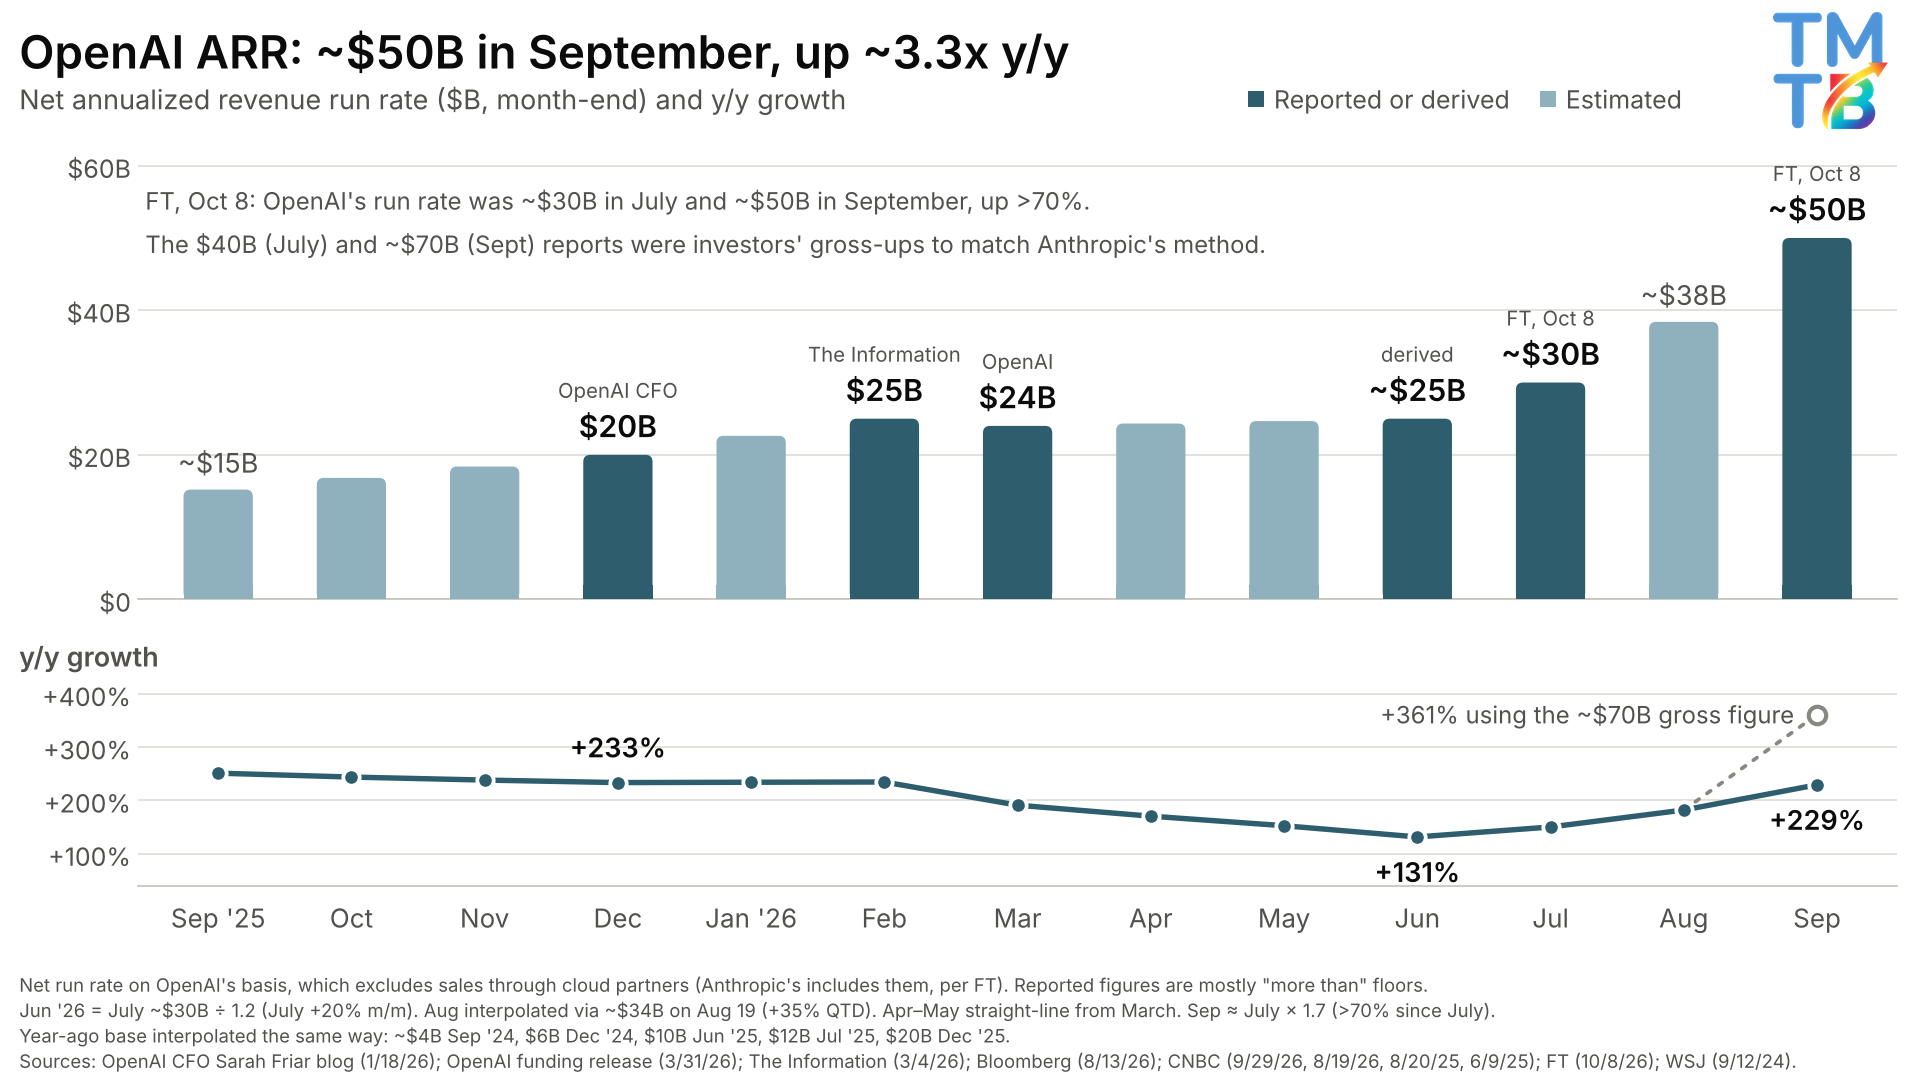
Glass half empty: People had thought $70B was net and the perceived dollar base just reset ~25–30% lower. OpenAI added ~$20B of ARR over August and September, not ~$30B. The first half was also weaker than people thought. The net run rate sat at ~$24–25B from February through June, and y/y growth slid to ~130% y/y by June, a big decel from Dec 2025. That’s a lower starting point for YE26/YE27 net ARR targets & for valuation, and for the math on funding OAI’s compute commitments.
Glass half full: The growth rate hasn’t changed. $30B → $50B net is the same ~70% in two months as $40B → $70B gross, and the monthly additions picked up into September. The y/y line bottoms at +131% in June, then climbs to +150% in July, +182% in August and +229% (~3.3x) in September. Had July really been $40B, September’s $50B would have meant y/y growth flat at ~230%. On the net base, it’s actually sharp re-acceleration of ~100% y/y in 4 months. Against Anthropic nothing changes, because the ~$70B gross figure is still the like-for-like comparison.
We had a fun day in TMTB Slack and set a record for most comments in a thread here

Favorite comment in the thread:

Moving on…
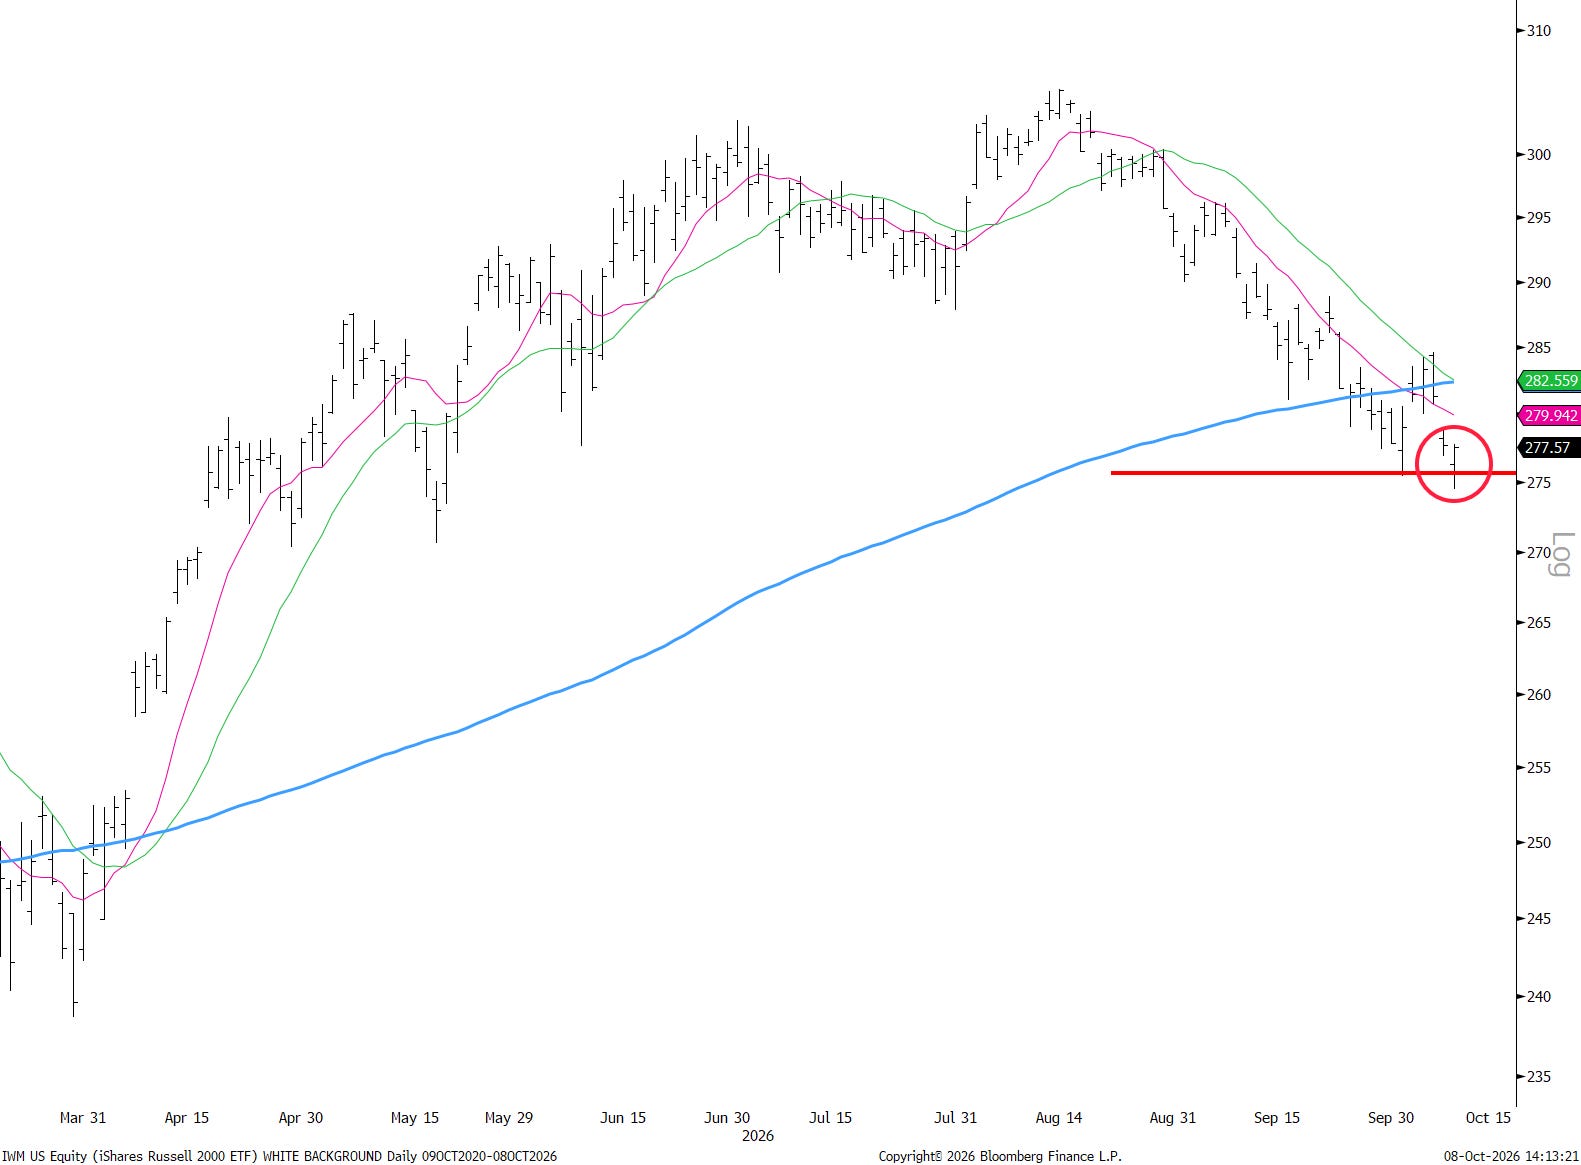
Software -23bps held in and IWM flat finished well off its -1% morning lows as the long end rallied. Chart here looks interesting with IWM breaking its low but finishing above it, a false breakdown that can typically presage further strength
It was a rotation out of anything with AI-capex or AI-financing beta: neoclouds and miners, already sliding on Firmus’ IPO stumble (HUT -11%; CRWV -8%; NBIS -7.4%; IREN -7.7%), optics and AI networking (COHR -9.6%; ALAB -9%; GLW -6.4%; LITE -5.6%), AI power (BE -6.3%; VST -6.3%) and the OpenAI counterparties (ORCL -5.6%; AVGO -4.3%; NVDA -3%) led the way lower. The other side of the trade was another squeeze in the AI-loser baskets: IT services (ACN +6%; CTSH +5%), the Muse-disintermediation names (Z +7%; EXPE +4.4%; ETSY +5%; EBAY +4%) and seat-based software (HUBS +5.3%; MNDY +6.5%; FIG +4.7%). AAPL +1% was the only green megacap ahead of Tuesday’s smart-home event.
Couple charts worth flagging in semis…