

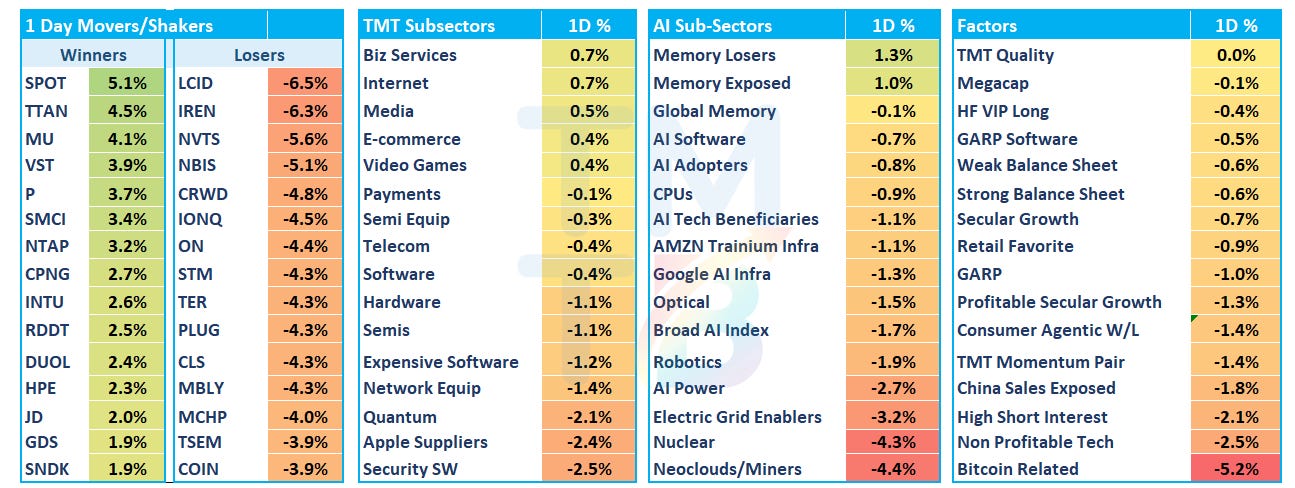
Good afternoon. QQQs -25bps, well off the -1% morning lows, but underneath was uglier than the index with a lot more red than green on my screen. Semis -1.1% and software -1.2% underperformed while internet +70bps was green. Overall didn’t hear any panic or shifting narratives from investors today — seemed more like a digestion/rotation day.
In semis, analog/auto was the worst of it on no news (MCHP -4%; STM -4.3%; ON -4.4%; NXPI -4%), semicap stayed soft (TER -4.3%; LRCX -1.3%; AMAT -1.8%) and neoclouds fell, led by IREN after SemiAnalysis aired customer complaints about its BC sites (IREN -6%; NBIS -5%; CRWV -3.6%); in software, cyber gave back some of its run (CRWD -4.8%; PANW -3.4%; NET -3.5%).
The green was in memory as rotation with AI semis continues, which ripped off the strike-headline lows (MU +4%; SNDK +2%), AI hardware/storage catching another bid on Evercore’s NTAP upgrade (DELL +1%; NTAP +3%; P +5%; HPE +2%) as on-prem remains one of the strongest sectors with AI, and beaten-up internet (SPOT +5.1%; CPNG +2.7%; RDDT +2.5%; DUOL +2.4%) got a bid. Among megacaps, META -2.4% lagged while AMZN +1.4% was green for a second straight day, which these days counts as news.
In macro land, investors continue to focus on the long-end. The 10Y pushed to ~5.35% this morning, a 24-year high, before a strong 10Y reopening at 1pm pulled it back to finish +1bp to 5.28%. The September FOMC minutes at 2pm had “most participants” seeing another hike as likely appropriate by year-end, also saying “some” worried the “AI buildout could cause aggregate demand to outpace aggregate supply.” Futures still put ~20% odds on a 10/28 hike, in line with Tuesday and down from 70%+ early last week. WTI traded around $90, up ~1% early as tanker attacks in Hormuz hit their highest weekly count of the war, and BTC -3% to ~$83K after a late-night flash selloff. HYG flat put in a nice green candle off the lows.
Let’s get to the good stuff…
AI/SEMIS
MU +4.1%; SNDK +1.9% reversed hard from the opening lows (MU was -3.3%) as Reuters reported MU’s Taoyuan union won strike authorization with 99% of ballots, and Korean media reported Samsung’s 12-high HBM4E passed qualification at NVDA and other customers
 Jukan ✈️OCP 2026@jukan05SOUTH KOREAN MEDIA: SAMSUNG’S 12-HIGH HBM4E PASSES QUALIFICATION TESTS AT NVIDIA AND OTHER CUSTOMERShankyung.com[단독] 삼성 'HBM4E', 엔비디아 문턱 넘었다…주요 고객사 품질테스트 통과8:13 AM · Oct 7, 2026 · 28.2K Views12 Replies · 32 Reposts · 238 Likes
Commercial Times says the union escalates if MU’s 10/8-9 board meeting brings nothing (it wants 15% of operating profit shared). Remember: unlike other industries, strikes tend to be viewed as positive for memory stocks as read-through is supply disruption... DA Davidson was out slapping a street-high $3k target on MU (2nd highest is ~$2k) after meeting with IR saying investors still underappreciate how AI models require more memory for performance, speed and context, with demand expected to outstrip supply through 2027–28. One interesting datapoint we heard last week post earnings was that MU mgmt was saying on callbacks that their new LTA’s don’t cap pricing and that agreements signed in Q3 carry higher price bands than 1H deals. Last night, Nanya told customers some DRAM contract prices are going up as much as 20%. DRAM pricing continues to be more firm than NAND recently, which is why MU has been o/p’ing SNDK a bit recently. MU chart looking better as despite all the frustration from memory investors, we’re only 10% off ATHs. I get the question a lot when memory will get its groove back — we have no crystal ball so let the chart guide us. MU popping from below to above ST MA’s a good start today. We get Samsung’s Q3 prelims tomorrow. SKHY -2.4% lagged as the lockup on its US-listed shares expired today.
WDC -1.4% lagged again while STX +24bps steadied after Tuesday’s TDK selloff.


MCHP -4%; STM -4.3%; ON -4.4%; NXPI -3.8%; TXN -2.8%; ADI -2.5%: the selling started in Europe, with STM -4.1% overnight. GS reiterated Buy on MCHP Tuesday arguing the analog recovery is undervalued, and Stifel said the industrial/auto inventory correction is done in raising its ON target. Positioning has cooled significantly on analogs since a very hot in June when everyone was looking for the next AI-related subsector of semis.