

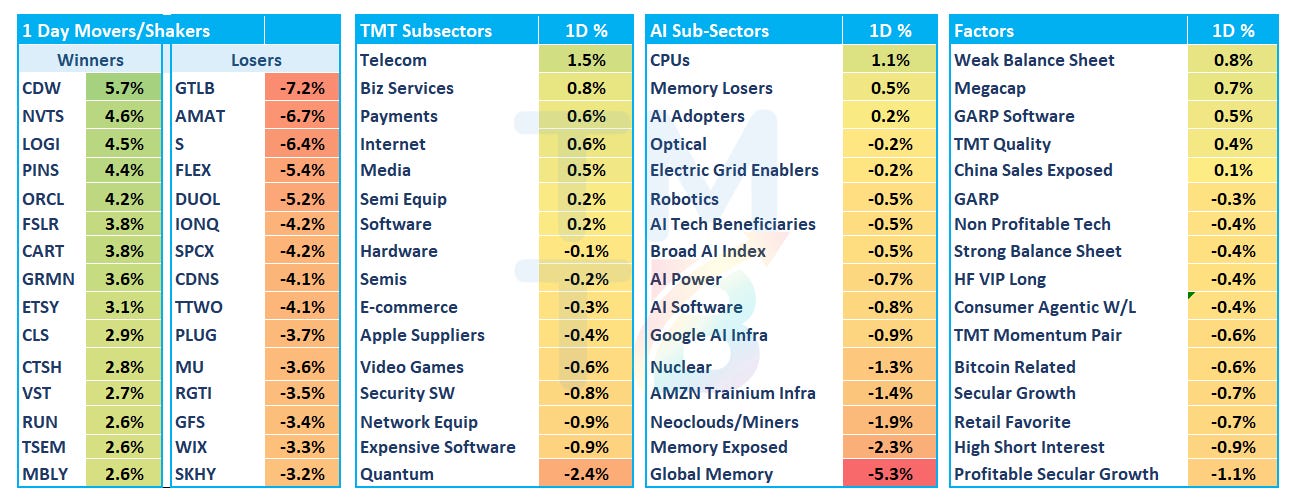
Good afternoon. QQQs -33bps were down ~90bps at the open after another Korean memory rout overnight (KOSPI -5.5%, Hynix -10%; Samsung -8%), then spent the day grinding back, with semis finishing close to flat nearly erasing a -3.3% drop by the bell while software -27bps gave back a +1.4% morning pop. Memory was the weak spot again on more CXMT headlines but finished well off the lows (MU -3.6%; SKHY -3%; WDC -1.6%; SNDK -34bps), and semicap lagged (AMAT -6.7%; LRCX -2.7%; ASML -2%) after AMAT’s investor day served up 2030 margin targets but no WFE number. On the other side of the rotation, PC/IT hardware (CDW +5.7%; LOGI +4.5%; HPQ +2.5%) and IT services (CTSH +3%; IBM +1.7%) caught a bid on no news, META +2.6% kept going after Muse Wonder, and ORCL +4.3% reversed a -1.3% open.
All eyes on tomorrow’s Anthropic investor meeting, with the ASML print and CPI playing second fiddle.
We’re settling around a $78–80B September ARR bogey versus $65B at July-end based on our polling and conversations, though there’s plenty of debate in both directions. Bears see $80B as a stretch given potential headwinds from META/MSFT curtailing usage, OpenAI share gains and tighter anti-distillation measures. Bulls counter that roughly $79B would put Anthropic on a straight-line path from July’s $65B to its $100B year-end target.
Broadly speaking, the fixation on ARR over the past two weeks has put a spotlight how much of the broader AI trade is perceived to hinge on the revenue trajectories of just two private labs whose financials remain largely opaque. At this point, investors seem tired of trading competing whispers and want the number out of the way, alongside more transparency on the financials. Better disclosure won’t necessarily make the story more bullish, but it should reduce the uncertainty investors are being asked to underwrite (knowledge is vol reducing after all).
Does a beat clear the deck? Does a miss trigger a swoon? Either likely drives a sharp short-term move, but we think the September number’s importance is overstated. Absent a major surprise, a few billion either side of the bogey won’t settle the broader semi debate around the frontier vs. open source transition (and other debates we talked about in yesterday’s wrap), but a good print would still be welcomed for sentiment by bulls after the last week.
The other thing to remember is that consensus already assumes Anthropic ARR has reaccelerated since early October following the Opus 5.5/Sonnet 5.5 launches, which means September is stale. More important will be whether management confirms that acceleration and what it implies for the year-end exit rate. Investors will love any clarity around the forward growth trajectory and/or underlying economics. But it’s still very unclear what numbers we will actually get tomorrow before the S-1 is filed. Some told me Anthropic was meeting some sell-side today, but haven’t heard any leaks. The meetings tomorrow are with a broad group of investors, so we are likely to hear what was said and it wouldn’t be surprising if we see press leaks early on in the day.
In terms of positioning for semis heading into the print, JPM’s international desk says semis were the most net-sold industry by HFs last week (-1.5z in North America, -3z in EMEA), yet remain a top-2 net exposure in every region. We get a similar sense in our conversations: investors are long, but not as long as they were in June. If June was a 10/10, we’re probably around a 7+ now, but frustration near highs.
In macro land, the bond market reopened after Monday’s holiday and caught a bid into the semis rout: 10Y -4bps to ~5.22% (from 5.24% Friday) ahead of tomorrow’s 8:30am CPI print (consensus ~3.7% y/y vs. 3.4% in August). Fed’s Williams said he sees no need for a rate hike in 2027 “at this time.” Odds of a 10/28 hike sit at ~19%, about where they were Monday and way down from 70%+ in late September; December is ~74% priced for a hike, with ~25bps priced for the rest of 2026 and another ~60bps through October 2027. Crude reversed a ~-2% premarket dip to finish flat as attacks in Saudi Arabia and Yemen offset Trump easing sanctions on Russian diesel. BTC ~$83K after an overnight dip below $81K. Always interesting to see V and MA breaking out to new highs as data continues to show a strong consumer heading into the holiday season.
Let’s get to the good stuff…
AI/SEMIS
AMAT -6.7% was outperforming SOXX into its SEMICON West investor breakfast, then sold off hard once Dickerson declined to give a WFE outlook beyond saying it will be very big. The 2030 targets: ~54% non-GAAP GM (about +100bps a year), ~40% op margin, >2pts of WFE share gains from CY25 to CY30 and services >$12B. Q&A pushback: the share gain only wins back what AMAT lost in 2025, and GM is “only up 400 bips” over four years. Positioning didn’t help as the buy side was anchored to a ~$300B out-year WFE number. Bulls will be happy with 2030 margins above where the Street sits; bears get the slow GM ramp they flagged after the August print (F4Q GM flat on +12% revenue) and share gains that only get AMAT back to 2024 levels. LRCX -2.7%; KLAC -3.2%; ASML -1.9% in sympathy
Some good discussion in TMTB Slack here on whether the reaction made sense: