
Good afternoon. QQQs +88bps in a steady grind higher and closing just off the highs even as the long end backed up again.
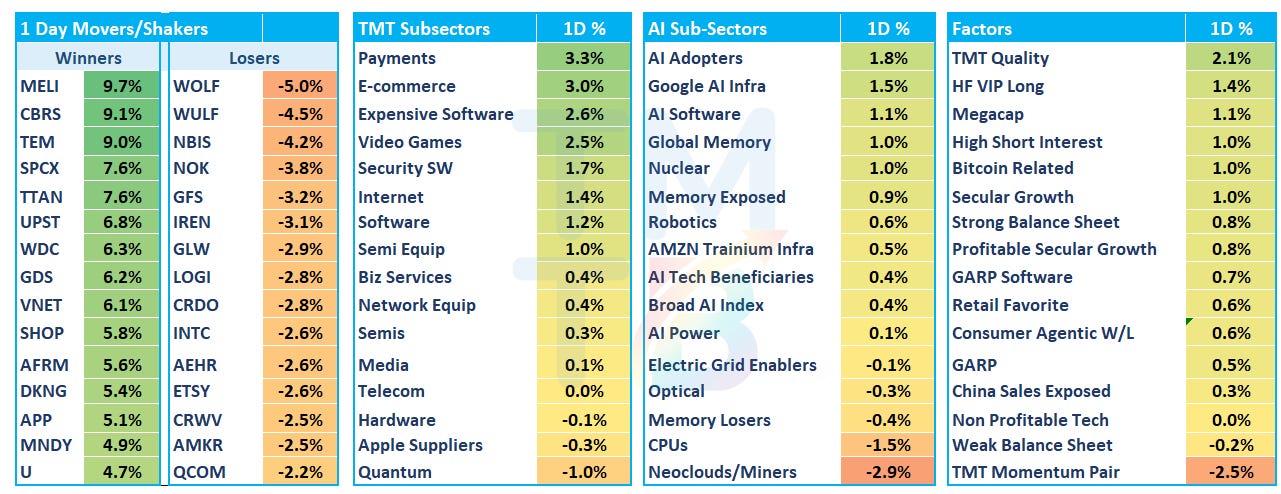
In Tech, Software +1.2% led as Schneider's $205/share cash takeout of PTC put a floor under vertical software (ADSK +4.5%; TTAN +7.6%) and the agent/e-com/cyber names kept chugging along (SHOP +5.8%; NET +3%; ZS +2.6%; OKTA +3%, etc.).
Semis +10bps lagged with megacap AI up and most everything else down: AVGO +2.1%; NVDA +2.1% worked after Morgan Stanley said both are shielded from the AI power crunch, the latter hitting new ATHs while the neocloud/BTM complex reversed early gains (NBIS -4.2%; WULF -4.5%; IREN -3.1%; CRDO -2.8%) and INTC -2.6% held most of its gap-down after Musk confirmed TSM talks on Terafab. HDDs bounced off Friday's Toshiba gap-down (WDC +6.3%; STX +4.5%) as sell-side was out in full force defending and CBRS +9.1% kept bouncing after Altman called it a close partner and sell-side defended.
In macro land, the long end kept leaking higher. The 10Y touched ~5.35%, the highest since 2002, after a roughly in-line ISM services print (54.9 vs. 55.4 in August) with prices paid up to 74 from 72.6, then gave back half as stocks ramped: 10Y +3bps to ~5.31%, 2Y flat at ~4.84%, another steepener. Fed pricing kept cooling after Friday’s soft payrolls (+29K vs. ~85-90K expected): odds of a hike at the 10/28 meeting are ~21%, down from ~30% Thursday and 70%+ early last week, though markets still lean toward one more hike by December (~75). Crude -2.3% to ~$89 WTI with no obvious headline and BTC +35bps to ~$85.7K. FOMC minutes and the 10Y auction Wednesday, 30Y Thursday.
Let’s get to the good stuff…
This is a great one to read if you are new to TMTB and want to see what we’re all about…
AI/SEMIS
WDC +6.3%; STX +4.5% bounced off Friday's ~10% Toshiba gap-down with the Street out in force. Bulls had a whole long list of things to push back on. Take a deep breath: 1) $380M isn’t a huge investment for this industry, and some likely goes toward equipment upgrades, testing and next-gen technology, not just new supply; 2) Toshiba's datacenter drives are 1–2 generations behind STX/WDC, still on 26/28TB CMR, with 40TB+ HAMR not expected until CY28 at the earliest; 3) the headline is a 2x increase in exabyte output at the Philippines facility, which is only ~2/3 of Toshiba’s base. On a total-company basis that implies closer to ~70% EB growth, roughly in line with STX/WDC, while unchanged unit forecasts are only low teens in FY27 and mid teens in FY28. Higher-capacity drives also mean “doubling capacity” does not mean twice as many drives; 4) Toshiba relies on TDK for heads, Resonac for media and Hoya for substrates, creating supply gates. We’ve heard Resonac is supposedly sold out through late CY27/CY28; 5) Toshiba has already pushed out its LSD million drives/quarter target because of yield issues 6) even if Toshiba doubled from ~200EB versus ~1,000EB each for STX/WDC, it only adds roughly 10% to industry supply, similar in absolute EB terms to what STX/WDC themselves are adding; and 7) the ’28 supply gap likely remains wider than Toshiba’s incremental capacity. Bulls will therefore frame this as a gradual expansion/upgrade that isn’t unexpected, not a major change in industry supply, while the recent STX/WDC underperformance (despite very strong pricing checks) suggests some of the Toshiba news was already circulating among Asia investors.
To us, this discussion feels similar to the Chinese supply debate for the memory guys: announced capacity isn’t the same as bits hitting the market. Still, memory names have largely already digested the Chinese supply risks which is partly why stocks have pulled back and already trade at mid single digit multiples. Similarly, the headline here was much worse than the likely fundamental impact, but unlike memory, the bear pushback is HDD multiples haven’t already discounted the risk and still trade at double digit P/Es. Any new entrant trying to gain significant share into an oligopoly will likely use price as a negotiation tool, and this likely gives hyperscalers leverage as they negotiate ‘29-’31 contracts.
Memory lagged: MU -1%; SNDK -92bps; SKHY flat
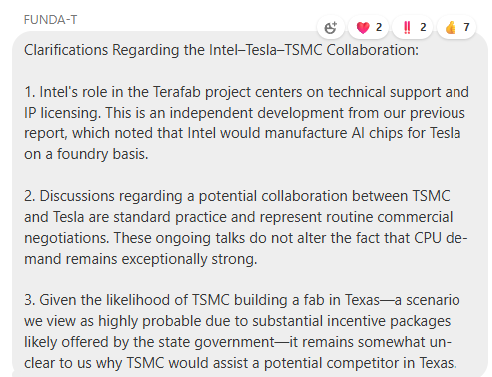
TSM +2.8%; INTC -2.6% on Musk confirming TSM is in discussions to join Terafab (”Just discussions, but something may come of it”), with DIGITIMES, citing Culpium, reporting suppliers now see >80% odds of a TSM-Terafab deal in Texas here. Funda’s had some good thoughts saying INTC’s Terafab role is technical support and IP licensing, separate from its earlier report that INTC would foundry AI chips for TSLA.