

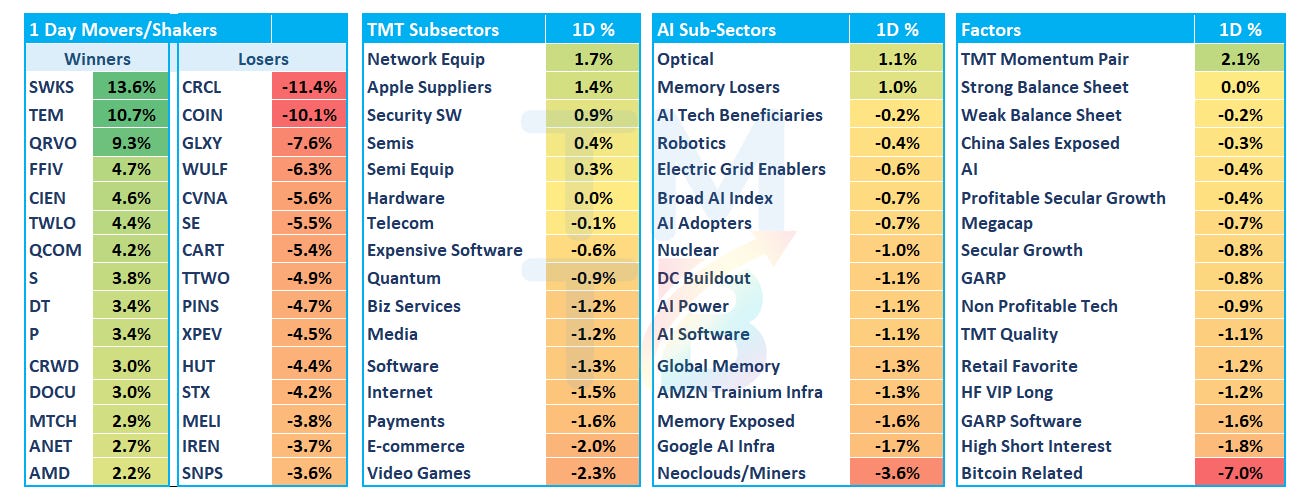
Good afternoon. QQQs -65bps ahead of Fed decision tomorrow as Oil +4% continued to be bid on Middle east turmoil. The market continues to price in 2 25bps increases before the end of the year (tomorrow and Dec). Semis +50bps managed to claw back a little of the underperformance from Software -1.3% today although it felt like a blip vs. yesterday’s historic divergence.
Lots to get to today in Tech so let’s dive right in…
AI/SEMIS


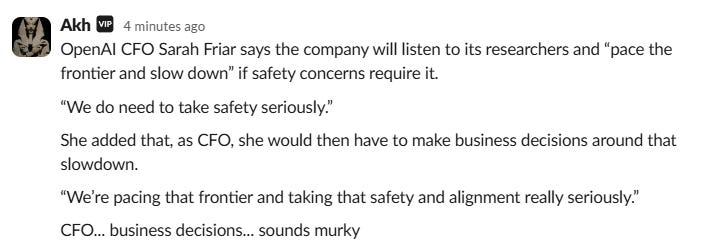
OpenAI CFO on Cramer:
Handset/AAPL related names continue to outperform: SWKS +13%; QRVO +8%
AMD +2% helped by the agentic CPU bid and positive pre-quiet period call with sell side. Piper and others recapped the call saying Helios rack production is beginning now with broader volume ramping into December/2027, while Venice server CPUs should drive >70% y/y CPU growth as AMD targets ~50%+ server share longer term. Piper says AMD has secured sufficient wafer/HBM/packaging supply to support guidance, with demand still exceeding availability and DC mix driving gross profit dollars higher despite margins hovering around ~55%
ARM +1% as Bernstein said AGI CPU program is on track, with demand already >$2B vs initial $1B FY28 target, saying Meta is expected to represent ~90% of the initial ~$1B FY28 AGI CPU revenue opportunity, with final qualification underway and first shipments expected in CQ1 2027 at roughly ~$100M of revenue.
NOK +2% as Rosenblatt initiated at $15, >50% upside saying they see the optical TAM expanding ~35% CAGR to $40–50B by 2030, with scale-out and eventually scale-up providing incremental upside beyond DCI/scale-across, and assumes no scale-up contribution in 2028 estimates. Rosenblatt also highlights U.S. InP laser capacity and Infinera integration as share/margin levers, arguing NOK should increasingly rerate from a telco multiple toward AI infrastructure.
NVDA +60bps as Semianalysis was out touting Rubing Economics saying Vera Rubin is already delivering up to ~7x Blackwell’s token throughput per MW versus NVIDIA’s ~3x GTC claim, with further upside as software/kernels mature
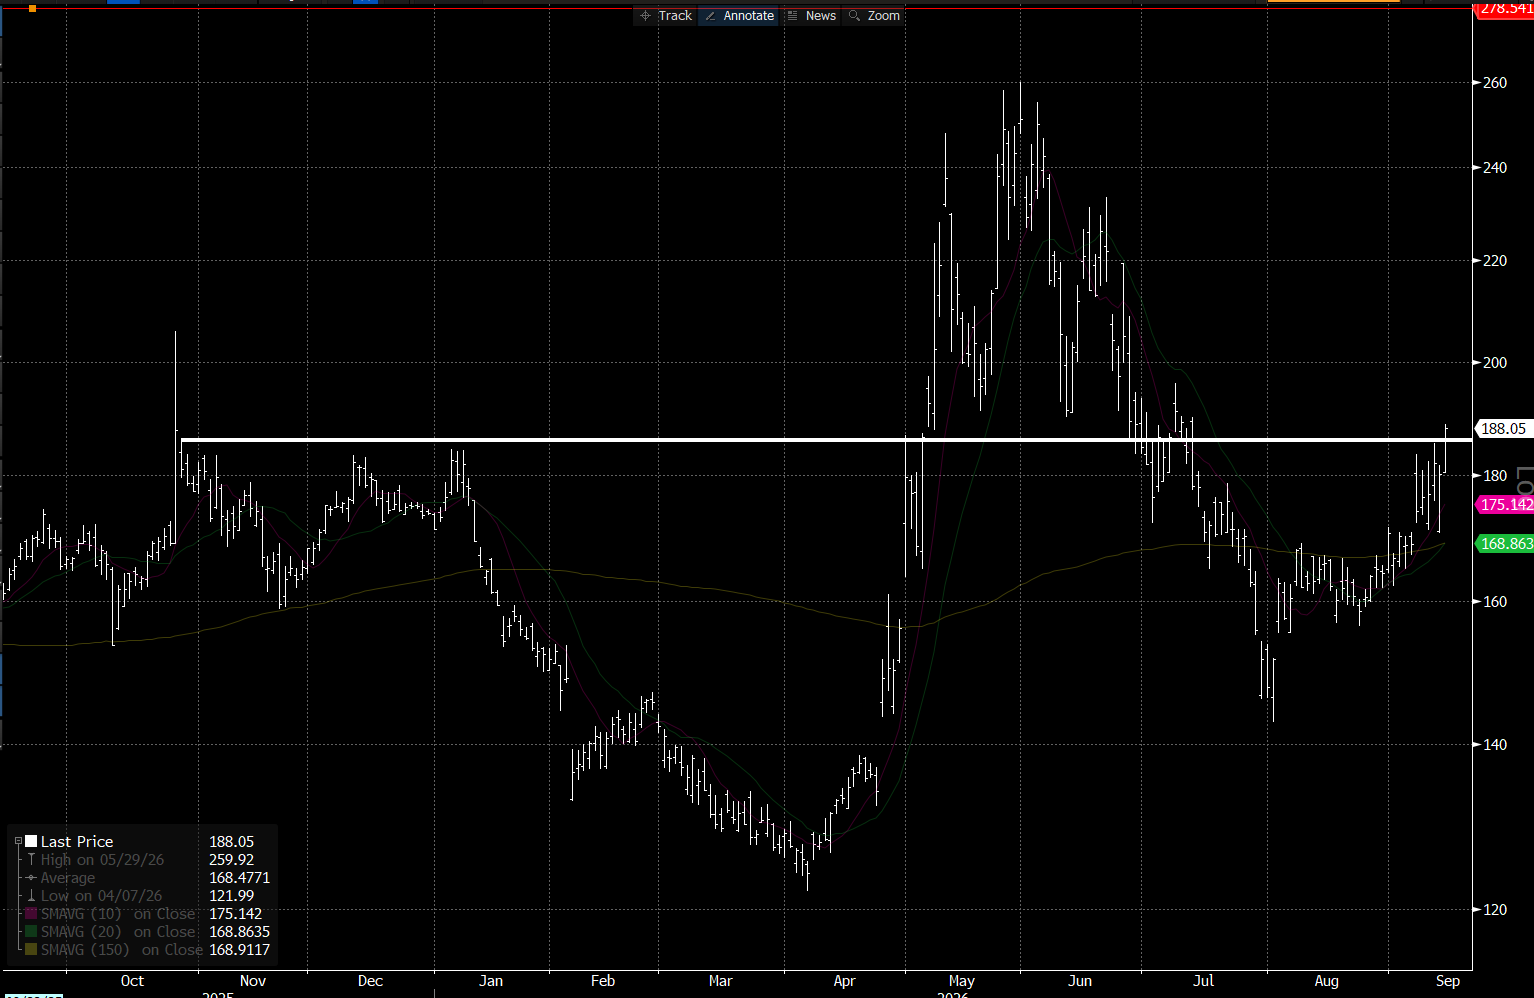
QCOM +4% getting carried up with handset strength despite not having content in AAPL Duo. QCOM ranked #1 in terms of positive incremental updates coming away from the conference appearances last week:
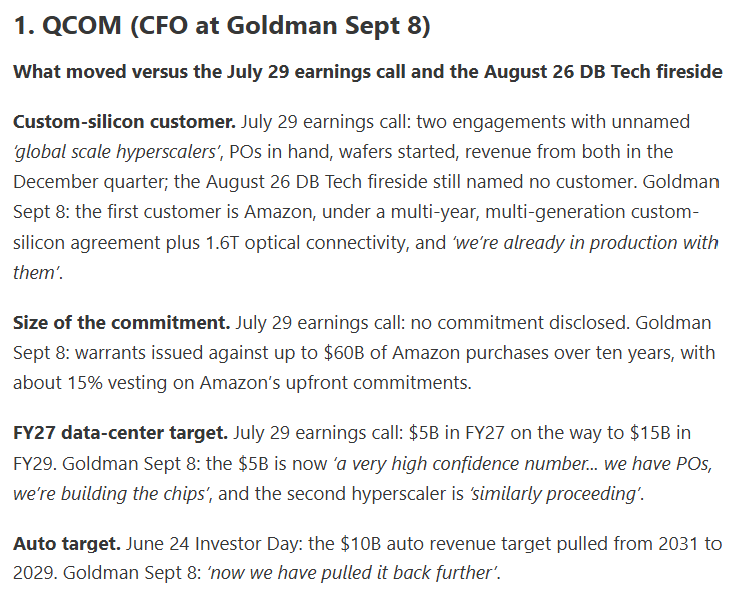
Chart looking better here as well:
Would love to hear bull case here from any bulls…
Enterprise AI/on-prem names to continue to be bid and continue to be seen by investors as beneficiaries from open source driven down token costs: DELL +2%; HPE +1%
AVGO -1.5% struggling to find a bid as investors continue to worry about Mediatek share loss
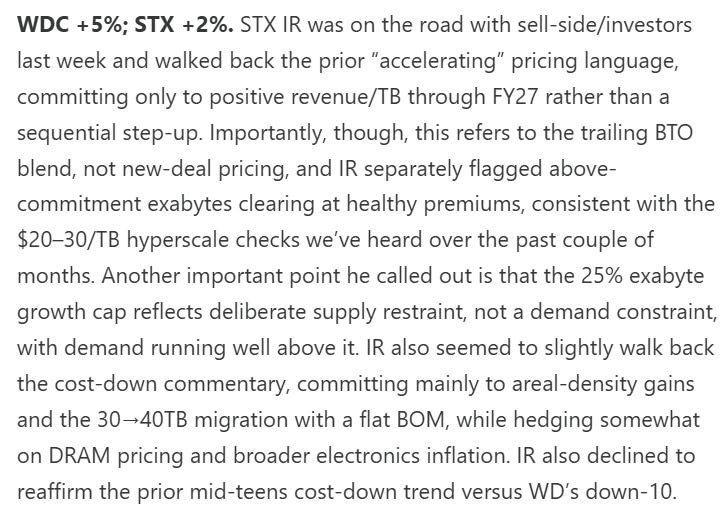
HDDs weaker with STX -4%; WDC -3.5%…didn’t see much here but space has been one of the weakest over the last month and a half and one of few AI semi sectors finally below the “Leopold Lows.” Pricing checks have remained strong and mgmt sounded good in presentations at conferences last week, although haven’t heard what they were saying in 1x1 meetings. As a reminder STX IR was on road last month (mid Aug) talking down cost commentary a bit, so some of that still plaguing the group. From our EOD Wrap on Aug 17th:
Outside of that, haven’t heard much why they’ve been weaker than other sectors with AI semis - if you know, let me know.
FLEX -30bps struggled to hold a bit despite some new info on their spin: Cloud and Power Infrastructure spin-off will be named Axiom Solutions International with separation targeted for 1Q27. Axiom will combine power, cooling and compute infrastructure for AI/data-center deployments, while Flex and Axiom will operate as separate public companies post-close. More strategy detail is due at Innovation Day on Nov. 10.
P +3% ahead of investor day on Sept 23rd. BofA was out previewing it positively saying it could include a 3-year revenue/margin framework, and sees upside to Street after Everpure’s second hyperscale win validated DirectFlash
INTERNET
META +75bps as Muse continues to receive good reviews and remains on #2 on the Apple app store despite only launching in the U.S. Bloomberg our reporting META plans to deploy its MTIA 450 inference chip in 1H27, with >1GW of capacity committed over the following 12 months and Astrid ramping by YE27; early silicon is tracking within 2–3% of simulations. Bloomberg notes META’s strategy is increasingly focused on low-cost, power-efficient general-purpose inference, reducing reliance on NVDA at scale while remaining a positive read-through for AVGO/TSMC.
AMZN -2% continues to underperform other hyperscalers as agentic worries hitting the stock as Muse/Instinct adoption continues to increase. Bulls will say agents should favor Amazon’s selection, pricing, delivery and fulfillment advantages, while AWS benefits from the extra compute demand. Bears will say Muse/Instinct could own discovery and purchase intent, leaving AMZN shipping the boxes while someone else captures the customer relationship and ad dollars. Bernstein was also out saying AWS web metrics remain soft through early September, though Q3 should still show ~50bps of ex-AI growth acceleration given the strong start to the quarter. Bernstein sees more risk in Q4, where non-AI AWS growth could face an additional ~100bps headwind versus current estimates as traditional workloads weaken.