

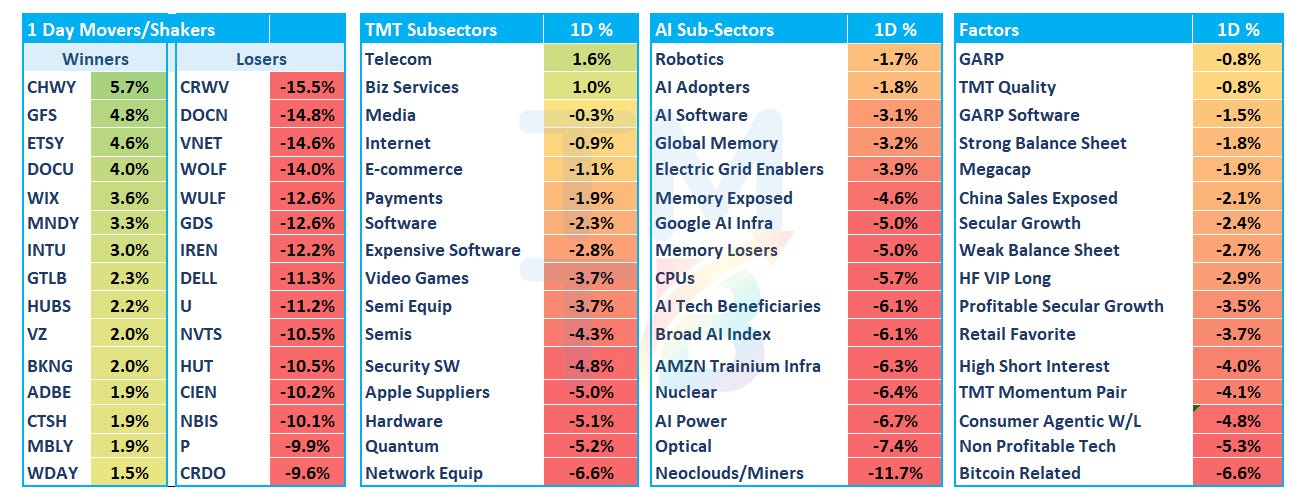
Good afternoon. QQQs -2% (down as much as -2.3%) had one of the ugliest sessions in a while for anything with AI-infrastructure or AI-financing beta, as CRWV’s bonds slid into distress, a hot CPI lit up yields for a few hours and everyone waited on Anthropic’s numbers (still haven’t heard anything as of 2pm pst as supposedly the 1x1 meetings are still ongoing with buyside). Nothing was spared today with many HF favorites across all sectors even outside semis getting hit. Semis -4.5% and software -3%, with neoclouds (CRWV -15.5%; IREN -12%; NBIS -10%), servers (DELL -11.4%; HPE -8%) and optical (CIEN -10%; COHR -9%; LITE -9.3%) at the epicenter. The only places to hide were app software (DOCU +4%; HUBS +2%; INTU +3%), telcos (TMUS +2.6%; VZ +2%), AAPL +50bps, and CHWY +5% (pets an AI safe space…well until Physical AI that is).
Talk of the day was AI financing, and it started in credit. CRWV’s 2032 unsecured bonds closed at a record ~14.5% yield Tuesday, Musk replied “Yikes” to Chamath’s post on them that evening

and the FT reported overnight that CRWV wants insurers to fund more of its build through investment-grade, chip-backed loans, co-founder McBee noting insurers’ capital “is unlimited.” By midday the 2032s were below 80 cents, CDS was pricing a ~58% chance of default within five years, and Reuters reported record CDS for both CRWV and ORCL. Around 1:25pm Bloomberg had CRWV CEO Intrator’s staff memo (backlog “more than supports” its debt; rivals’ weakness “bleeding into” the narrative), then him blaming the drop on the market acting “irrationally.”

But as market veterans know, when a CEO has to publicly reiterate “confidence” in funding and the ability to meet debt obligations, the conversation has shifted from a place tech investors feel comfortable (“growth”) to one not many are comfortable: balance-sheet risk. Nobody ever got into tech investing to read a debt covenant (here at TMTB, we’re more comfortable with top line accel/decel debates).
CPI gave the sell off a rates excuse at the open (core +0.36% m/m vs. 0.22%). Some feedback from TMTB Slack:
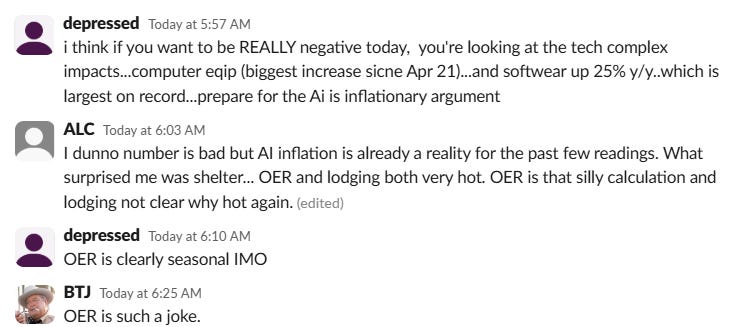
But by early afternoon the 10Y had round-tripped the whole move while semis kept sliding.
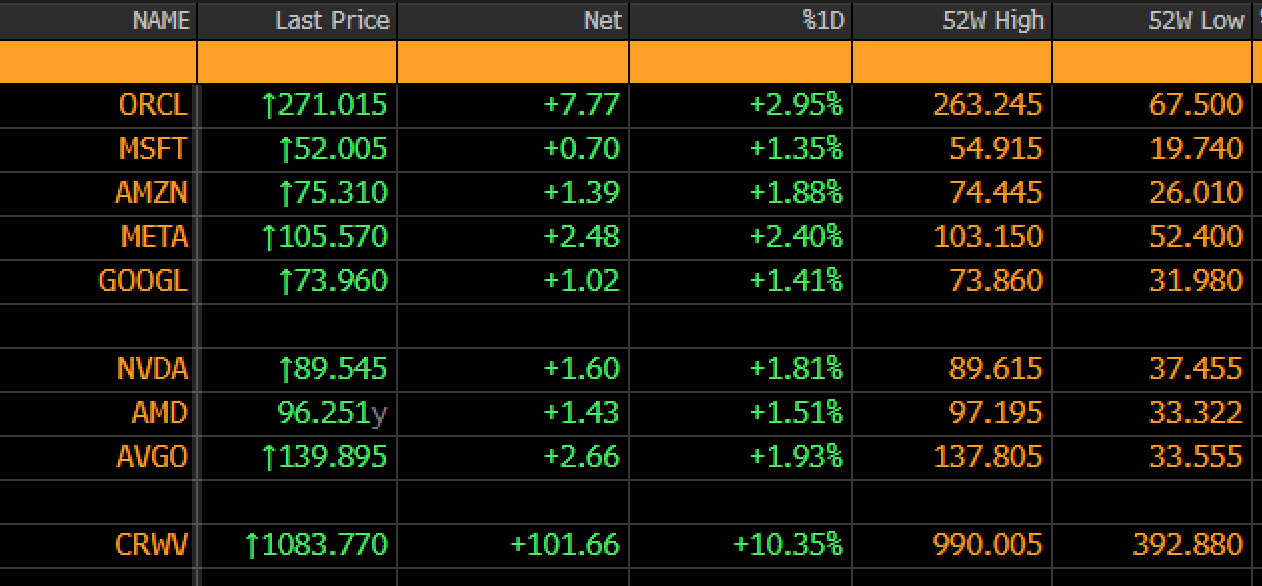
Then the midday headlines piled on. WSJ reported OpenAI’s compute chief is leaving after about a year (OpenAI named xAI’s Uday Ruddarraju to run data centers and compute); Sachin Katti’s own post says he secured “double-digit GWs of compute” with NVDA, AVGO, AMD, ORCL, MSFT, GOOGL and AMZN:

And Gartner’s release (out at 4:22am, but it made the rounds from midday; CNBC’s Carl Quintanilla posted it at 2:08pm):


Key line from the release: “More than $3.5 trillion of AI infrastructure spending could be exposed to impairment by the end of 2030, if AI providers continue their current pace of capital spending.” The math: ~$1T of spend this year and ~$6T more in 2027-30 needs ~$8.5T of cumulative revenue to cover capex, financing and a 12% return, vs. Gartner’s ~$3.6T of AI-attributable revenue.
The backdrop is worse than one name however as all this financing focus has put circular financing back in focus: a snippet passed along to us from a sell-side credit call said that data-center financing has “effectively stopped,” with a META-backed DC deal pricing at 7.5% vs. 6.5% expected, QTS settling for a 5-year non-call-2 because a 10-year wouldn’t clear, and no DC issuance for one to two months despite a healthy pipeline, as it’s become impossible for DC developers to issue debt at 8-8.5% and keep the equity economics attractive enough to build.
Some were flagging CDS among hyperscalers blowing out:
Part of this is hedging rather than anything to read-through on credit: lenders and bond buyers taking down the wave of AI financing (GPU- and TPU-backed deals, data-center debt, etc.) hedge by buying CDS on the names standing behind it, which pushes spreads wider across the complex regardless of the fundamentals. AVGO’s deal is the cleanest example: it backstops the bonds that finance its customers’ TPU buys. Buyers of those bonds hedge the backstop by buying AVGO CDS, which gaps wider on an otherwise high-quality name; the move hits the WSJ and X → the headline scares more holders into hedging → and the loop feeds itself. The irony: what starts as prudent risk management ends up looking like evidence of the very risk investors are hedging.
All of this into Anthropic’s closed-door investor day in SF - lots of rumors and talk being passed around on X, but nothing substantive which is worth passing along.

Anthropic’s implied valuation on Liquid slipped below $2T, down ~10% in a month


Ramp’s AI Index opened the day with “AI spend stutters” (top 1% of firms at $9,568 per employee per month in September, -3.1% from July’s high;


though bretzel noted in TMTB Slack here that Ramp quietly revised August up 10%+ and the data still imply ~11.5% m/m growth. Ramp’s afternoon follow-up had OpenAI growing at Anthropic’s expense, but Anthropic’s lead “not budging,” with Opus 5.5 driving 34% of business spend:

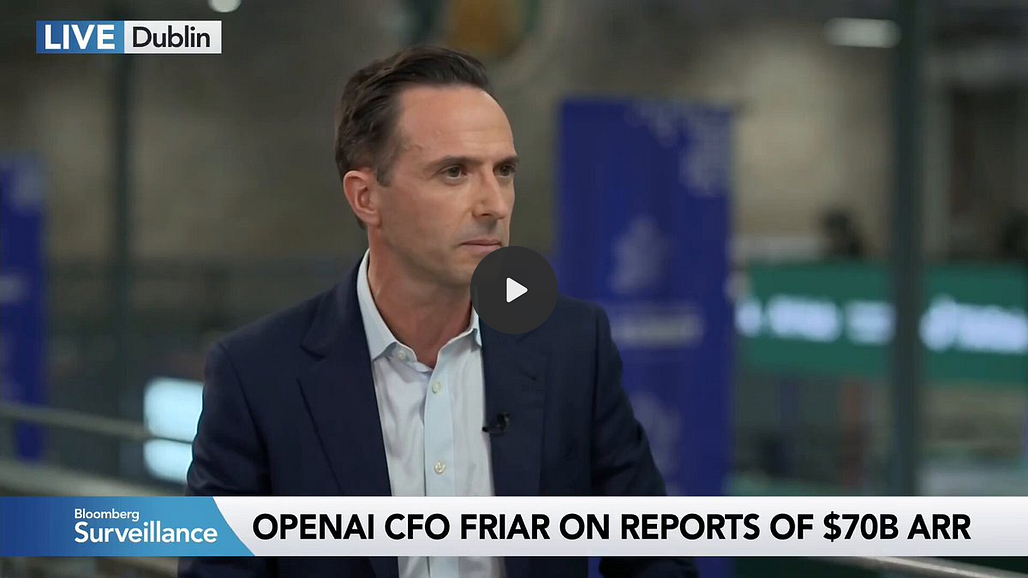
OpenAI’s CFO Friar told Bloomberg TV that Q3 hit close to $50B, up 70%+ q/q, with Q4 “continuing at pace” and cyber a big driver from here (more in software):


Positioning wise, RBC’s Calvasina cut US tech to market weight this morning in favor of health care (XLV +2.5%), citing decelerating upward EPS revisions in semis and semicap and weaker tech fund inflows. And the flows don’t look like the late-July correction to JPM’s Panigirtzoglou: no retail buy-the-dip yet, a buyback flow cliff, no large short base and more AUM in leveraged equity ETFs.
In macro land, September core CPI printed +0.36% m/m vs. 0.22% expected (headline +0.6%, 3.7% y/y vs. 3.6%), with gasoline +9.1% and shelter +0.4%. The 2Y jumped ~13-15bps to ~4.93% and the 10Y touched 5.33% after the print, then the long end round-tripped: by late afternoon the 10Y was ~5.19% (-3bps vs. Tuesday’s 5.21% close) and the 30Y ~5.53% (-4bps). Odds of a 10/28 hike jumped to ~50% from ~22% Tuesday and ~18% a week ago; by December the market sees ~96% odds of at least one more hike and ~40% odds of two (~34bps priced for the rest of 2026), plus roughly two more hikes in 2027. Crude +1% to ~$95 after the Houthis hit a Saudi Aramco building and the IEA warned supply could stay tight into next year. BTC -1.8% to ~$81.7K.
Never a great day for tech when the TMTB intro is this long and half of it sounds like a distressed-credit research note. The good news: TMTB Slack was lively as ever and kept things fun.
OK, let’s get to the good stuff…
AI/SEMIS
Neoclouds and miners took the brunt: CRWV -15.5%; IREN -12.2%; WULF -12.6%; NBIS -10.1%; HUT -10.5%; GLXY -9%, with China IDC in sympathy (VNET -14.6%; GDS -12.6%). This is CRWV’s medium-term bear case playing out in credit: growth needs more debt, equity, leases or prepayments (FY26 capex $37B, ~4x Q2 revenue), and a 15% cost of unsecured debt makes that bill more expensive; bulls lean on the >$129B backlog and 4.2GW of contracted power, which is what Intrator’s memo pointed to.
Some good discussion in TMTB Slack here after the memo on whether the bonds are telling you something the backlog isn’t.