

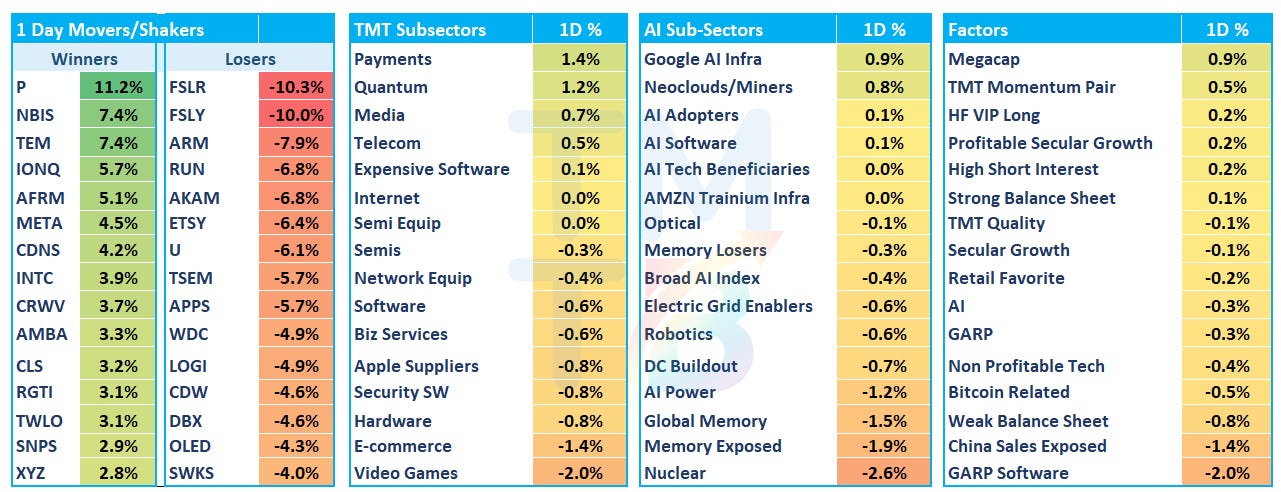
Good afternoon. QQQs flat (-1bp) in a session that looked a lot worse early. QQQs were down ~90bps at the lows before bouncing, led by META +4.5% (best month since 2013, knocking on the door of $2T) and a sharp reversal in the CPU complex (AMD +2.4%; INTC +3.9%, both off -2.5% lows). Semis -33bps after opening down ~2%, while software -90bps lagged again as the AI-loser basket stayed under pressure (INTU/PATH/ACN/CTSH -3%+).
Rates and oil continue to be top of mind on the macro front. The long end sold off again (TLT -1.3%): the 10Y rose ~10bps to ~5.2%, the highest since 2007, and the 30Y touched 5.5%, highest since 2004, helped by a sloppy 7-year auction (cleared at 5.085%, highest since 1993) and more hawkish Fedspeak (NY Fed’s Williams said another hike “may be appropriate by the end of the year”). Crude +2.8% (WTI ~$95; Brent ~$106.60 after spiking to $108 when Saudi Arabia intercepted Houthi missiles aimed at Yanbu, its export route around Hormuz). QQQs turned up around 12:15, jumping ~80bps in 30 minutes, when Reuters reported the US and Iran are discussing a phased deal to reopen Hormuz. Trump is hosting Xi at the White House (trade truce extended to January). BTC flat. Fed expectations didn’t shift much as the market continues to price in 40bps of incremental hikes this year (the odds of an increase on 10/28 stand at >70%) and another ~55bp in 2027.
In AI infra land, the day was bookended by two very different headlines. Before the open, Bloomberg reported ORCL -3.5% sent a force majeure notice to the Blue Owl-backed developer of Project Jupiter, its giant New Mexico campus, to shield itself on payments if the site slips. ORCL isn’t walking away from the capacity and says Jupiter remains on schedule. The glass half full empty read from investors is that this potentially makes lenders more cautious about funding the next project.
After the bell, things more positive as Anthropic signed an $11.6B, seven-year commitment with AKAM (+20% post-close) for CPU capacity. Coming from a frontier lab, not a consumer app after the MUSE narrative ramped CPU stocks over the last couple weeks. Just shows how much CPU demand there is out there across the board.
Details:
The AKAM deal with Anthropic is $11.6B of contractual commitment over seven years to support Anthropic’s “accelerating CPU workload demands” on AKAM’s Cloud’s distributed infrastructure (Can expand by up to another $9B, for ~$20B of total potential commitment). That’s ~6x the $1.8B, seven-year Anthropic deal from May (at the time the largest contract in AKAM’s 28-year history), and the 8-K suggests tonight’s $11.6B comes on top of it (two new project plans signed 9/18 under the May master agreement; worth confirming on the call). The stock had closed at the lows right before the release, giving back part of its edge/agentic run alongside FSLY. Warrant to Anthropic for up to ~5% of the company (7.7M shares) at a $111.33 strike, basically today’s close. ~2% vests on the first payment under the new plan; ~1% more for every additional $3B committed.
Read-throughs from Claude:
AKAM’s cloud already runs on AMD EPYC. The current top tier is 5th-gen EPYC and the one before it is 3rd-gen. I found no Intel or Arm servers anywhere in their lineup. The dollars are modest for AMD. My rough math is about $1–1.4B of CPUs over 2027–28.
JBL. The 8-K has Jabil holding Akamai’s $1.7B of memory on consignment and buying it back at cost as it uses it. That means Jabil is building the servers. It’s big revenue at thin margins.
Lenovo (992 HK / LNVGY). It signed a new 7-year hardware deal with Akamai on 9/23, likely the second server supplier.
More details:
$5.5B of capex tied to the deal, including ~$1.7B of extra 2026 capex to “secure and pre-purchase critical supply chain components, including memory” (per the 8-K, a memory order through Jabil). For reference, 1H26 capex was ~$550M and they had $4.6B of cash at 6/30. No change to the 2026 revenue guide. Call ongoing right now…Reminder: AKAM round-tripped the May deal. It jumped 27% on the day, then gave all of it back by 9/18 although that included the big July semis drawdown.
Let’s get to the good stuff…
AI/SEMIS
Neos strong on the back of a pair of upgrades as GPU pricing remains firm. CRWV +4% was upgraded by JPM saying pricing backdrop has strengthened materially, with July pricing +25% across SKUs, recent short-duration contracts signed around ~$40M/MW, and short-term capacity commanding roughly 3x long-term pricing. BNP upgraded NBIS +7% as they see 2027 as key catalyst as scarcity pricing drives materially higher AI Cloud returns, calling out a path to $22B+ ARR exiting 2027, 30% above street as META/MSFT capacity ramps and incremental capacity reprices higher. Remember, NBIS has more near-term leverage to pricing.
AMD +2.4% / INTC +3.9% reversed hard off the morning lows (INTC closed at the highs), shrugging off the M-sci shipment datapoint on AMD we flagged this morning. KeyBanc’s bus-tour note helped INTC (14A “~1 year ahead of where 18A was”), and NBIS told customers it’s raising AMD EPYC CPU instance prices ~25% on 10/1. Lots of questions on the odd one out: ARM -7.9% and closed near the lows. No great answers other than giving back some outperformance over the last two weeks. Lots of debate over how much actual incremental impact there is from MUSE and consumer agentic apps where event some bulls think although directionally right, a little over their skis at the moment (although Anthropic/AKAM deal post-close just adds some fuel to CPU demand is insatiable narrative). Some good discussion in TMTB Slack here on the topic: