

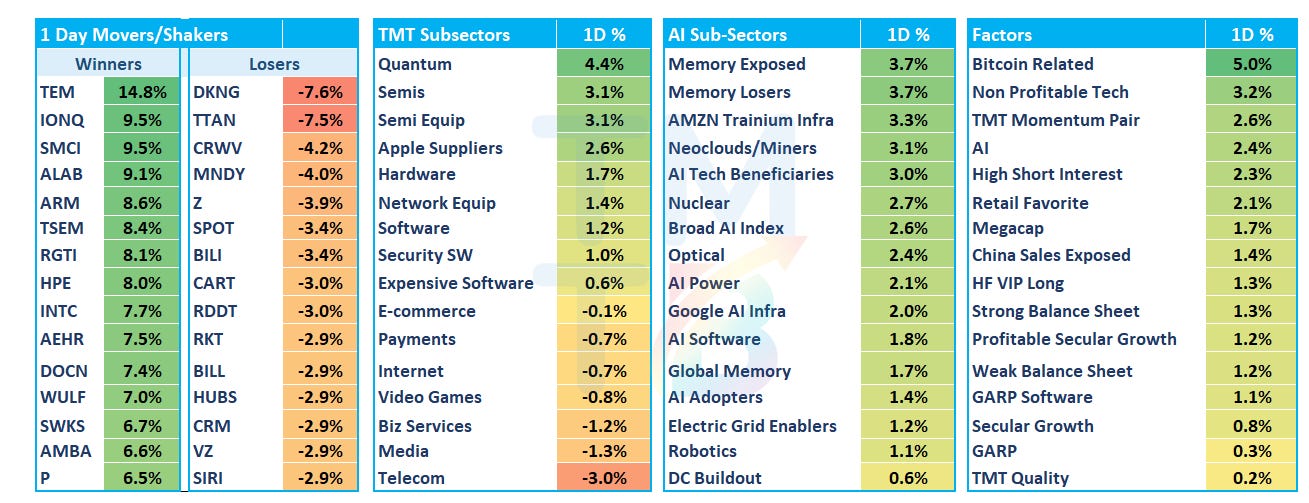
Good afternoon. QQQs +1.8% as yields dipped 8–10bps across the curve and oil fell 2%. Semis +3% led the way higher as sentiment continues to regain its footing. The path here: sentiment improved heading into and out of the GS and Citi conferences as management teams sounded good and investors felt emboldened enough to put some gross back on (rumors of even Leo re-grossing up). Then AI safety threw a wrench into things over the weekend, but the debate now seems to have settled on: nothing is really slowing down, and AI safety may actually require more compute for alignment. So naturally, we went from “AI safety is bad for chips” to “AI safety needs more chips” in about 72 hours. Always a fun time in the AI trade. Lots of charts looking better after today with CPU trade & BE (BTM) leading the way higher…
Despite the semi strength, software +1.2% still held a bit as outflows were concentrated in non-hyperscaler internet names.
Let’s get to the good stuff…
AI/SEMIS
NBIS +4% sold off most of the day after news they were raising GPU rental prices by 20% on Oct 1st, likely weighed down by the CRWV -4% ATM Convert offering.
CPU complex strong and has climbed to the top of the sentiment ladder in AI semis, as they remain key beneficiaries from enterprise/consumer agentic harnesses and on-prem rollouts: AMD +6%; INTC +7.5%; ARM +8.5%. Some specific things to call out on each name. The AMD and INTC charts looking really nice breaking out to 2 month highs.