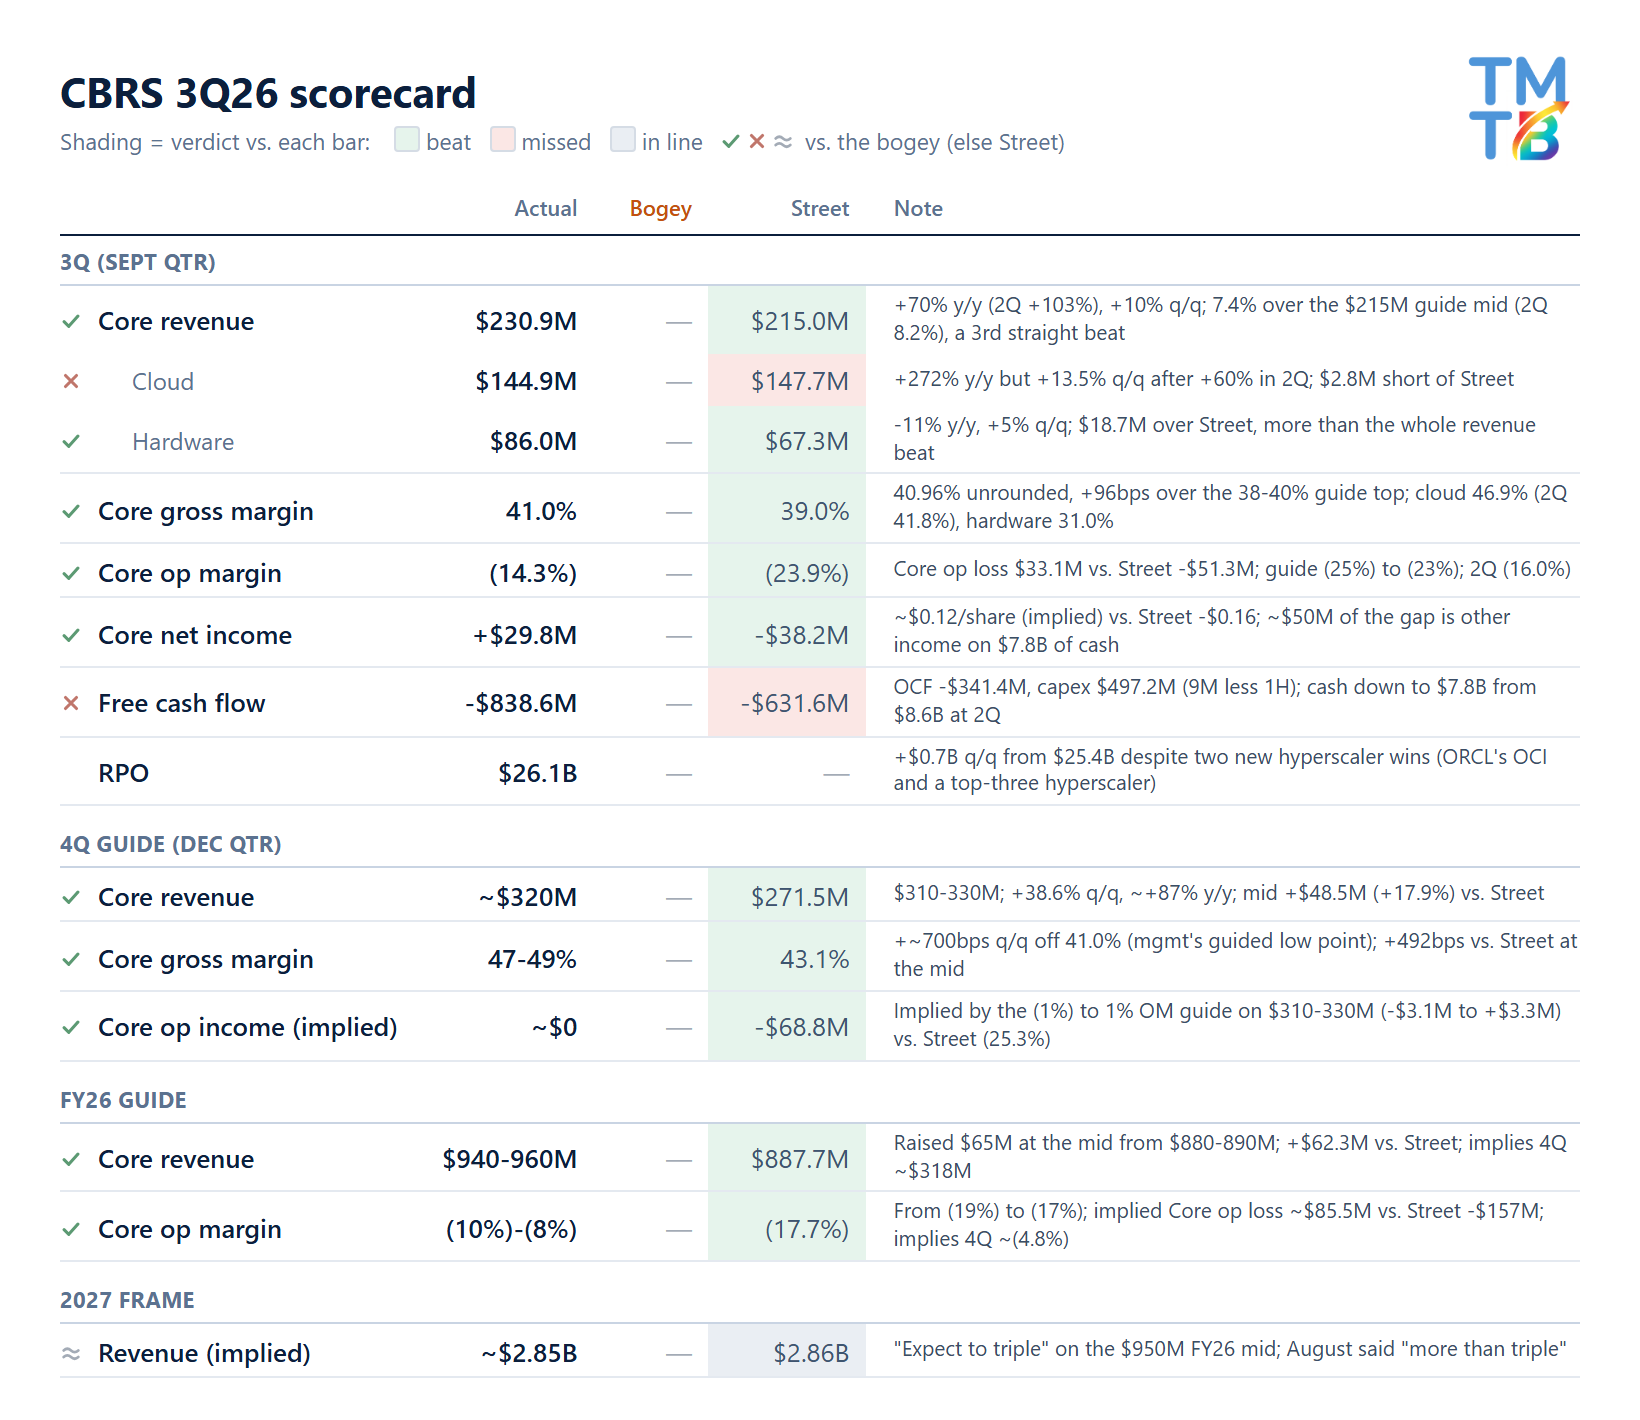

CBRS +13%: Big beat and raise, with a 4Q guide way over Street on both revenue and margins; hw beat and cloud missed.
Didn’t hear many bogeys here but expects/positioning pretty low for a stock that has underperformed big time since IPO heading in so these #s much better…
3Q Core revenue (the non-GAAP line Street and the guide use) of $230.9M (+70% y/y, +10% q/q) beat Street $215.0M and the ~$214-216M guide at a 41.0% Core GM (Street 39.0%, guide 38-40%) and a (14.3%) Core OM (Street (23.9%), guide (25%) to (23%)).
The 4Q guide is ~$310-330M (mid $320M, +39% q/q) vs. Street $271.5M, with Core GM of 47-49% vs. Street 43.1% and Core OM of (1%) to 1% vs. Street (25.3%); FY26 Core revenue goes to $940-960M from $880-890M (Street $887.7M), and they announced a cloud deal with a top-three hyperscaler.
Bulls will point to a 3rd straight quarter over the guide, a 4Q guide that takes y/y growth back to ~+87% (from +70% in 3Q) with 47-49% Core GM after mgmt called 3Q the GM low point in August, FY26 raised $65M, and the top-three hyperscaler deal on top of an ORCL cloud (OCI) integration.
Bears will lean on hardware doing the beating (Core $86.0M vs. Street $67.3M) while Core cloud missed ($144.9M vs. Street $147.7M; +13.5% q/q after +60% in 2Q), RPO up just $0.7B q/q to $26.1B despite two new hyperscalers, 3Q FCF of -$839M vs. Street -$632M, and 2027 wording trimmed from “more than triple” (August) to “triple” (~$2.85B on the new FY26 mid, in line with Street’s $2.86B).
Key quote (release, CFO): “we saw our pipeline for high-speed AI inference increase by more than 10x in the quarter.”