
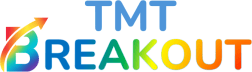

APP +22.2%: Gaming, where bears saw share loss to U, was the bright spot. It grew nearly 50% y/y (their first gaming growth disclosure in a year) on a partial rollout of new ad models, driving most of the 3Q beat ($2.185B vs. ~$2.10-2.12B bogeys), first acceleration after four straight decels (although the 2 yr stack decel’d) and biggest beat vs. street since 1Q’25. The 4Q guide, counting only model gains already live, beat bogeys on revs ($2.38B mid vs. ~$2.33-2.36B) and EBITDA ($2.01B vs. ~$1.93-1.96B). Foroughi said share-loss checks “tend to end up being flawed” and called 2Q’s miss “our own foot fault,” but mgmt gave no take rate, gaming vs. consumer split, full-rollout timing or e-com revenue: “You sort of have to make your own guesses.” Foroughi called the 3Q model rollout “a model transition as significant as Axon 2.0,” and asked if it’s Axon 3.0, put it on that level “from a technology standpoint in terms of technical complexity.” It’s “still in partial rollout,” the 4Q guide counts only gains “already live,” and there’s no timing on the full rollout.
Crowded HF short that ran 19% this week into the print, including +11% today but this should still be good enough for a stock that now trades at 15x P/E. The pushback is the 4Q guide’s +8-10% q/q (vs. +14% in 3Q), but their usual ~5.5% beat on the mid would take 4Q to ~+15% q/q. No 2027 number, but 2026 now tracks to ~$8.33B (nine months reported plus the 4Q guide), so Street’s ~$10.1B for 2027 assumes just +21% growth, well short of the “roughly 30%” a year Foroughi says the business can compound at long term. At 30%, 2027 revenue would be ~$10.8B. Overall, much better than feared after U share-loss scare, and the higher base de-risks 2027 and likely gets some bulls back on board hoping for e-com to ramp and beats to continue in ‘27. U -1% in the post ahead of Thursday’s print:

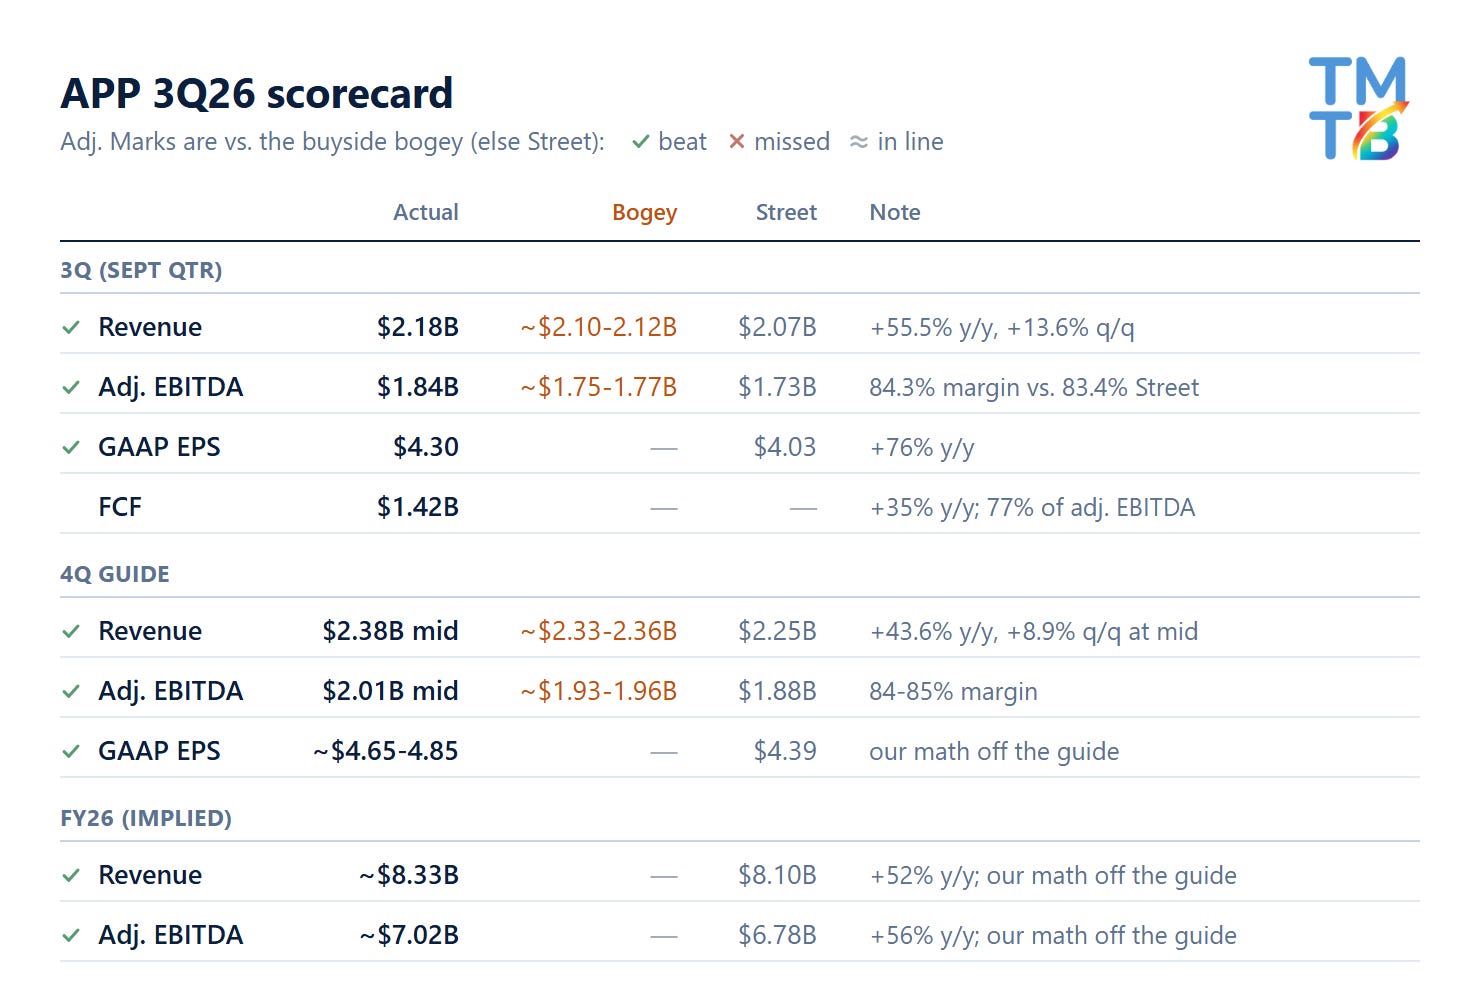
QCOM -6.9%: Revenue cleared the bar but the GM recovery was shifted out. Record auto ($1.99B, +89% y/y) drove the Sept-Q beat. DC’s first quarterly guide (>$650M vs. a ~$0.5B bogey) and only a mid-single-digit q/q handset decline put the Dec-Q guide at $10.8B, above the ~$10.05-10.25B bogeys. But GM fell a 4th straight quarter (52.4%), and the Dec-Q EPS guide ($2.25 mid) missed Street’s $2.33. On GM, the worry going in, the CFO said price increases only return QCT GM to “the low end” of 48-50% by 2H FY27 (vs. “over the next couple quarters” in July), before DC dilution, and declined to guide March, FY27 opex or the QCT operating-margin path.
Under-owned and a favored HF short, it squeezed +5% into the close as SOXX fell 3% in the post-election rotation. It slid from -5% to -8% within ten minutes of the GM answer. DC’s $5B FY27 target held; upside is “constrained by supply rather than demand,” the CFO said. Overall, better than feared on revenue, but the GM framework brings FY27 #s lower. More fuel for bears.
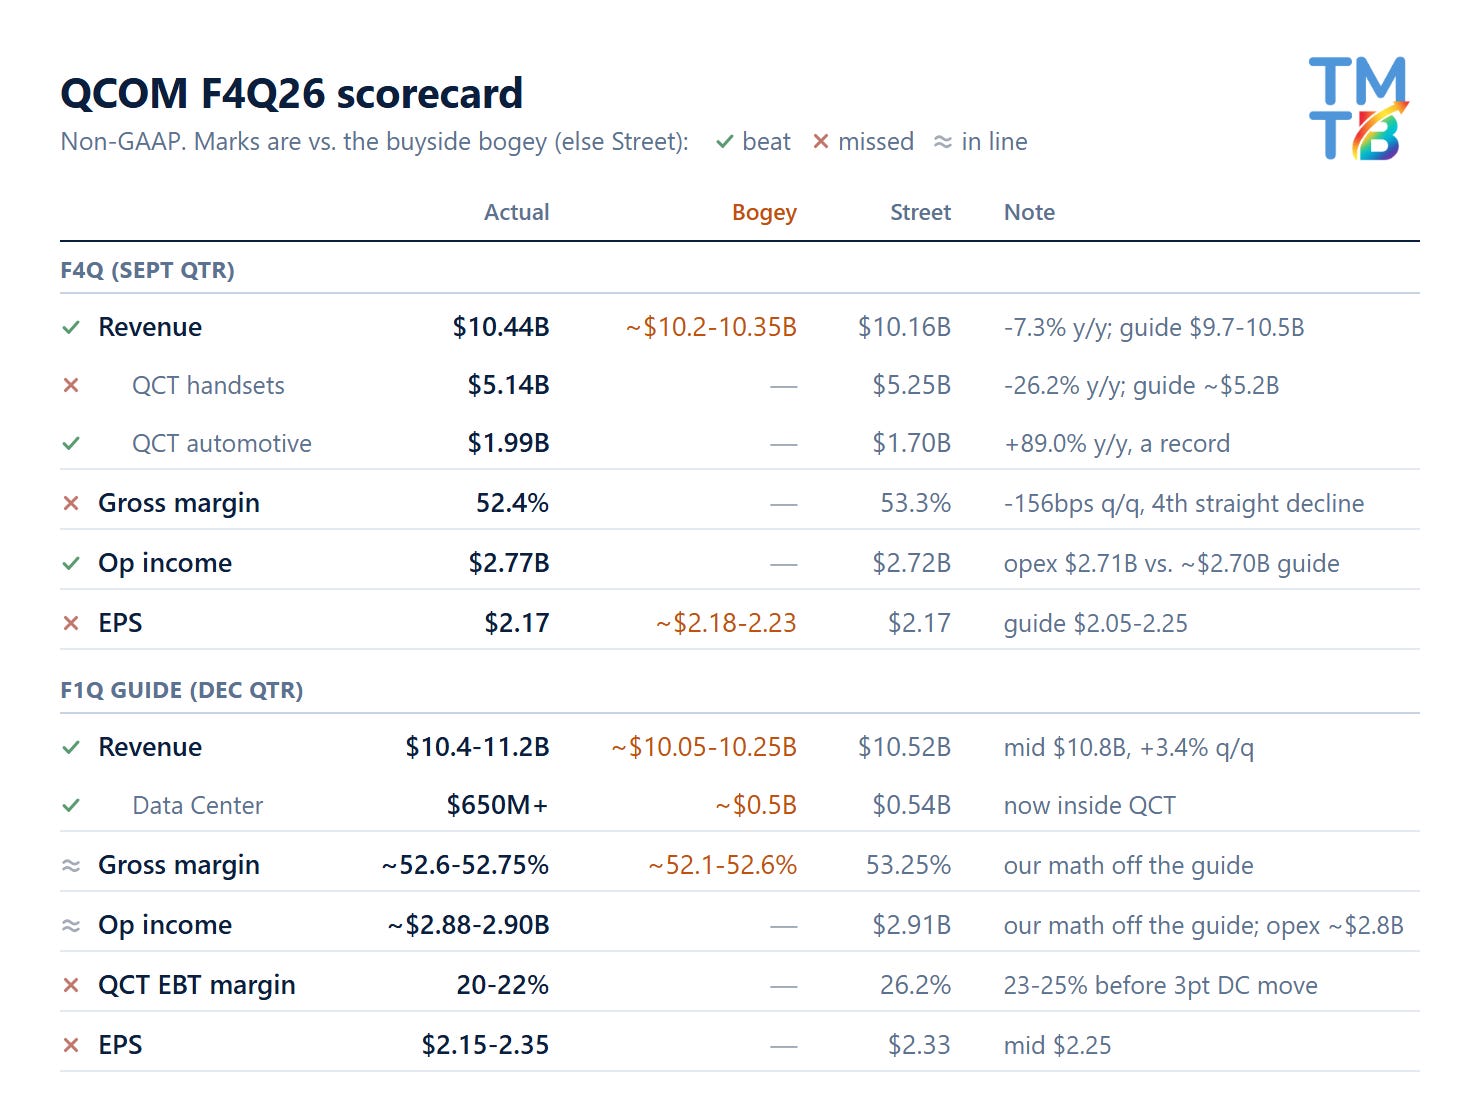
ARM -1.4%: License is carrying ARM while phones drag on royalties. License ($773M, +50%) ran “around $100 million higher than we had anticipated”, per the CFO, while royalty ($670M, +8%) missed the ~$705-712M bogeys. The $1.54B Dec-Q guide mid matched the top of the ~$1.50-1.54B bogeys, with implied op income ~$10M above Street. But the CFO guided royalty up just “low single digits year-on-year” (~$755M on last year’s $737M, vs. Street $818M). Add Street’s March quarter and FY27 royalty is ~$2.96B (+13%), below the ~$3.06-3.10B bogeys. Mgmt blamed memory prices hitting mid- and low-end phones and sees some recovery in the March quarter, but wouldn’t commit to license holding ~$770M a quarter next year and didn’t update July’s high-teens FY27 royalty view.
Positioning mixed going in with stock down 30% in Oct. AGI CPU offset the royalty miss: asked what drives the $15B FY31 target, the CFO said “we are increasing our confidence to deliver $2 billion” over FY27-28 (vs. >$1B in July), the top of the ~$1.5-2.0B bogeys. Overall, worse than feared on royalties but delivered the AGI CPU raise bulls wanted.
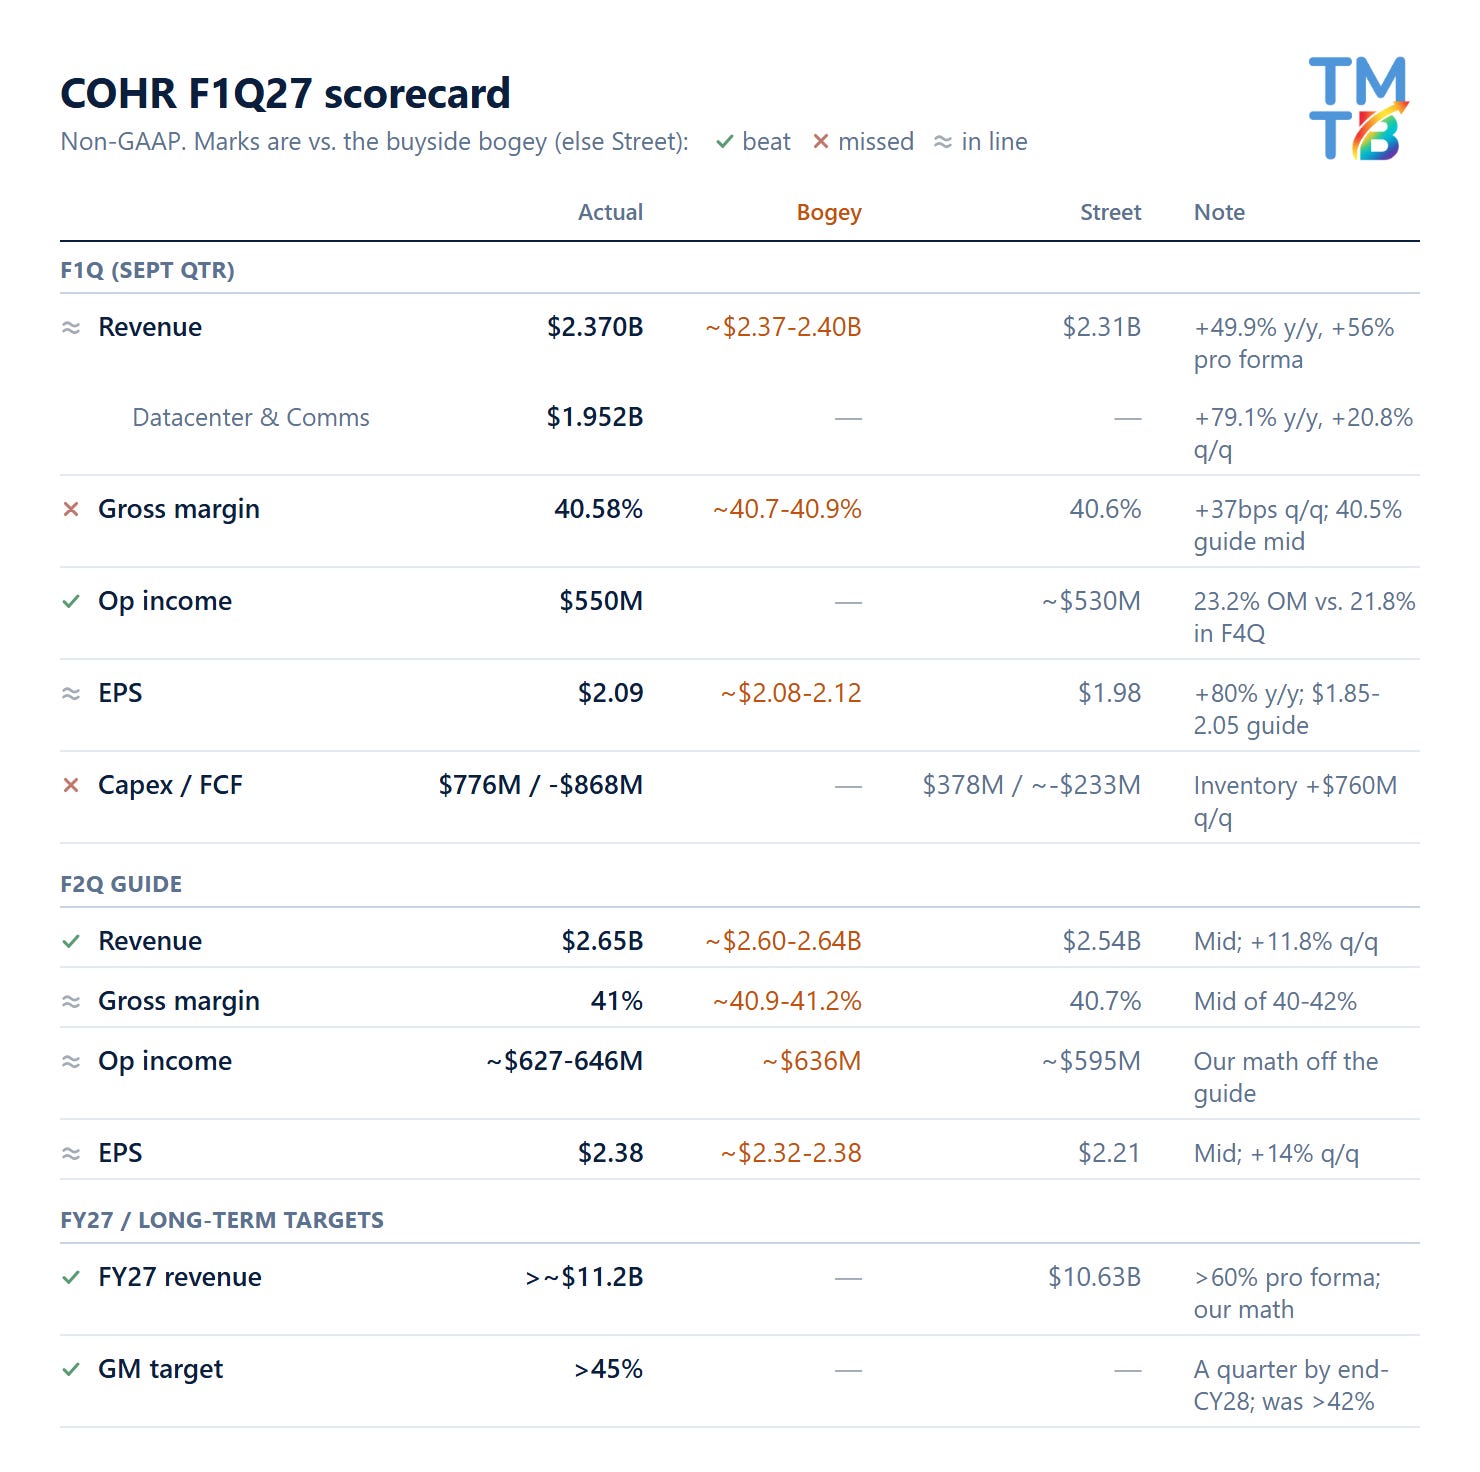
COHR +7.6%: In line on the quarter (GM missed by ~10-30bps), better guide. DC& Comms (+79% y/y) drove F1Q, and the Dec-Q guide beat the bogeys ($2.65B mid vs. ~$2.60-2.64B) with profit in line (op income ~$627-646M at the mids vs. ~$636M at the bogeys). The firsts: >$100M of PhotonLink (CPO) revenue in the March-Q, a ~$20B, five-year PhotonLink LTA from CY28 (customer unnamed), and FY27 pro forma growth >60%, which puts it at >~$11.2B on the ~$7.0B FY26 base vs. Street $10.63B. On GM, the worry going in, the 6-inch InP savings behind the new >45% target (by end-CY28) are still ahead: the CEO wouldn’t give the internal/external laser mix but said it’s “about the same” as a year ago, as doubled InP output kept pace with transceiver growth.
HFs were short this to fund LITE longs before the MRVL deal, and it fell 6% today with semis on post-election data center worries. Asked about them, the CEO said “almost every LTA” carries an upfront customer payment to help fund capacity; prepayments rose $270M in F1Q, a third of capex. Overall, better than feared, and it de-risks 2027-28 demand. AMD and ANET finished green despite the semis blood bath today, so would imagine should hold in ok tomorrow.
You are reading TMTB Pro. Please contact sales@tmtbreakout.com for more info or a trial.
HUBS -7.7%: Put simply: the slowdown doesn’t end in 4Q feeding the AI loser bear case. 3Q grew 17% cc, beating the ~15.5-16% bogeys, but the 4Q guide of 12% missed the ~14.5-15%, which mgmt put on AI changing how customers find and buy software. KPIs got cut too: the CFO now sees FY NRR down ~2pts, net new ARR down y/y and 4Q net adds “below the 5,000 level”. Asked if 2027 starts at 12%, below the ~13% bar, she said the headwinds “will continue in Q4 and into 2027”; mgmt wouldn’t say if trends stabilized, give a 2027 number before February or date its lower-ASP seats-plus-credits pricing beyond new EMEA customers.