

AMAT +1.1%: Decent enough, not a blowout. DRAM finally showed up, but revenue was a touch light of the bogeys and the Jan-qtr guide only inline with them.
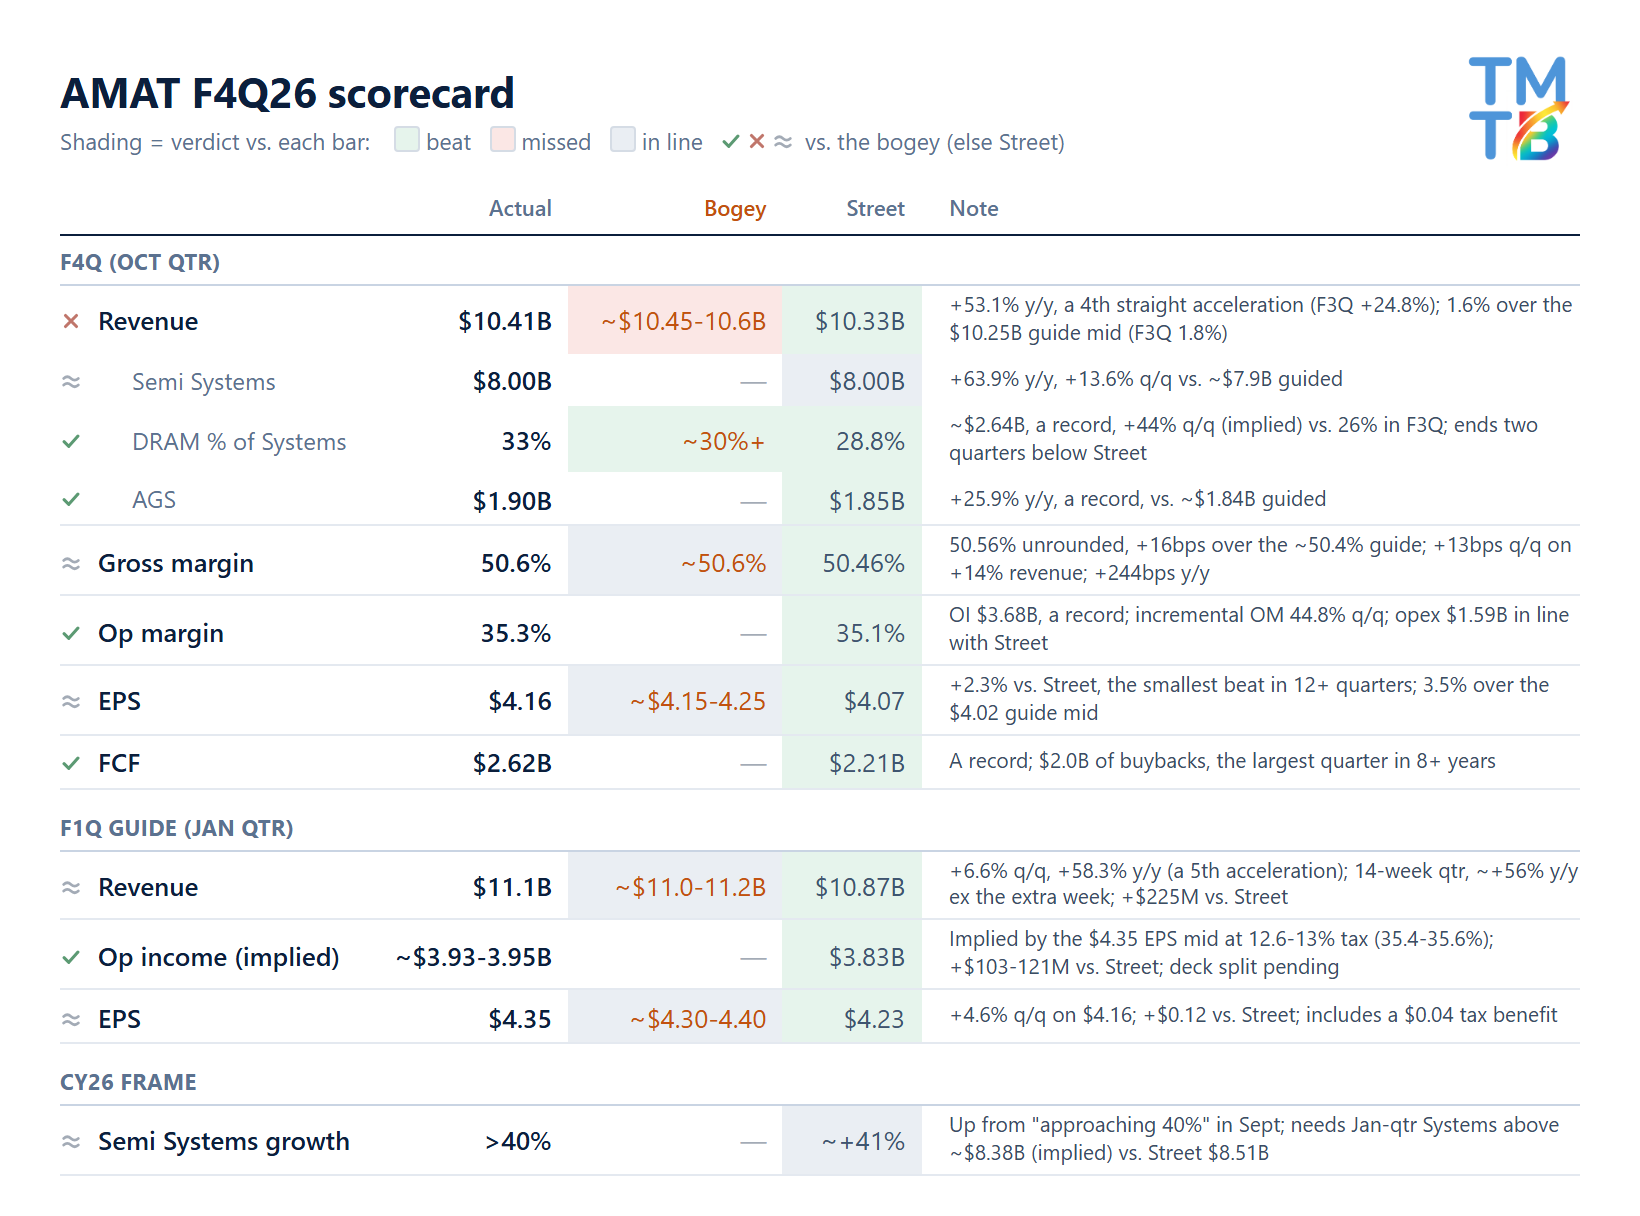
F4Q revenue of $10.41B (+53% y/y, a 4th straight acceleration) beat Street ($10.33B) but missed the ~$10.45-10.6B bogeys, with DRAM at 33% of Semi Systems revenue, which beat Street (28.8%) and the ~30%+ bogey. GM of 50.6% beat Street and was in line with the bogey, and EPS of $4.16 beat Street ($4.07) and was in line with the ~$4.15-4.25 bogeys.
The Jan-qtr guide (a 14-week quarter) of $11.1B ± $0.5B beat Street ($10.87B) and was in line with the ~$11.0-11.2B bogeys, and EPS of $4.35 ± $0.20 beat Street ($4.23) and was in line with the ~$4.30-4.40 bogeys.
CY26 Semi Systems growth is now "more than 40 percent" (CEO; "approaching 40%" in September, Street ~41%), but the release has no 2027 line (August's called for "another strong growth year"). Key for call will be the CY27 framing
Bulls will point to a 4th straight y/y acceleration (+53%), DRAM at a record ~$2.64B (+44% q/q), a Jan-qtr guide $225M above Street that accelerates again (+58% y/y, ~+56% ex the extra 14th week), CY26 Systems now “more than 40 percent” and record FCF of $2.6B with a $2.0B buyback.
Bears will lean on revenue missing the bogeys on the smallest beat vs. Street since the F2Q25 miss (+0.8%; EPS +2.3%, the smallest in 12+ quarters), foundry-logic down ~2% q/q in dollars (our math), GM up just 13bps q/q on +14% revenue, ~$0.14B of the guide from the extra week, no 2027 line to set against the ~$210-230B C27 WFE bogeys, and China still rising in dollars (+5% q/q) into new export controls.
CSCO +1.5%: Big beat and raise: a 4th straight acceleration, a record OM, and this time the GM guide beat Street.
Should be good enough after expects were lowered heading in. However, stock selling off a a bit after initial pop as they dropped the product orders bullet from the release - will be key on the call. Bogeys low 30s…