

Things not getting much better following AMZN and INTC in Tech land with SNDK only name in the green tonight (and barely)
SNDK +1%: Ok looking print (best of the night) with better top line and mixed GM. F1Q revenue of $11.03B beat Street ($10.74B) and was in line with the ~$10.9-11.2B bogey, but GM of 85.1% beat Street and missed the ~86% bar, and the F2Q guide of $12.2-12.6B / 84.5-85.5% GM / $55-57 EPS beat Street ($12.08B / 84.7% / $52.94) and hit the top of the ~$12.2-12.4B bogey, while the flat GM guide sits well short of the 86.5-87.5% bulls wanted. Datacenter did the work (+61% q/q) as Edge and Consumer missed. NBMs: no new signings, still 8 customers and the $93.9B floor minimum vs. bulls wanting more than 8; RPO $88.9B vs. $91.1B pro forma in Aug. ... 8 for 1 stock split coming in November.
Not crowded coming in, but the stock ran +12% the two days before today’s -5%, and a GM guide that’s flat q/q not exciting and bulls were looking for more pricing flow-through but expects low heading in.
F1Q revenue of $11.03B (+23.0% q/q) beat $10.74B Street and was in line with the ~$10.9-11.2B bogeys, 2.1% above the top of the $10.3-10.8B guide (Aug beat the top by 8.7%).
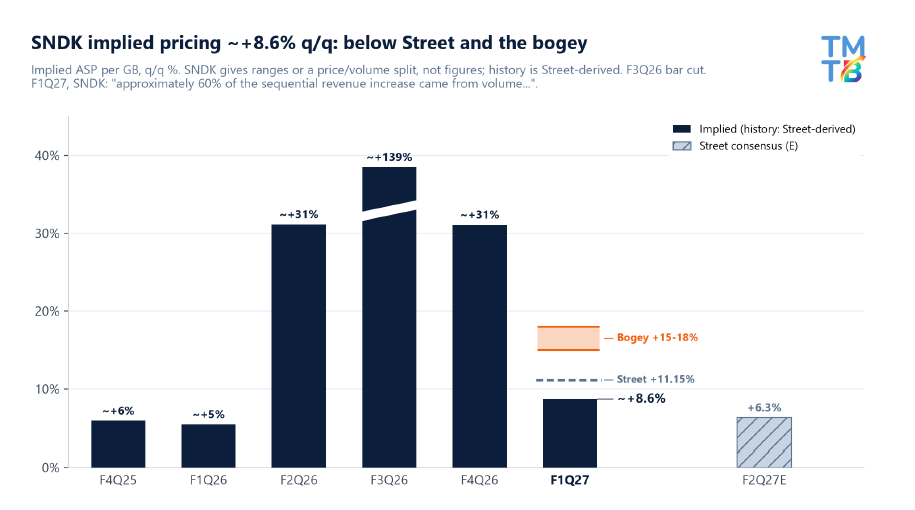
60% of the q/q revenue increase came from volume and ~40% from pricing (Aug: one-third volume / two-thirds price). That’s ~+8.6% pricing and ~+13% bits by our math, vs. Street ASP +11.1% / bits +7.9% and the ASP +15-18% bogey: a volume-led quarter, which is why GM only ticked up.
Datacenter beat at $4.80B (+61% q/q) vs. $4.0B Street (+34%), now 43.5% of revenue (33% in June).
Edge missed at $5.83B (+7% q/q) vs. $6.08B Street (+12%); Consumer missed at $397M (-29% q/q) vs. $584M.
GM beat Street at 85.07% but missed the bogey, ~60bps above Street’s 84.45%, 0.4pt below the 85.5-86.5% bogey and 0.1pt over the 83-85% guide top (84.64% in June, so +0.4pt q/q).
Pure price flow-through on the ~$230M over the guide top would have given ~85.3%, so no cushion showed up from the “prudent” component-cost assumptions.
EPS of $49.51 beat $46.73 Street, in line with the ~$48-50 bogeys and above the $44-46 guide, on 154M diluted shares (~155M guide).
A 14.3% non-GAAP tax rate vs. the 15% guide added ~$0.40 of that.
Opex of $513M was under the $520-540M guide; OM of 80.42% beat Street’s 79.5% (~90bps above).
F2Q revenue guide of $12.2-12.6B ($12.4B midpoint, +12.4% q/q) beat $12.08B Street and hit the top of the ~$12.2-12.4B bogeys.
GM guide of 84.5-85.5% (85.0% midpoint, flat with F1Q’s 85.07%) is ~30bps above Street’s 84.7% but 1.5pt below the low end of the 86.5-87.5% bogey.
EPS guide of $55-57 ($56 midpoint) beat $52.94 Street and is at the top of the ~$54-56 bogeys, on ~151M diluted shares (154M in F1Q). Opex guide $540-560M, tax 14.3%.
Part of the Dec-Q step-up is consumer seasonality (F2Q26 Consumer $907M vs. $652M in F1Q26), not all pricing.
FY27 Street of $49.12B now needs $25.7B in 2H vs. $26.3B before, or ~$12.8B a quarter vs. the $12.4B Dec-Q midpoint.
NBMs: no new signings, still 8 customers and the $93.9B floor minimum vs. bulls wanting more than 8; RPO $88.9B vs. $91.1B pro forma in Aug. Bit coverage unchanged at ~1/2 of FY27 and ~2/3 of FY28 (bogey: above ~2/3 for FY28); $16.5B of financial guarantees, 4+ year average duration. The two Q1 closes were already announced in Aug; “active conversations” on extensions and new NBMs, and the pipeline “exceeds our supply through the end of the decade”.
Cash: adj FCF missed at $5.70B vs. $5.93B Street (reported FCF $6.31B, with receivables up $1.88B).
Bought back $5.0B (3.2M shares) vs. $4.5B in June, which leaves ~$10.5B of the $15.5B authorization by our math.
8-for-1 stock split: record date Nov 9, trades split-adjusted from Nov 20.
RDDT -7%: US DAUq fell to 50.7M (-2.5M q/q, -2% y/y) vs. 53.5M Street and the +0.1-0.2M bogey, and the letter says total DAUq could fall by a low-double-digit % in 4Q on search referrals. Revenue of $895M beat Street ($877M) but missed the ~$935-945M bogeys, and the 4Q guide of $1,000-1,030M missed both $1,044M Street and the ~$1.07-1.08B bogeys. Logged-in and app DAUq grew q/q, so the call is all about how big the logged-out hole gets.
Stock was short-skewed coming in and ~50% off its highs (-3.8% today, -19% since 10/12), but this is worse than bears were looking for - US users fell 2.5M vs. the 0.3M in Q2 and the guide takes away the revenue cushion too. Huffman has an uphill battle on the call.
Key quote: “Our search referral traffic was down meaningfully in Q3, with the decline accelerating later in the quarter. The biggest impact was on logged-out and web traffic, but some of the impact flows through to logged-in and App traffic, since search referral is a common source of reengagement for users… These declines have continued into the early part of Q4. During October, we have seen that search traffic has dropped by more than 1 million referrals on average per week. If this rate of decline continues, current trends would suggest that total DAUqs could fall in Q4, by a low-double-digit percentage from our current base of 130 million DAUqs.”