

NVDA +2.6%: Clean beat and a Jan-qtr guide at the top of the buyside bogey, but GM a bit light. All in-all looks really solid with biggest beat over midpoint of the guide since 3Q’25. Bigger issues at play here obviously and key will be the call and reiteration of ‘27 guide of 70%
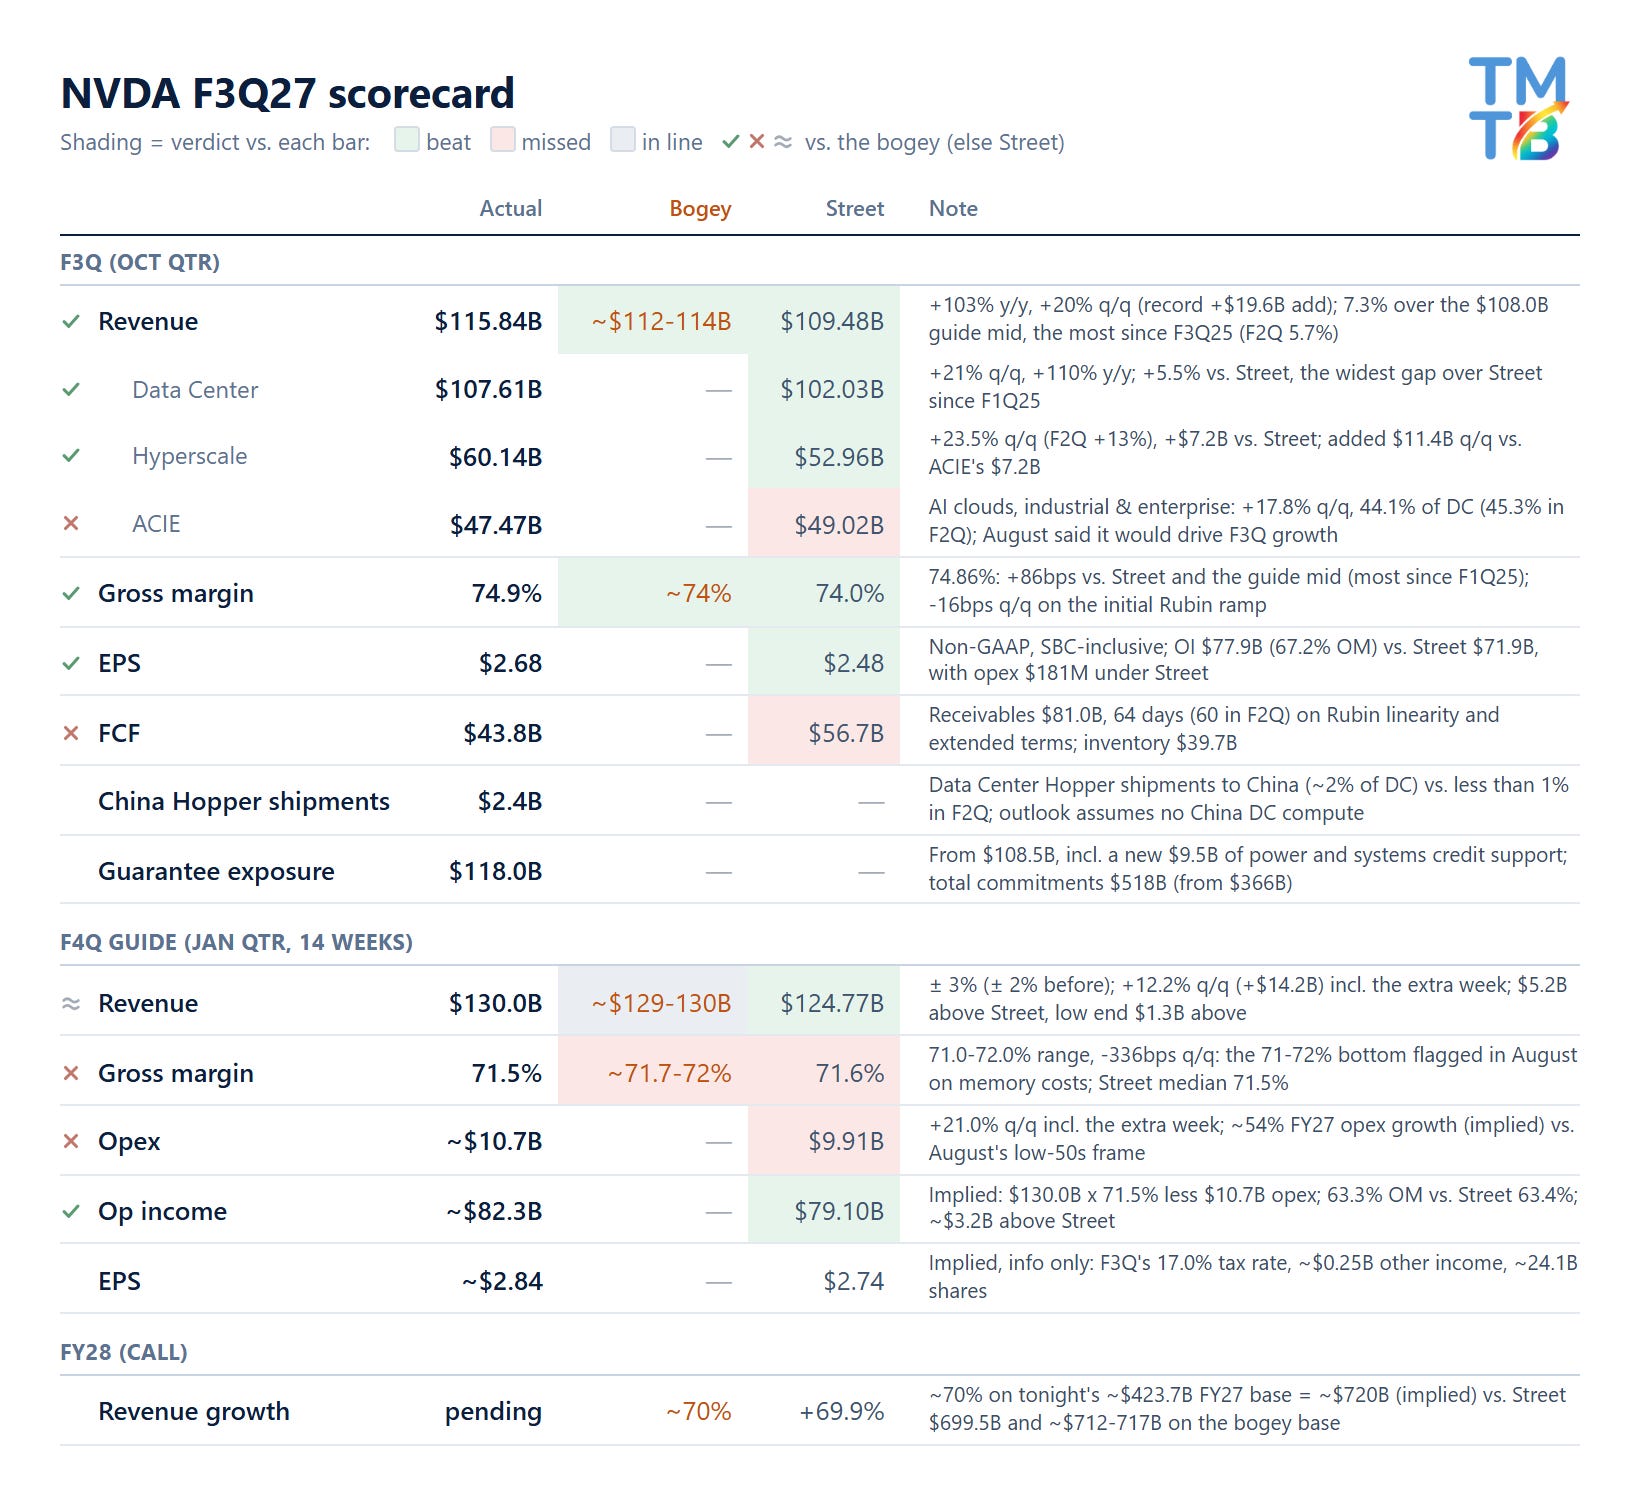
F3Q revenue of $115.8B (+103% y/y) beat Street ($109.48B) and the ~$112-114B bogeys, a 7.3% beat on the $108.0B guide mid vs. 5.7% in F2Q (the biggest since F3Q25) and a record $19.6B q/q add.
Data Center of $107.6B beat Street ($102.03B) on Hyperscale ($60.1B vs. Street $52.96B), while ACIE (AI clouds, industrial and enterprise) missed ($47.5B vs. $49.02B).
GM of 74.9% beat Street (74.0%) and the ~74% bogey, and EPS of $2.68 beat Street ($2.48).
The Jan-qtr revenue guide (a 14-week quarter) of $130.0B ± 3% (widened from ± 2%) beat Street ($124.77B) and was in line with the top of the ~$129-130B bogeys. GM of 71.0-72.0% (71.5% mid) missed Street’s 71.6% mean (in line with the 71.5% median) and the ~71.7-72% bogeys; with $10.7B of opex (Street $9.91B) that’s implied OI of ~$82.3B, above Street’s $79.10B.
The CFO Commentary: “We plan to file our 10-Q in the coming weeks.”
“We have partnered with leading neoclouds to enable broader access to our AI infrastructure to serve AI startups, model builders, enterprises, research organizations and sovereign customers. Our commitments take effect only if the neoclouds secure financing to purchase the data center infrastructure products and the related compute capacity is deployed, made operational, and accepted by us. The maximum commitment presented assumes these contingencies are satisfactorily resolved. If they are not timely resolved, the amount and timing of our commitments may be affected, and certain commitments could be reduced or eliminated. Under these agreements, we will earn revenue on the upfront sale of our infrastructure and if certain criteria are met, we will participate in revenue share generated by the neoclouds from their third-party customers.”