

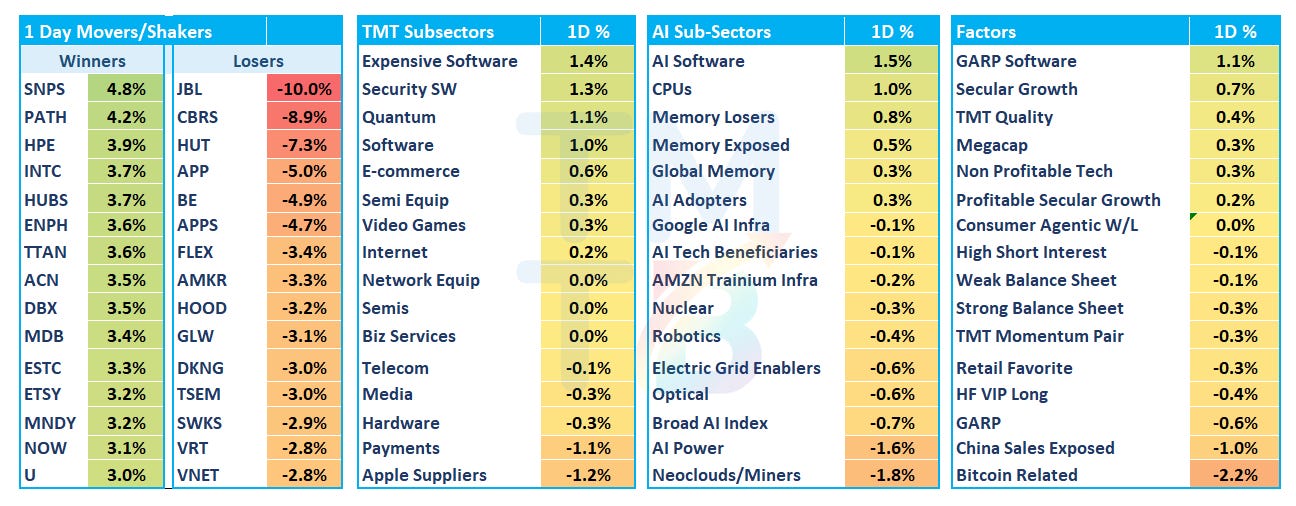
Good afternoon. QQQs +25bps on the last day of the quarter, fading from +97bps at the highs with most of the give-back in the last 40 minutes. Software over AI SI infra was the trade today: software +1.2% led, with the names hit by META’s enterprise push and OAI Dev Day bouncing hardest (MNDY +3% HUBS +3.7%; PATH +4.2%), while semis +21bps lagged (AVGO -1.1%; ASML -1.2%; SKHY -1.4%) and AI infra/power bled (JBL -10.1% despite a decent set of numbers & CBRS -8.9% reports they won’t be used in Ultrafast led the way lower)
Mega caps held in (AAPL +1.1%; AMZN +1%; GOOGL +93bps; MSFT +77bps), META -1.8% the lone man out. GOOGL was up 2% heading into the close before Bloomberg reported they were “grappling with internal skepticism over how well the flagship artificial intelligence model performs in key areas.” Then GOOGL actually dropped Gemini 4 “Argon” post-close and it actually looks pretty solid and right around the frontier on benchmarks:
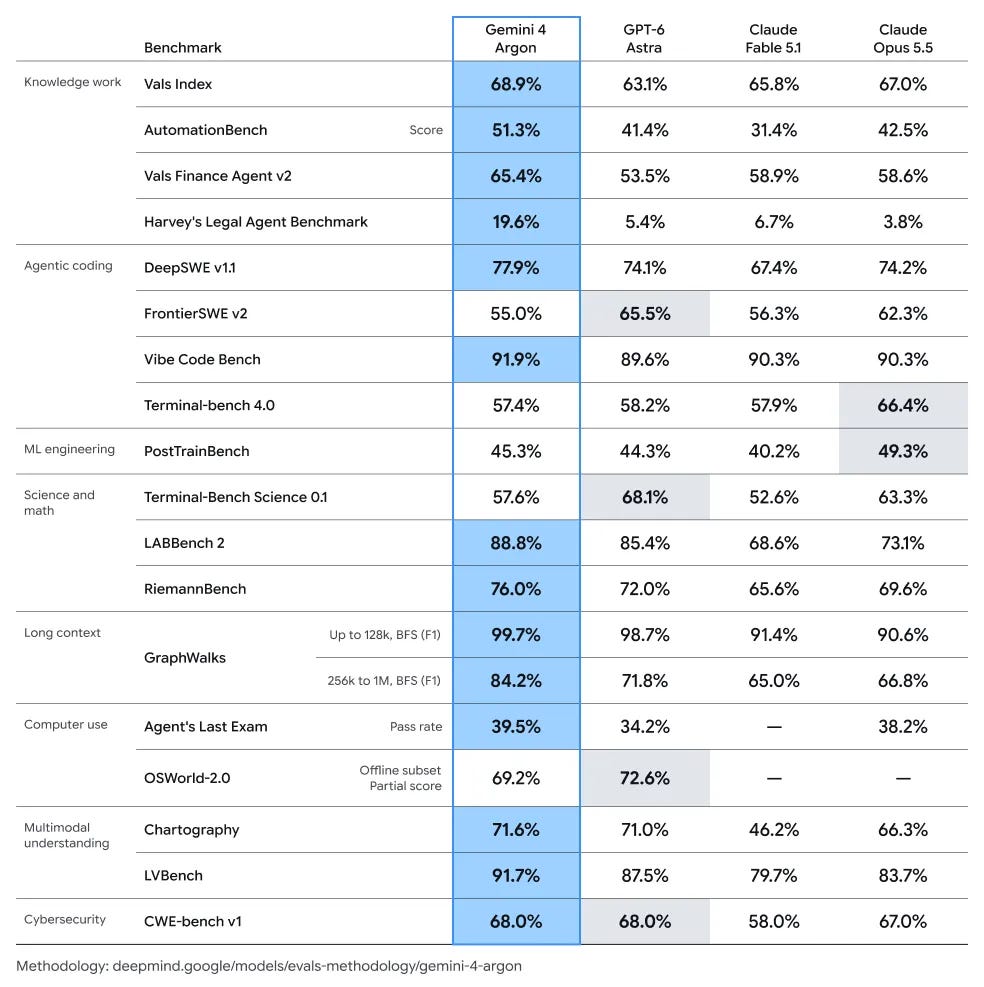
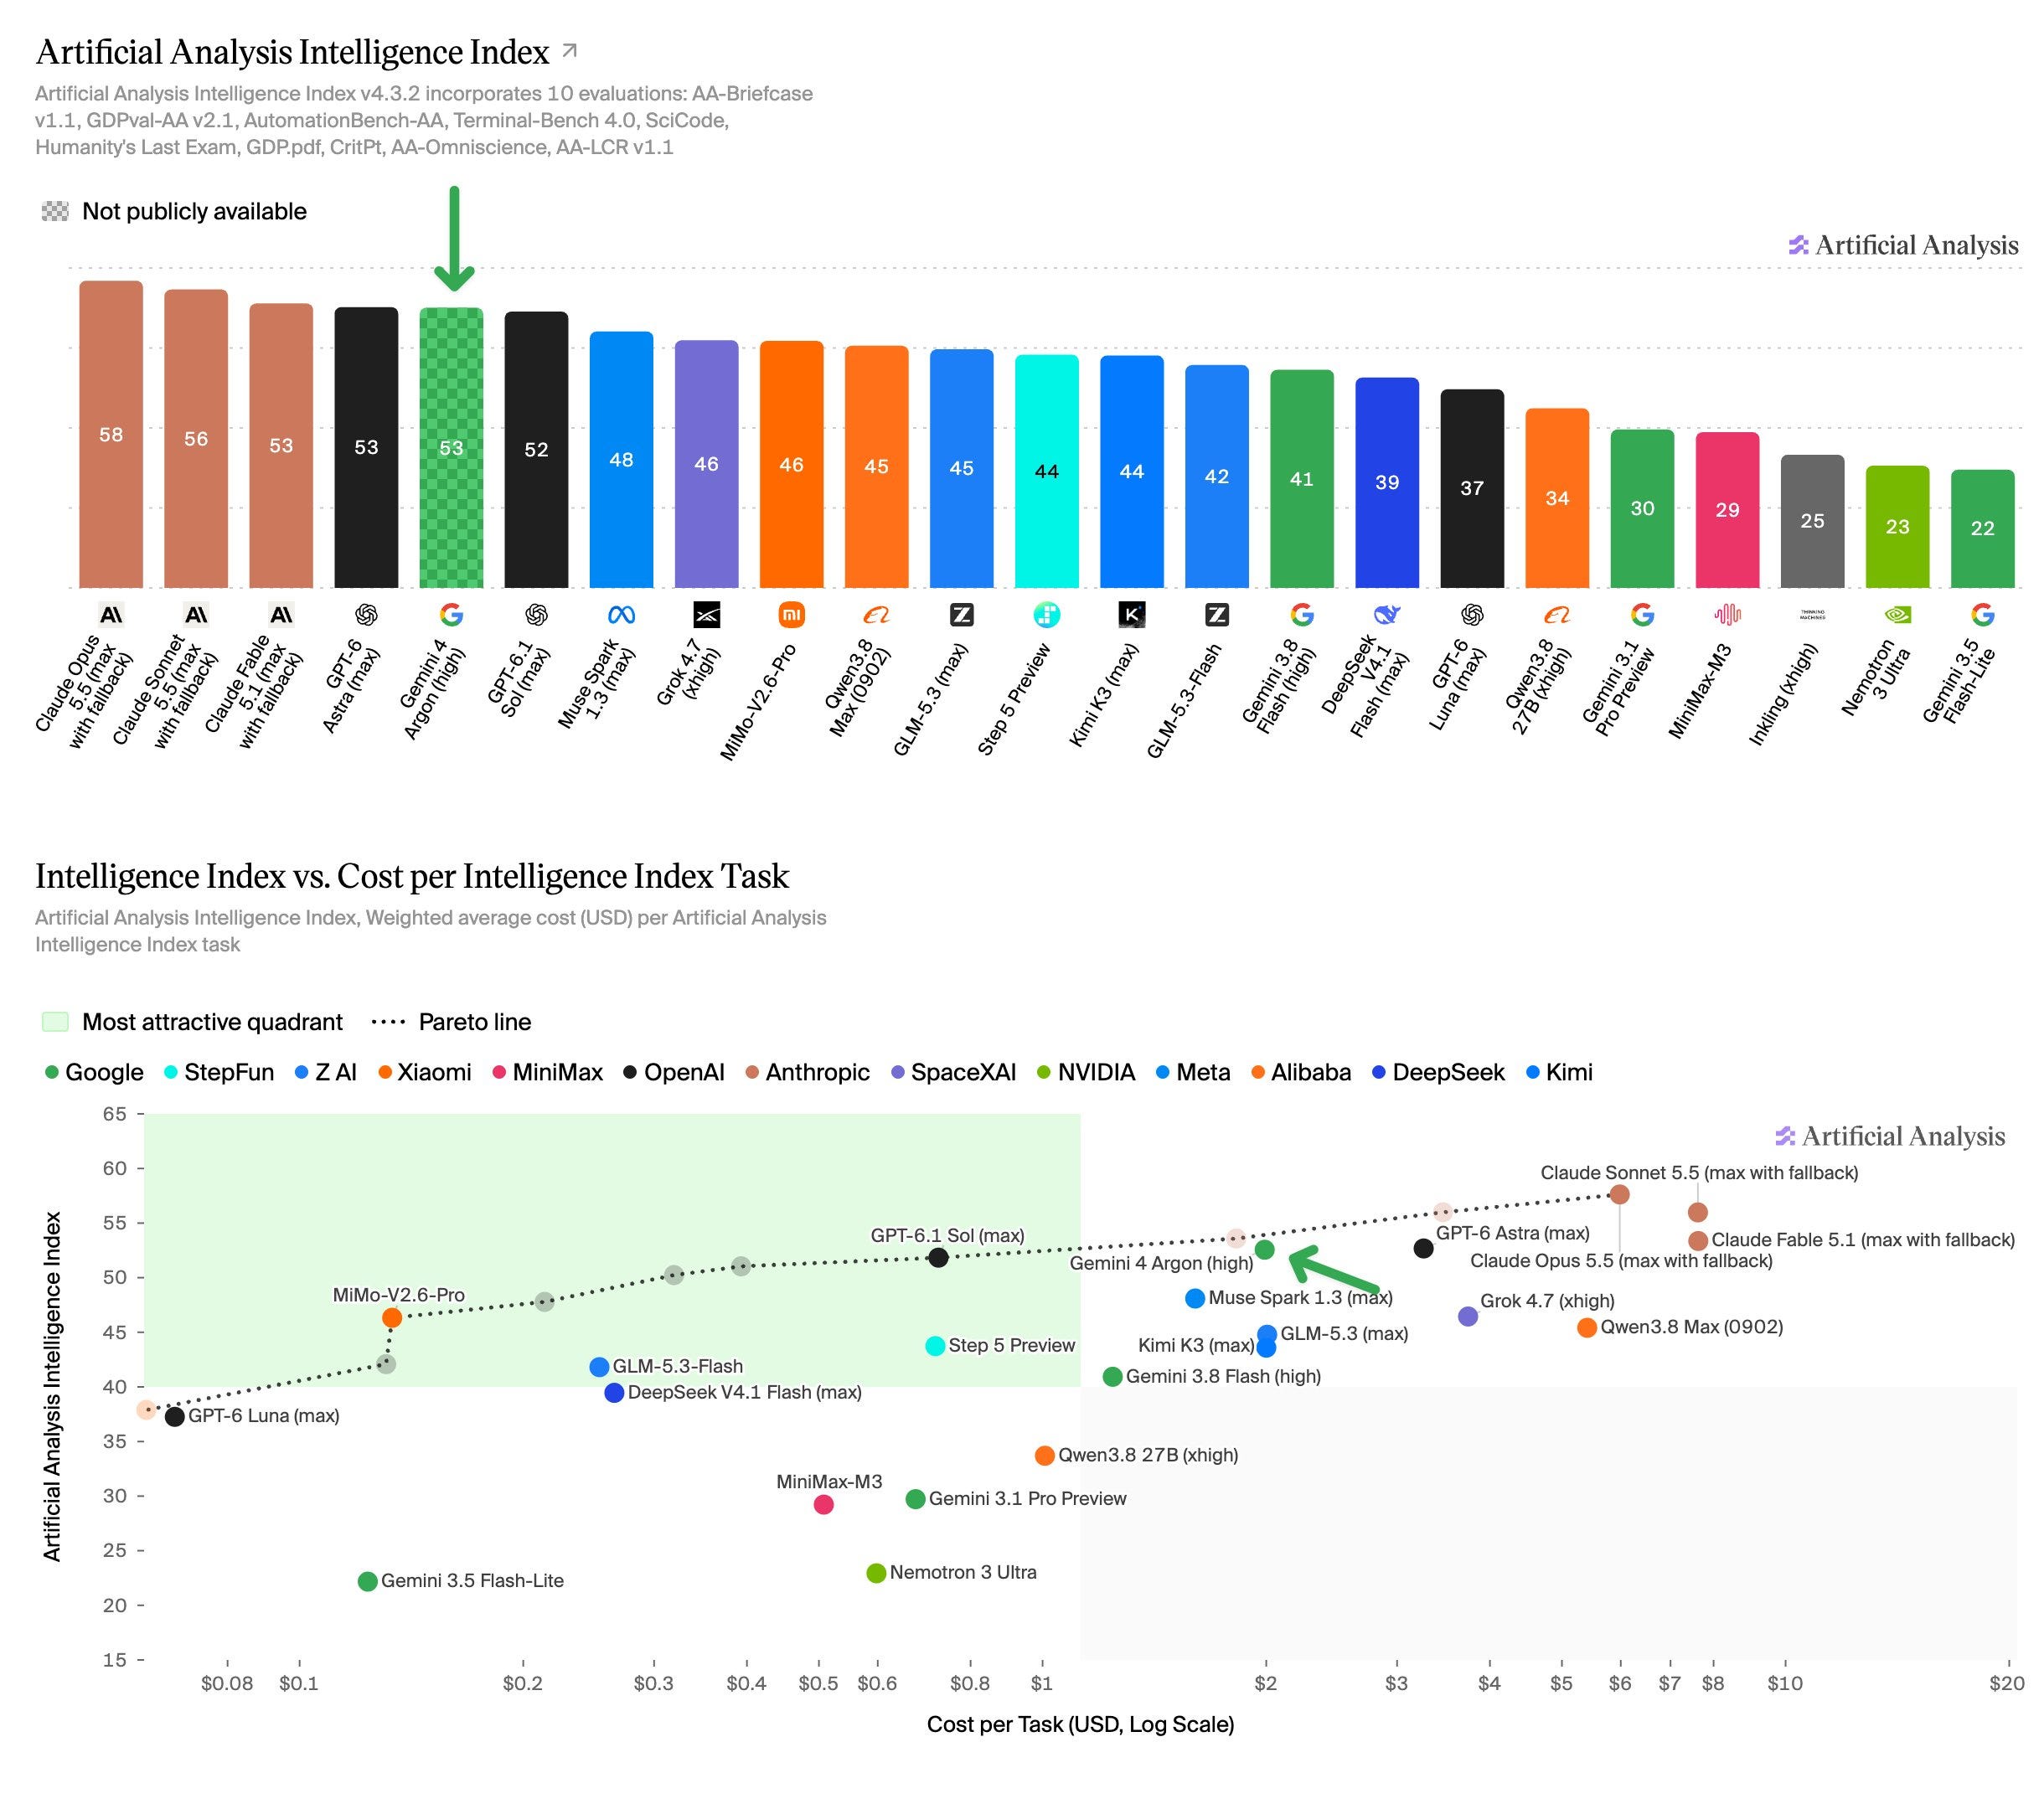
Cost is same price as Opus 5.5. The glass half full from bears will likely be: still 1-2 months behind and now what’s the catalyst for bulls to look forward to while search fears still abound…
Lets touch quickly on the macro today as its top of mind for investors: another bear steepener, this time on softer data. August core PCE came in at +0.2% m/m and 3.0% y/y vs. 0.3%/3.3% expected (a 6-month low, helped by a BEA methodology change) and ADP was +90K vs. ~70K; yields dipped on the print and then turned higher, with the 2Y -1bp to 4.88%, the 10Y +3bps to 5.29% (highest since 2007) and the 30Y +5bps to 5.64%. As @jturek18 on X put it (h/t Arun Dhar in TMTB Slack here): “dovish data right now is more pressure on the backend than it is relief on the front end.” Fed pricing went the other way: ~35% odds of a hike on 10/28 (from ~50% Tuesday and ~71% Monday), ~30bps of hikes priced for the rest of 2026 and another ~60bps in 2027. Just before the close (~3:50pm), Trump said on Truth Social that Fed Governor (and former Chair) Powell should resign over the Fed HQ renovation after an inspector general report, or be sued “for either corruption or incompetence.” WTI +1.4% to ~$90.6 as Trump denied an Axios report that he’d ease Iran sanctions. BTC flat at ~$83.7K.
Post-close:
MU +2%: Big revenue/EPS beat and strong FQ1 guide, with gross margin the only real blemish.
MU beat across the board, with FQ4 revenue well above Street and EPS above even the buyside bogey, while FQ1 revenue/EPS guidance also cleared expects. The one nit is gross margin guide: FQ4 hit the ~87% bogey, but FQ1 guides down to 86.25% vs. ~87-88% buyside, although initial read seems like it’s all due to mid-shift to HBM and they are saying Q1 will be floor for GMs in ‘27. Call ongoing.
“We anticipate fiscal Q1 to be the floor for gross margins in fiscal 2027. As Sanjay mentioned, we made a decision to increase fiscal 2026 incentive compensation in fiscal Q4. Most of the increase in fiscal 2026 incentive compensation pertaining to manufacturing was absorbed into inventories in fiscal Q4. As a result, the effects from the sale of these higher cost inventories principally impact fiscal Q1 gross margin. Fiscal Q2 benefits from less of this fiscal Q4 related compensation expense, but this benefit is offset by the impact of higher fiscal 2027 incentive compensation. We expect higher gross margins beyond fiscal Q1 for the remainder of fiscal 2027, with a more moderate rate of price increases.”
FQ4 revenue: $54.23B vs. ~$51B Street
FQ4 EPS: $33.42 vs. ~$31.50 Street / $33+ bogey
FQ4 gross margin: 87.0% vs. ~87% bogey
FQ4 operating margin: 82.3%
FQ4 operating cash flow: ~$44B
FQ4 adjusted FCF: ~$33B
FQ1 revenue guide: $60-63B, midpoint $61.5B vs. ~$57B Street / ~$60B bogey
FQ1 EPS guide: $37.15-39.15, midpoint $38.15 vs. ~$36 Street / ~$37.5 bogey
FQ1 gross margin guide: 86.25% vs. ~87-88% bogey
Let’s get to the good stuff…
AI/SEMIS
SNPS +4.8% had a busy day: a $1B+ AWS license deal spanning Graviton, Trainium and Nitro generations pre-market, then an analyst day with FY27 guidance two months early (revenue +15% to $11.15B vs. ~11% consensus; EPS +27% to $19.08; a $1B buyback) and the long-term revenue CAGR raised to mid-teens through 2030 from double digits. It also announced “GPT-Synopsys” with OpenAI, an AI model for chip design where OpenAI pays a training subscription plus a revenue share, structured so it “will not be cannibalizing our business” per CEO Sassine Ghazi. In the analyst-day thread in Slack here, Marengo flagged the new custom-silicon IP business getting to ~$1B of revenue by FY30, while EM countered that IP growth was in line with the high teens already expected. Up +7.3% at the highs; CDNS +1.9% in sympathy.