

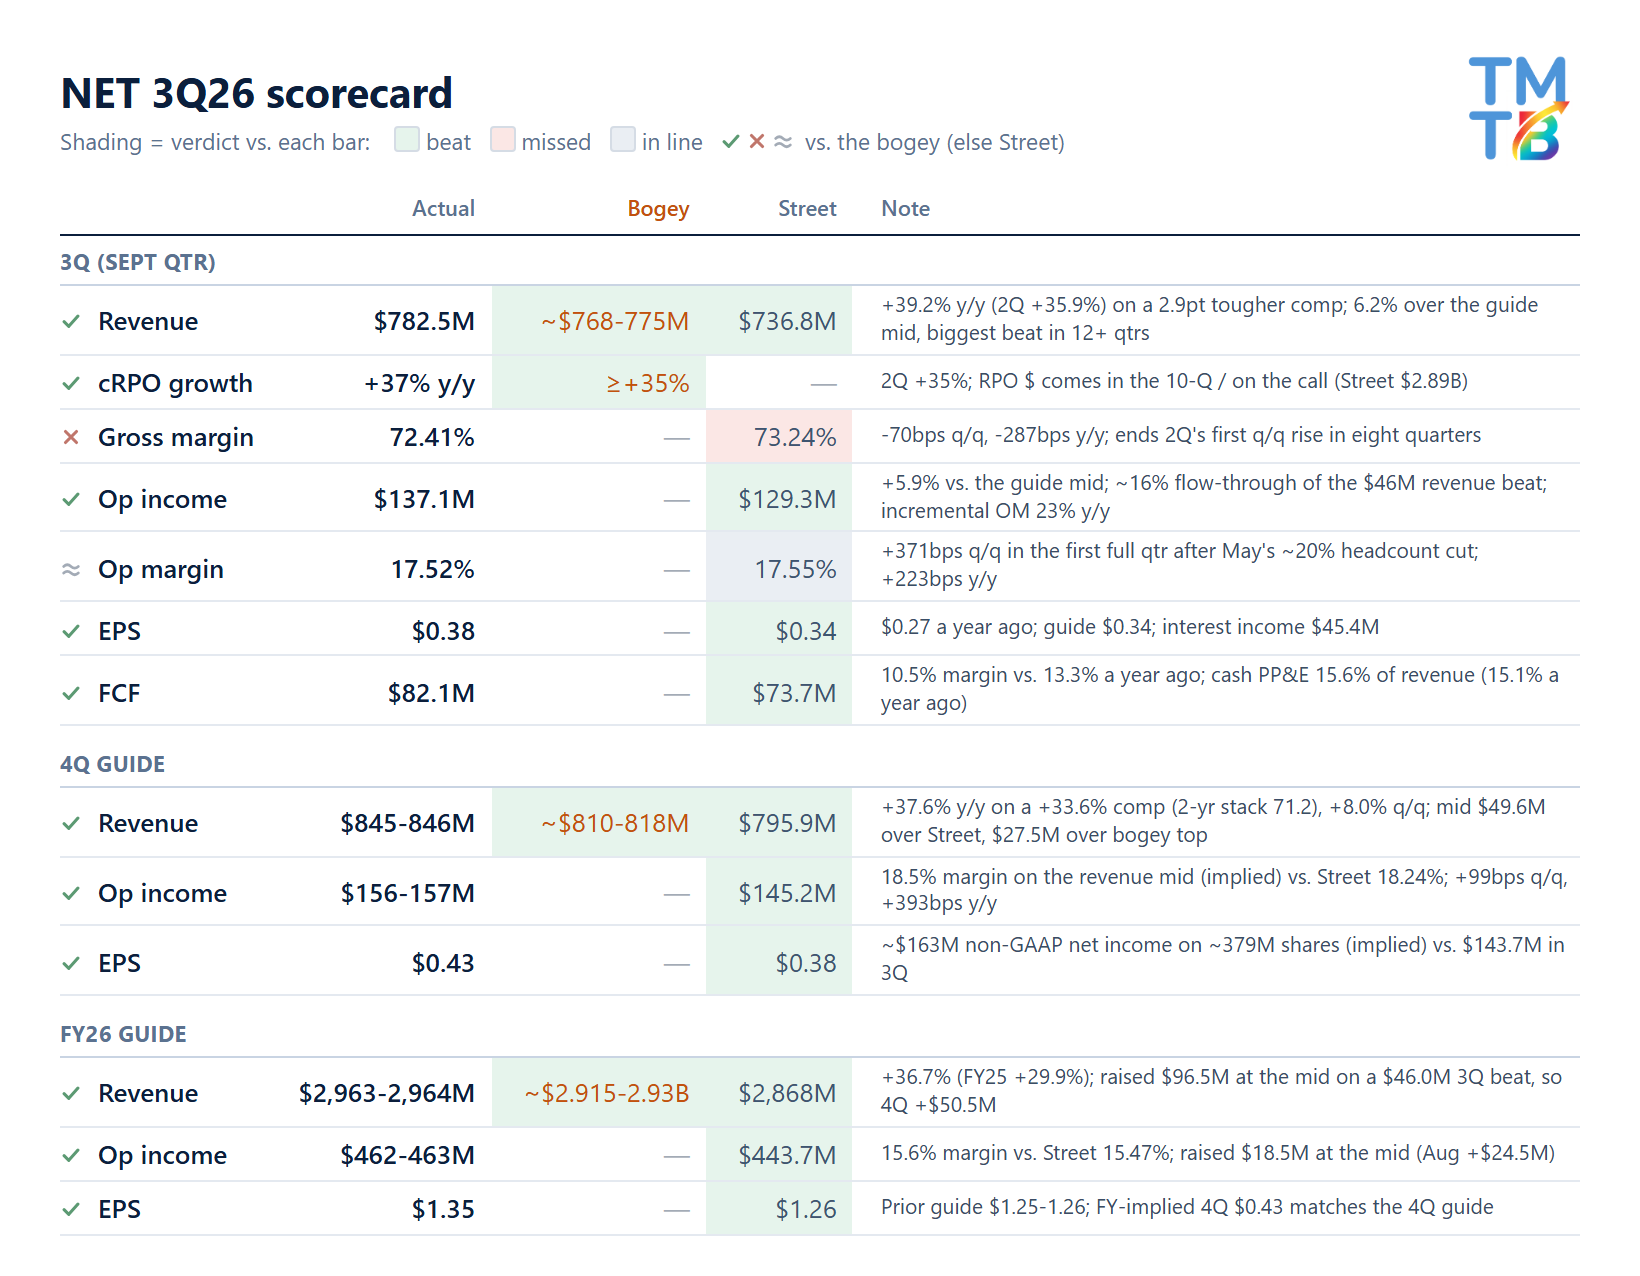
NET +18%: Best sw print of the season and arguably best print NET has put up in a long time. Clean beat and raise and acceleration on tougher comps. 3Q revenue of $782.5M (+39.2% y/y vs. 35.9% in 2Q, the 5th acceleration in 6 quarters and the “fastest revenue growth in nearly four years”) beat Street ($736.8M) and the ~$768-775M bogeys, a 6.2% beat on the guide mid, the biggest in 12+ quarters. cRPO growth accelerated to 37% vs. the ≥35% bogey. The 4Q revenue guide of $845-846M (+37.6% y/y) is ~$50M above Street ($795.9M) and ~$28M above the top of the ~$810-818M bogeys, FY was raised $96.5M at the mid (vs. $58M last quarter), and the 4Q op income guide of $156-157M (18.5% margin) beat Street’s $145.2M (18.2%). The blemish is GM: 72.4%, 84bps under Street and -287bps y/y.
With Q4 guided at 38%, implied exit rate would be low 30s and so bulls will think Q1 at least mid 40s growth. Tough market so who knows what happens tomorrow, but definitely a great print. Positioning had come down hard coming in (-21% in the five sessions since 10/29, incl. -8% today with QQQ -6.5%, and fast money out, and this is the print bulls needed: growth re-accelerated on a tougher comp and the 4Q guide is above the bogeys before their usual beat. Bulls will point to revenue +39.2% against a 3Q25 comp 2.9pts tougher than 2Q’s (2-yr stack 69.9 from 63.6), current RPO growth up to 37% from 35%, and a 4Q guide of +37.6% on the year’s toughest comp (4Q25 +33.6%) that tops 3Q’s growth with just a 1.2% beat on the mid (their smallest in 12 quarters was 1.5%). Bears will lean on GM of 72.4% (84bps under Street, -287bps y/y), an op margin only in line with Street at 17.5% even though revenue beat the guide mid by $46M (only ~16% of that fell to op income), FCF margin of 10.5% vs. 13.3% a year ago.
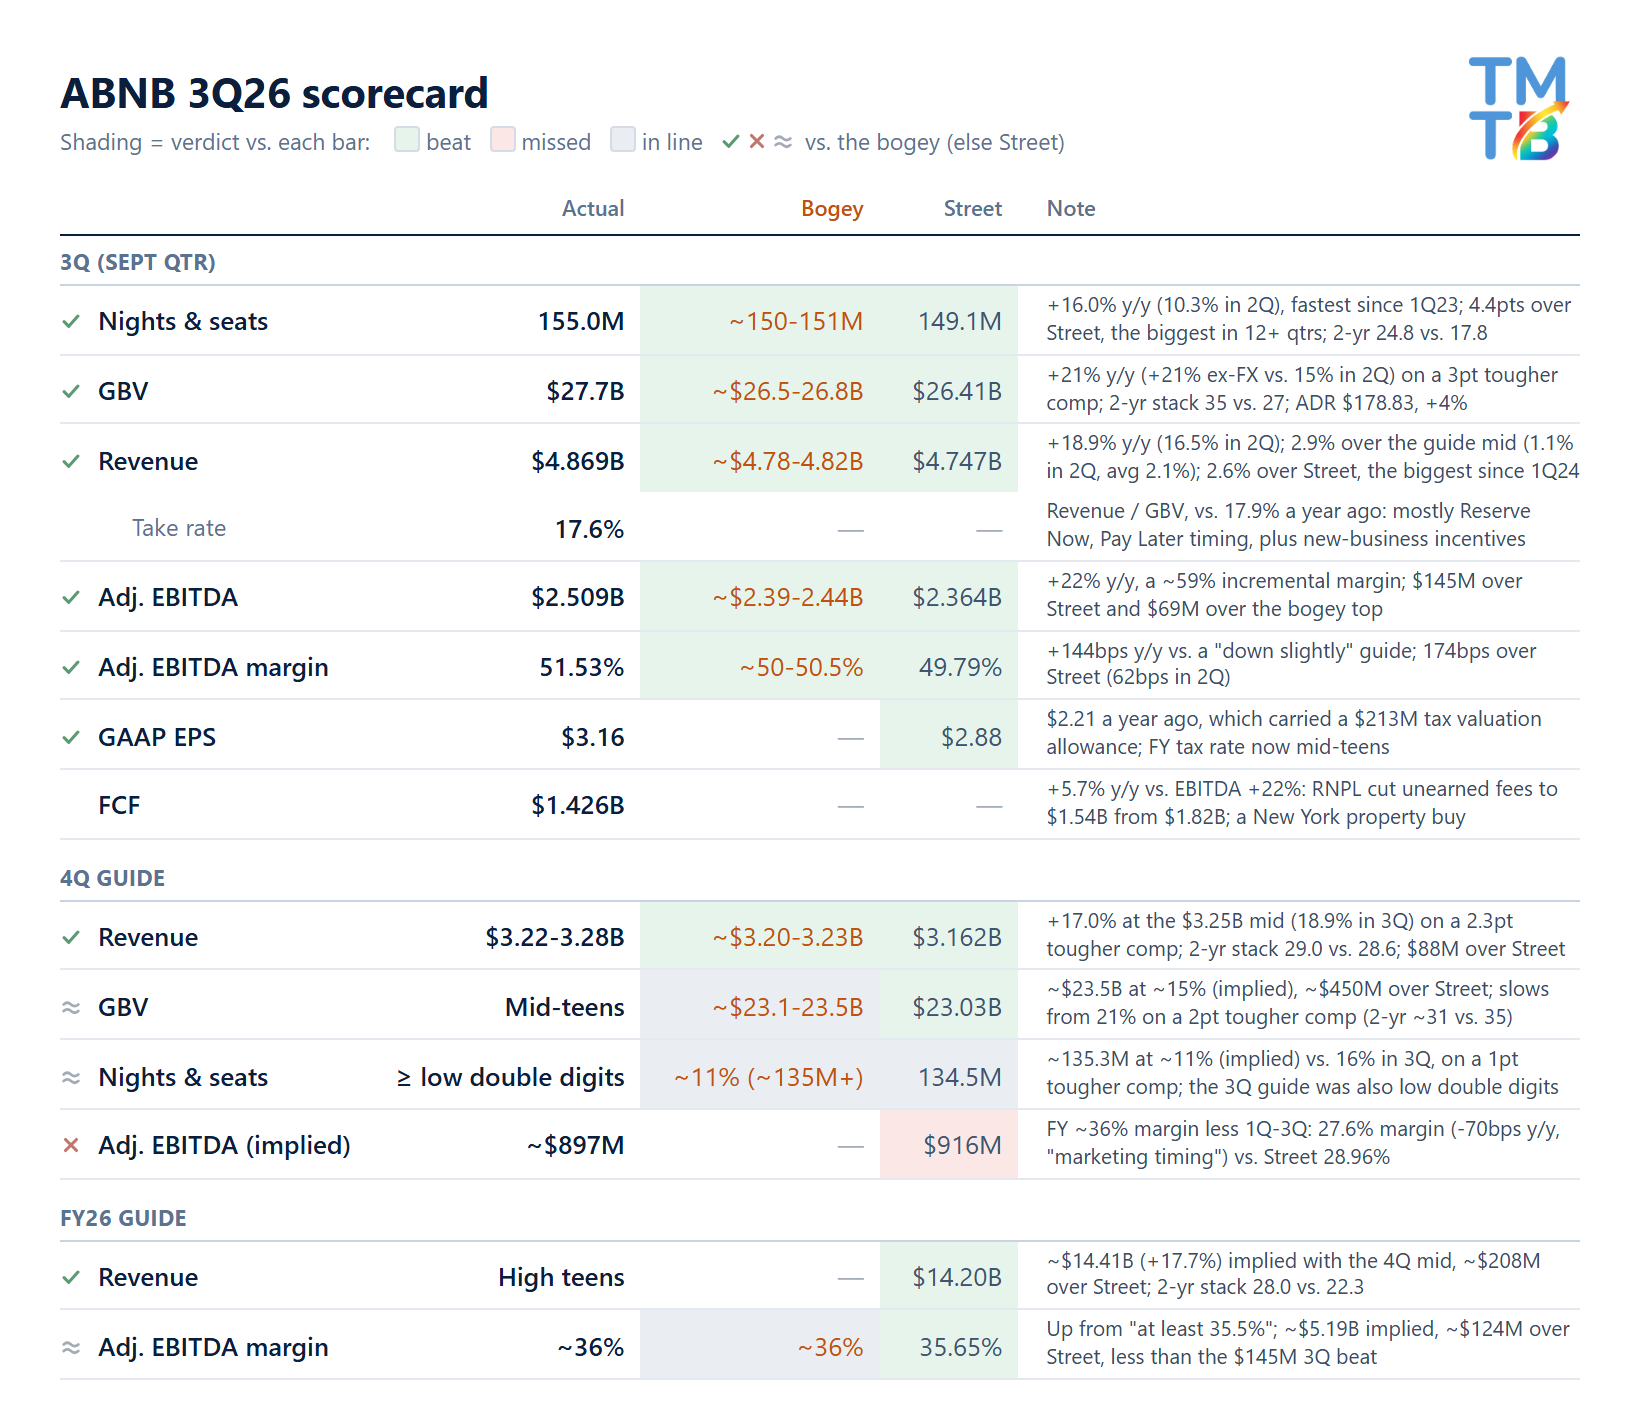
ABNB +12%: Blowout 3Q acceleration and EBITDA with solid Q4 top line guide that implies more accel. Nights grew 16% (155.0M), up from 10% in 2Q and the fastest since 1Q23, vs. Street 149.1M (+11.6%) and the ~150-151M bogeys. GBV grew 21% ($27.7B) vs. Street $26.41B and the ~$26.5-26.8B bogeys. Revenue of $4.869B beat Street ($4.747B) and the ~$4.78-4.82B bogeys, and adj. EBITDA of $2.509B (51.5% margin, up y/y when the guide said down slightly) beat Street ($2.364B) and the ~$2.39-2.44B bogeys. The 4Q revenue guide of $3.22-3.28B (+17% at the $3.25B mid) beat Street ($3.16B) and the ~$3.20-3.23B bogey. 4Q GBV is guided to mid-teens growth on at least low double-digit nights, above Street and at the top of the bogeys. The FY margin goes to ~36% (the bogey), and there’s a new $12B buyback. The one soft spot is 4Q profit: the margin is guided down slightly y/y on marketing timing, which implies ~$0.90B of 4Q EBITDA vs. Street $916M.
Crowded long that sold off into the print (-3.5% today with EXPE -14% on its 4Q guide, ~11% off the August high), and this is the print bulls wanted. Bulls will point to nights at +16% vs. a “low double-digit” guide, a 5.7pt acceleration on a 1.4pt tougher comp (2-yr stack 24.8 from 17.8), EMEA accelerating to mid-teens, North America at a four-year high, a 4Q revenue guide $88M above Street and a $12B buyback (~12% of the market cap). Bears will lean on 4Q profit: a ~36% FY margin on ~$14.41B of FY revenue (1Q-3Q actuals plus the 4Q mid) leaves ~$0.90B of 4Q EBITDA (27.6% margin, -70bps y/y) vs. Street’s $916M, so FY EBITDA rose only ~$124M vs. Street after a $145M 3Q beat. They’ll add GBV guided to slow to mid-teens from 21%, and the take rate (revenue / GBV) down to 17.6% from 17.9% as Reserve Now, Pay Later books GBV ahead of the stay. Reserve Now, Pay Later is pulling bookings earlier (“an extension of lead times”) and has “higher cancellation rates”.
Key quote (letter): “Although we’re closely monitoring ongoing developments in EMEA, underlying global travel demand remains healthy, and our product and growth initiatives continue to deliver results.”
Ops & support fell to 7.4% of revenue from 8.4%, helped by “lower agent contact volume resulting from increased use of artificial intelligence (‘AI’) in community support”.
TEAM -20%: Another sw miss as cloud beat Street but missed the bogeys and decelerated for the first time in six quarters, and the guide beat Street but missed the bogeys too. Cloud revenue of $1,302.5M (+30.5% y/y, from 30.8% in F4Q) beat Street ($1,283.7M, +28.7%) and the ~28.5% guide by 2.0pts, the smallest cloud beat since F3Q25, but missed the ~$1.31-1.32B bogeys (~31.5-32%). Total revenue of $1,772.2M beat Street ($1,712.0M) and was in line with the ~$1.76-1.78B bogeys, with $33M of the $62M beat on the guide midpoint from Data Center. The F2Q cloud guide of ~27% (~$1,355M) beat Street (26.5%) but missed the ~28-28.5% bogeys, and FY27 cloud went to ~26% from 25.5% (just the F1Q beat) vs. Street 25.7% and the ~27% bogey, which leaves the implied 2H at ~23.6% vs. Street’s 24.0%. FY27 non-GAAP OM of ~25.5% (OI ~$1.91B) beat Street’s 25.2% ($1,871M) and hit the low end of the ~25.5-26% bogeys, but the implied 2H OI of ~$855M (~22% margin) sits ~$79M below Street’s ~$934M.